

National Atomic Company Kazatomprom JSC, the world’s largest uranium producer, has moved closer to sealing a massive long-term supply deal with India. The Kazakh state miner announced that it plans to sell a significant portion of its natural uranium concentrates to India’s Department of Atomic Energy (DAE).
However, the transaction is so large that it requires shareholder approval under Kazakhstan’s Joint Stock Companies law. As a result, the company has called an Extraordinary General Meeting (EGM) at the initiative of its Board of Directors.
If approved, the agreement could tighten an already strained global uranium market.
A Deal That Could Reshape Uranium Supply
The proposed contract signed with the Directorate of Purchase & Stores (DPS) under India’s DAE, covers the long-term sale of natural uranium concentrates (U₃O₈) for physical delivery to India.
The value of the transaction equals or exceeds 50% of Kazatomprom’s total book asset value. Under Kazakh law, such a major transaction must go before shareholders for approval.
While pricing, volumes, and delivery schedules remain confidential due to commercial sensitivity, the scale alone signals its strategic weight.
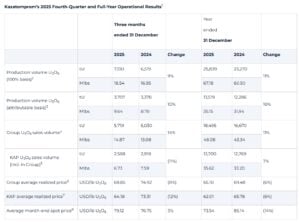
Kazatomprom’s Q4 2025 Fourth-Quarter Uranium Output
Kazatomprom currently accounts for about 20% of global uranium production. In 2025, it produced 25,839 tonnes of uranium (around 67.2 million pounds U₃O₈) on a 100% basis. That marked a 10–11% increase from 2024, driven largely by ramp-up at JV Budenovskoye.
- Meanwhile, spot transactions increased sharply. Spot volumes rose 50% year-over-year to 55.3 million pounds U₃O₈ (around 21,270 tonnes), with an average price of $72.75 per pound.
- Group sales volumes reached 5,719 tonnes (14.87 million pounds U₃O₈), up 14% from the previous year.
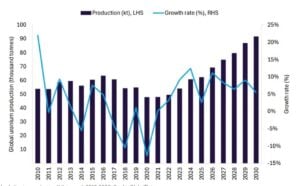
At the same time, global uranium mine production for 2025 was projected at 62.2 kilotonnes (ktU), according to industry estimates. Reactor demand stands higher at 68.9 ktU. This gap highlights a persistent supply deficit. Therefore, removing a sizeable share of Kazakh output under long-term contracts with India could tighten spot availability even further.
Fueling India’s Nuclear Ambitions: Why Uranium Imports Matter
India’s nuclear expansion explains the urgency behind this deal.
The country’s domestic uranium production currently meets only about 36% of its needs. Between 2025 and 2033, imports were projected to reach roughly 9,000 tonnes of uranium (tU) to support new reactor capacity.
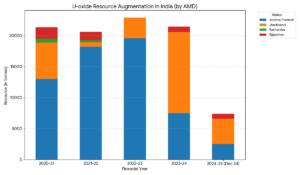
India holds recoverable reserves estimated at 252,500 tU below $260/kgU. In addition, the Atomic Minerals Directorate for Exploration and Research (AMD), a unit of the Department of Atomic Energy, has identified 433,800 tonnes of in-situ U₃O₈ resources across 47 deposits in states including Andhra Pradesh, Jharkhand, Rajasthan, and Telangana.
Mining at Jaduguda began in 1967 under Uranium Corporation of India Limited (UCIL). Recently, AMD discovered 26,437 tonnes of additional in-situ uranium oxide resources at the Jaduguda North–Baglasai–Mechua deposit in Jharkhand. This discovery is expected to extend the mine’s life significantly.
Still, domestic output alone cannot support India’s long-term reactor fleet expansion. Hence, securing a stable overseas supply has become a strategic priority.
The DPS, which handles procurement and inventory for India’s nuclear industry, accepted Kazatomprom’s commercial offer within its validity period. That move now awaits shareholder approval in Kazakhstan.
Uranium Supply in a Shifting Geopolitical Landscape
The uranium market remains highly concentrated in 2025, and this proposed deal reflects a broader shift in global nuclear geopolitics.
- Looking ahead, Kazatomprom’s 2026 production guidance stands at 27,500–29,000 tonnes on a 100% basis, slightly below nominal capacity due to sulphuric acid supply constraints. Group sales are expected at 19,500–20,500 tonnes.
If the India contract absorbs a major portion of future output, the free market could feel the impact quickly, especially given the structural supply gap.
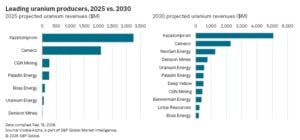
Reports say that by 2050, Kazakhstan and Canada are expected to dominate uranium exports. And in this market, uranium giants like Kazatomprom and Canada’s Cameco Corp. will dominate global revenue and production. Yet pricing trends have shown volatility. As demand for nuclear energy grows, countries are likely to form tighter supply alliances to secure fuel.
Balancing Strategy and Market Risk
At present, we can perceive that political tensions and energy security concerns are reshaping trade routes in oil and gas. And uranium may follow a similar path. Significantly, the IAEA has repeatedly noted that primary mining will remain the main source of uranium supply. Secondary sources, such as stockpiles and recycled materials, can only play a limited role.
Therefore, policymakers must rethink production and export strategies. Uranium-rich nations may reassess how much supply they allocate to long-term bilateral deals versus the open market.
For importing nations like India, long-term contracts provide stability. They reduce exposure to spot price volatility. They also strengthen diplomatic and economic ties. However, for the broader market, such agreements may reduce liquidity and amplify price swings during supply shocks.
The post Kazatomprom Deepens Strategic Ties with India in Major Long-Term Uranium Supply Deal appeared first on Carbon Credits.

Nature-based carbon investments deserve consideration when they address a specific business dependency and produce outcomes you can measure. Imagine Moonbucks, a global coffee roaster planning next season’s espresso blend. It is considering natural Grade 4 coffee from Jimma, in southwestern Oromia, Ethiopia. Its sourcing decisions affect the roasting schedule and the cash tied up in coffee purchases. Moonbucks needs to understand which measures could protect that supply, what they would cost and how it would judge the results.
1. Define the sourcing problem before choosing a project
Moonbucks needs a dependable component for its espresso blend. Its procurement team wants continuity of volume and an agreed cup profile. Replacing a shipment at short notice could require new sample approval and changes to the blend, and given the schedules for cultivation, processing, and freight delivery, is practically impossible. Moonbucks needs to get this right, and its initial concern is inconsistent deliveries. It commissions an assessment of the supplying farms and post-harvest chain. The questions cover land condition, harvest availability and whether drying or storage problems are affecting saleable lots.
This distinction changes the investment brief. A tree-planting proposal cannot be assumed to fix drying problems. Better storage cannot restore eroded land. The team must establish which problem exists before selecting the response.
CCC’s guide to finding nature-based solutions in your supply chain explains where to look. Here, the next task is to turn a broad concern into a testable proposal.
2. Develop nature-based carbon investments around the actual supply chain
The assessment would trace Moonbucks’ purchases back through the exporter and supplying producer groups. Which farms supply the contracted lots? Who controls land-management decisions? How long does the buyer expect to maintain the purchasing relationship?
Furthermore, Jimma natural Grade 4 cannot be treated as interchangeable with every Ethiopian coffee. Moonbucks would need to test any substitute against its own blend and quality requirements.
Suppose Moonbucks’ assessment identifies an opportunity to maintain shade trees and restore vegetation along exposed streambanks. The IPCC describes agroforestry as a way to store carbon in vegetation and soil, with potential benefits for erosion control and water quality.1 Moonbucks would need local advice on species, growing conditions and maintenance before deciding how these measures fit its sourcing plan.
The proposal now has a defined sourcing connection and a candidate intervention. The next steps are to test its effect on production, assess carbon eligibility and build the financial case.
3. Compare the proposal with other ways to protect supply
WBCSD’s Nature-based Solutions Blueprint recommends comparing nature-based options with other responses across their benefits and costs.2 For Moonbucks, that means evaluating the landscape proposal alongside drying improvements, storage controls and alternative sourcing arrangements.
The product’s natural-process designation matters. Moonbucks should examine the drying and dry-milling chain alongside land conditions. Its team would check storage practices, contamination risks and incoming-lot quality to see whether problems arise before or after the coffee leaves the farms.
The revised proposal might combine land stewardship with separate post-harvest controls. Each component needs its own purpose and budget. A sustainability label should not obscure which activity is expected to solve which problem.
The project develops as the evidence improves. Its scope should follow the diagnosis rather than preserve the first idea unchanged.
4. Establish what the carbon outcome could count toward
Moonbucks’ sustainability team now tests the proposed carbon case separately from the sourcing case. Is the objective a measurable change in Moonbucks’ value-chain emissions, verified credits for separate voluntary use, or distinct outcomes under carefully defined arrangements?
Scope 3 covers value-chain emissions. A purchasing relationship alone does not prove that a farm intervention can be included in Moonbucks’ inventory. The team needs an applicable accounting method, defensible boundaries and evidence supporting attribution.
SBTi’s FLAG Guidance (forest, land and agriculture), version 1.2, says purchased credits used as offsets cannot meet near-term FLAG or energy and industry targets. Eligible land-based removals are subject to accounting requirements.3 Moonbucks needs to test its proposal against those rules before including an outcome in its targets.
For Moonbucks’ Jimma proposal, maintaining existing trees and establishing new vegetation could involve different carbon questions. Specialists must examine the baseline and additionality, meaning what changes because the project proceeds. They must also assess measurement and the risk that stored carbon is lost. CCC’s MRV and additionality article introduces those tests.
Until that work is complete, Moonbucks should not budget an assumed Scope 3 reduction or credit-sale receipt. Direct emissions reductions remain the priority.
5. Build a financial case that survives weaker assumptions
Moonbucks’ finance team would now build a multi-year budget. UNEP’s State of Finance for Nature 2023 compares current finance with the investment needed to meet climate, biodiversity and land-restoration goals.4 The company would cost its proposed activities, farmer participation and ongoing monitoring. Verification, where required, is a separate expense. Maintenance and responsibility for replacing failed plantings must remain visible after the initial establishment budget ends.
Operational benefits need equally careful treatment. If fewer rejected lots reduce emergency purchasing, count that saving once. Do not add “supply resilience” as another financial benefit when it represents the same avoided cost.
Moonbucks should compare a base case with slower benefits, higher implementation costs and no carbon revenue. It should also distinguish production outcomes from quality and shipment outcomes. A single good harvest would not prove that the landscape intervention caused better delivery performance.
A project can remain worth funding even when its carbon case needs more work. That decision must rest on the operational evidence and the company’s objectives, without unsupported environmental claims.
6. Fund a pilot with a clear expansion decision
Moonbucks’ first approval would fund a bounded pilot, rather than commit the entire sourcing program. Before spending, Moonbucks would agree on participating farms, responsibilities and the evidence needed at review.
Its scorecard could track farmer participation, implementation costs and plant survival, alongside accepted coffee volumes and lot-quality results. Carbon measurements would follow the selected method. Farm-level traceability must connect the intervention to the actual sourcing relationship.
Suppose Moonbucks’ review later finds that storage changes explain most quality improvements, while the land measures need longer observation. Those findings would shape the next decision: expand the proven component, adjust the landscape work or pause further spending. They would not justify crediting all improvements to tree planting.
This gives nature-based carbon investments a practical place in a multi-year strategy. Funding increases as the evidence supports it, and the project can change direction before a larger commitment.
Discuss a sourcing opportunity with CCC
Carbon Credit Capital’s nature-based supply-chain investment service uses its Dual-Value Model to examine supply-chain economics alongside potential sustainability outcomes.
Schedule a consultation to discuss your sourcing exposure and the questions to resolve before allocating capital.
Sources
- Intergovernmental Panel on Climate Change (IPCC), Climate Change 2022: Mitigation of Climate Change, Chapter 7, Agriculture, Forestry and Other Land Uses, section 7.4.3.3 (Agroforestry).
- World Business Council for Sustainable Development (WBCSD), Nature-based Solutions Blueprint, 5 June 2024.
- Science Based Targets initiative (SBTi), Forest, Land and Agriculture Science-Based Target-Setting Guidance, version 1.2, March 2026, section 3.1.4, pp. 37–38.
- United Nations Environment Programme (UNEP), State of Finance for Nature 2023, 2023.
A plastic credit funds the collection of plastic waste in places where no formal system exists to collect it. Each credit represents a measured, independently audited quantity of plastic taken out of the environment or returned to use, tracked on a public registry.

EU carbon credit claims changed on 27 September 2026, the day the Directive (EU) 2024/825 began to apply across the European Union. The change is narrow. It changes how a company can talk about the credits it buys. A product can no longer be called neutral on the strength of compensation alone; however, every specific, evidenced statement about what a company measured, reduced, and funded stays fully available.




-
Climate Change1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Greenhouse Gases2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
Greenhouse Gases1 year ago
Guest post: Why China is still building new coal – and when it might stop
-

 Climate Change2 years ago
嘉宾来稿:满足中国增长的用电需求 光伏加储能“比新建煤电更实惠”
-
 Renewable Energy1 year ago
Sending Progressive Philanthropist George Soros to Prison?
-
Greenhouse Gases1 year ago
嘉宾来稿:探究火山喷发如何影响气候预测
-

 Climate Change2 years ago
Analysis: China’s CO2 falls 1% in Q2 2024 in first quarterly drop since Covid-19