

Only half of China’s provinces have finalised new rules for pricing wind and solar power, according to Carbon Brief analysis.
Local governments are required to have published final plans to reform the way wind and solar power is priced in their jurisdiction before the end of this year.
This follows the release of a central government directive in February – known as “Document 136” (136号文) – that calls for developing a more “market-based” approach to pricing newly installed renewable projects.
The new rules will replace the previous pricing mechanism, which gave wind and solar generators guaranteed sales at a fixed price tied to the benchmark electricity price from coal.
The shift towards market-based pricing for wind and solar is seen as a key uncertainty for the sector, with implications for China’s wider energy and emissions targets.
Carbon Brief analysis finds that, as of 15 October 2025, only 18 provinces had issued finalised “Document 136” plans.
Another 10 have published draft plans, while Jiangsu, Tianjin and Tibet have yet to indicate what their strategies will be.
Central direction, local rules
In February this year, China’s central government issued a notice on “deepening market-based reform of feed-in tariffs for new energy”, also known as “Document 136”.
The document calls on local governments to develop plans for new pricing mechanisms for wind and solar power, applicable to projects completed on or after 1 June 2025.
Local governments are expected to develop “sustainable new-energy pricing mechanisms” (新能源可持续发展价格结算机制), in which they only offer a fixed price to a set amount of new wind and solar capacity each year.
The amount offered a fixed price is to be linked to each province’s annual clean-energy installation quotas. Moreover, the fixed price is to be determined at auction, through a mechanism resembling the UK’s contract for difference (CfD).
Any additional wind and solar projects, which are unable to secure contracts via the provincial auction mechanism, would need to find buyers for their electricity on the open market. This could be done through a “power purchase agreement” with a grid operator or a large industrial user, for example, or by selling their power in spot markets.
The move is part of wider efforts to shift China’s giant electricity system towards more market-based operation, rather than running on rules set by the government, including prices for coal-fired power plants determined by bureaucrats.
The shift towards market-based pricing for renewables has been attributed to both the falling costs of building new solar and windfarms, as well as to the grid challenges created by record renewable capacity additions.
At the time of the policy’s release earlier this year, analysts expected the rules to have a chilling effect on China’s wind and solar buildout in the short term, as developers adjust to the new rules and to lower – and more uncertain – prices set at auction.
The notice led to a rush of new capacity additions ahead of the June cut-off, with an estimated 100 solar cells being installed every second in the month of May.
However, a subsequent policy requiring cement, polysilicon and iron and steel manufacturers, as well as certain types of data centres, to use renewable power to fulfil a certain proportion of their overall consumption has been seen as a “backstop” that may buoy industry demand for new wind and solar capacity.
Furthermore, analysts believe that “Document 136” may strengthen China’s clean-energy industries in the long term, by forcing companies to become more innovative and competitive.
Below, Carbon Brief lists which provinces have published finalised “Document 136” pricing plans (green), which provinces have published a form of draft plan (yellow) and which provinces have yet not published their plans at all (white).
By default, provinces are listed in order of the size of their energy-related carbon dioxide (CO2) emissions, based on a dataset for 2022 from the thinktank Institute of Global Decarbonization Progress.
New territory
So far, Carbon Brief finds, only just over half of provinces have issued finalised plans. Collectively, these provinces account for 61% of China’s energy-related emissions.
Another 10, representing 31% of emissions, have published draft plans, while Jiangsu, Tianjin and Tibet – the final 8% of CO2 – have yet to publish anything.
A few provinces published finalised rules in early June, including renewable-power heavyweights Shandong and Inner Mongolia.
(Inner Mongolia’s power grid is split into two zones – “Inner Mongolia East” and “Inner Mongolia West” – which are administered separately.)
In a nationwide conference call at the end of August, National Energy Administration officials urged provinces to “promptly promote” concrete plans.
Eleven provinces have published finalised rules since then, including major polluters Heilongjiang, Hebei and Guangdong, with a further eight publishing draft rules, according to Carbon Brief calculations.
The delay in provinces completing their plans can be attributed to the fact that local policymakers are trying to establish a completely new system of pricing power from scratch, says David Fishman, principal at energy consultancy the Lantau Group.
He tells Carbon Brief that, for some of the provinces that have issued finalised rules, “fairly meaningful differences” can be found between the final version and earlier drafts – indicating a high level of debate on the best path forward.
Shandong province was the first to issue draft rules, setting the tone for other local governments’ documents.
The eastern province is seen as a leader both in renewable energy additions and in undertaking power-market reforms. It is also the largest source of energy-related emissions in China.
Its plan saw notable policy innovations, such as setting an auction subscription threshold of 125% to encourage competition, by ensuring that not all bidders will be successful.
In September, it also became the first province in China to hold auctions for solar and wind power under the new rules, with the winning bidders securing prices of 0.319 yuan per kilowatt-hour (yuan/kWh) for wind and 0.225 yuan/kWh for solar.
These prices are equivalent to £33.8 per megawatt hour (MWh), or $44.8/MWh, for wind and £23.8/MWh, or $31.6/MWh, for solar.
While the wind prices are seen as high enough to be relatively acceptable to project developers, the price for solar is below the level thought to be needed to finance such developments. As such, it could “discourage” further solar investment in the province, Reuters reports.
Shortly afterwards, the southwestern province of Yunnan also held its first renewables auction, setting a price of 0.33 yuan/kWh for both wind and solar projects.
Effect on future additions
Analysts disagree about what impact the “Document 136” policy will have on the pace of China’s clean-energy additions.
The country installed a record 360 gigawatts (GW) of wind and solar in 2024, followed by an even higher 212GW in the first half of 2025 for solar alone, as developers rushed to complete ahead of the June deadline.
In September, Chinese president Xi Jinping announced a target of 3,600GW of wind and solar capacity by 2035 as part of the country’s new “nationally determined contribution” (NDC) to the Paris Agreement.
While hugely ambitious in the context of current global wind and solar capacity, which stood at 1,400GW at the end of 2024, this new goal is equivalent to just 200GW of new wind and solar per year. This would be a significant slowdown compared with China’s recent pace of expansion.
Dr Muyi Yang, senior energy analyst for Asia at thinktank Ember, tells Carbon Brief that he does not see the pricing reforms as a “signal of a structural slowdown in clean capacity [additions]”. He adds:
“Adding panels and turbines is the easy part…China is rewiring the world’s largest power sector, with multiple layers of interests and legacy assets to manage. In navigating this complexity, pledge targets act as a floor, providing certainty to clean-energy developers and clean-tech manufacturers. The NDC goal reflects what decision-makers are confident China can deliver given these constraints.”
But Fishman, writing on LinkedIn, notes that the pricing reforms could make it “challenging” for China to hit Xi’s new 2035 target.
Renewables developers are not incentivised to sustain previous years’ high installation figures under the local rules that have been rolled out so far, he notes, adding: “We will be lucky to see 200GW in a single year again for a long time.”
In its Renewables 2025 report, published in October 2025, the International Energy Agency (IEA) shaved 5% off its outlook for wind and solar growth in China out to 2030, a reduction of 129GW. It attributes this downgrade to the country’s renewable pricing reforms “impacting project economics and lowering growth expectations”.
Nevertheless, it adds that China is still projected to add “nearly 2,660GW” of new renewable capacity between 2025 and 2030, meaning that it would reach its 2035 wind and solar target “five years ahead of schedule”.
Bolstering storage demand
Beyond wind and solar capacity, “Document 136” also signalled potentially disruptive changes for China’s energy storage sector. It removed requirements at the central level that wind and solar projects must include a storage component.
This led to concerns at the time that demand for battery energy storage facilities could drop substantially.
In practice, however, different provinces have designed their own approaches to commissioning energy storage under their “Document 136” plans.
Some, such as Shandong, have eliminated energy storage requirements, while others, such as Yunnan and Guizhou have kept them.
A recent analysis by consulting firm Infolink argues that a significant drop in demand for energy storage projects is, therefore, “unlikely”, due to expected ongoing demand for “renewable integration and grid flexibility”.
Pumped storage and gas-fired power capacity make up only 7% of China’s electricity system – compared to 34% in Spain and 50% in the US, according to analysis by NGO Greenpeace. As such, it says there will likely be ongoing demand for battery storage as a major contributor to power flexibility in China.
The Chinese government set a target in a recent action plan for 180GW of new-energy storage by 2027, up from just over 100GW at the end of June 2025.
The target “directly addresses the issue of low short-term economic viability” of the energy storage sector caused by “Document 136”, economic news outlet Jiemian reports, although it notes that “uncertainties” still remain.
However, unnamed industry participants tell financial news outlet Yicai that the pricing reform has removed the storage sector’s “fig leaf”, meaning it is likely to result in the number of energy storage companies falling from the current figure of more than 200,000.
Yang tells Carbon Brief that the reforms will likely lead to “more storage-paired and hybrid projects” that better meet province-specific needs and “prioritise reliability and integration over headline [megawatts]”.

The post Analysis: Only half of Chinese provinces finalise key ‘Document 136’ renewable rules appeared first on Carbon Brief.
Analysis: Only half of Chinese provinces finalise key ‘Document 136’ renewable rules

Drought and heatwaves occurring together – known as “compound” events – have “surged” across the world since the early 2000s, a new study shows.
Compound drought and heat events (CDHEs) can have devastating effects, creating the ideal conditions for intense wildfires, such as Australia’s “Black Summer” of 2019-20 where bushfires burned 24m hectares and killed 33 people.
The research, published in Science Advances, finds that the increase in CDHEs is predominantly being driven by events that start with a heatwave.
The global area affected by such “heatwave-led” compound events has more than doubled between 1980-2001 and 2002-23, the study says.
The rapid increase in these events over the last 23 years cannot be explained solely by global warming, the authors note.
Since the late 1990s, feedbacks between the land and the atmosphere have become stronger, making heatwaves more likely to trigger drought conditions, they explain.
One of the study authors tells Carbon Brief that societies must pay greater attention to compound events, which can “cause severe impacts on ecosystems, agriculture and society”.
Compound events
CDHEs are extreme weather events where drought and heatwave conditions occur simultaneously – or shortly after each other – in the same region.
These events are often triggered by large-scale weather patterns, such as “blocking” highs, which can produce “prolonged” hot and dry conditions, according to the study.
Prof Sang-Wook Yeh is one of the study authors and a professor at the Ewha Womans University in South Korea. He tells Carbon Brief:
“When heatwaves and droughts occur together, the two hazards reinforce each other through land-atmosphere interactions. This amplifies surface heating and soil moisture deficits, making compound events more intense and damaging than single hazards.”
CDHEs can begin with either a heatwave or a drought.
The sequence of these extremes is important, the study says, as they have different drivers and impacts.
For example, in a CDHE where the heatwave was the precursor, increased direct sunshine causes more moisture loss from soils and plants, leading to a drought.
Conversely, in an event where the drought was the precursor, the lack of soil moisture means that less of the sun’s energy goes into evaporation and more goes into warming the Earth’s surface. This produces favourable conditions for heatwaves.
The study shows that the majority of CDHEs globally start out as a drought.
In recent years, there has been increasing focus on these events due to the devastating impact they have on agriculture, ecosystems and public health.
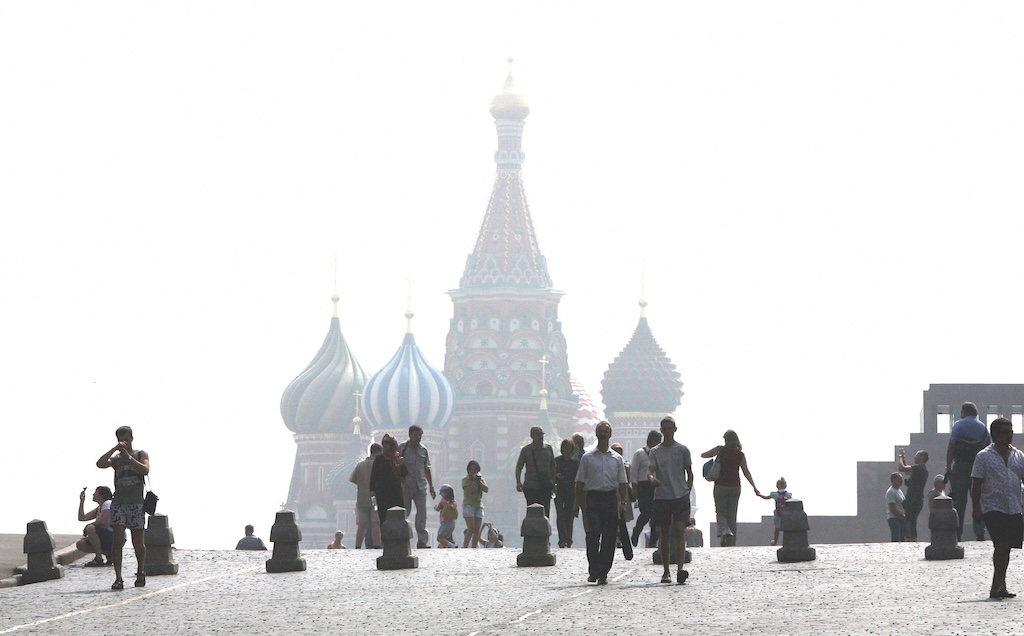
In Russia in the summer of 2010, a compound drought-heatwave event – and the associated wildfires – caused the death of nearly 55,000 people, the study notes.
The record-breaking Pacific north-west “heat dome” in 2021 triggered extreme drought conditions that caused “significant declines” in wheat yields, as well as in barley, canola and fruit production in British Columbia and Alberta, Canada, says the study.
Increasing events
To assess how CDHEs are changing, the researchers use daily reanalysis data to identify droughts and heatwaves events. (Reanalysis data combines past observations with climate models to create a historical climate record.) Then, using an algorithm, they analyse how these events overlap in both time and space.
The study covers the period from 1980 to 2023 and the world’s land surface, excluding polar regions where CDHEs are rare.
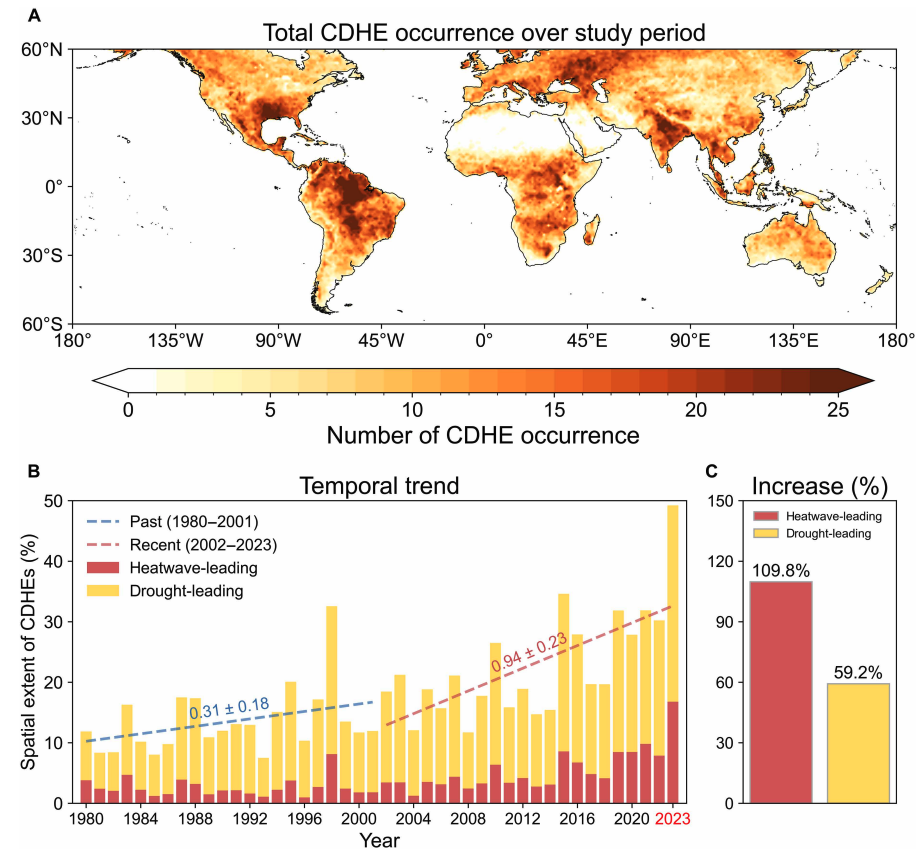
The research finds that the area of land affected by CDHEs has “increased substantially” since the early 2000s.
Heatwave-led events have been the main contributor to this increase, the study says, with their spatial extent rising 110% between 1980-2001 and 2002-23, compared to a 59% increase for drought-led events.
The map below shows the global distribution of CDHEs over 1980-2023. The charts show the percentage of the land surface affected by a heatwave-led CDHE (red) or a drought-led CDHE (yellow) in a given year (left) and relative increase in each CDHE type (right).
The study finds that CDHEs have occurred most frequently in northern South America, the southern US, eastern Europe, central Africa and south Asia.
Threshold passed
The authors explain that the increase in heatwave-led CDHEs is related to rising global temperatures, but that this does not tell the whole story.
In the earlier 22-year period of 1980-2001, the study finds that the spatial extent of heatwave-led CDHEs rises by 1.6% per 1C of global temperature rise. For the more-recent period of 2022-23, this increases “nearly eightfold” to 13.1%.
The change suggests that the rapid increase in the heatwave-led CDHEs occurred after the global average temperature “surpasse[d] a certain temperature threshold”, the paper says.
This threshold is an absolute global average temperature of 14.3C, the authors estimate (based on an 11-year average), which the world passed around the year 2000.
Investigating the recent surge in heatwave-leading CDHEs further, the researchers find a “regime shift” in land-atmosphere dynamics “toward a persistently intensified state after the late 1990s”.
In other words, the way that drier soils drive higher surface temperatures, and vice versa, is becoming stronger, resulting in more heatwave-led compound events.
Daily data
The research has some advantages over other previous studies, Yeh says. For instance, the new work uses daily estimations of CDHEs, compared to monthly data used in past research. This is “important for capturing the detailed occurrence” of these events, says Yeh.
He adds that another advantage of their study is that it distinguishes the sequence of droughts and heatwaves, which allows them to “better understand the differences” in the characteristics of CDHEs.
Dr Meryem Tanarhte is a climate scientist at the University Hassan II in Morocco, and Dr Ruth Cerezo Mota is a climatologist and a researcher at the National Autonomous University of Mexico. Both scientists, who were not involved in the study, agree that the daily estimations give a clearer picture of how CDHEs are changing.
Cerezo-Mota adds that another major contribution of the study is its global focus. She tells Carbon Brief that in some regions, such as Mexico and Africa, there is a lack of studies on CDHEs:
“Not because the events do not occur, but perhaps because [these regions] do not have all the data or the expertise to do so.”
However, she notes that the reanalysis data used by the study does have limitations with how it represents rainfall in some parts of the world.
Compound impacts
The study notes that if CDHEs continue to intensify – particularly events where heatwaves are the precursors – they could drive declining crop productivity, increased wildfire frequency and severe public health crises.
These impacts could be “much more rapid and severe as global warming continues”, Yeh tells Carbon Brief.
Tanarhte notes that these events can be forecasted up to 10 days ahead in many regions. Furthermore, she says, the strongest impacts can be prevented “through preparedness and adaptation”, including through “water management for agriculture, heatwave mitigation measures and wildfire mitigation”.
The study recommends reassessing current risk management strategies for these compound events. It also suggests incorporating the sequences of drought and heatwaves into compound event analysis frameworks “to enhance climate risk management”.
Cerezo-Mota says that it is clear that the world needs to be prepared for the increased occurrence of these events. She tells Carbon Brief:
“These [risk assessments and strategies] need to be carried out at the local level to understand the complexities of each region.”
The post Heatwaves driving recent ‘surge’ in compound drought and heat extremes appeared first on Carbon Brief.
Heatwaves driving recent ‘surge’ in compound drought and heat extremes
Greenhouse Gases
DeBriefed 6 March 2026: Iran energy crisis | China climate plan | Bristol’s ‘pioneering’ wind turbine
Welcome to Carbon Brief’s DeBriefed.
An essential guide to the week’s key developments relating to climate change.
This week
Energy crisis
ENERGY SPIKE: US-Israeli attacks on Iran and subsequent counterattacks across the Middle East have sent energy prices “soaring”, according to Reuters. The newswire reported that the region “accounts for just under a third of global oil production and almost a fifth of gas”. The Guardian noted that shipping traffic through the strait of Hormuz, which normally ferries 20% of the world’s oil, “all but ground to a halt”. The Financial Times reported that attacks by Iran on Middle East energy facilities – notably in Qatar – triggered the “biggest rise in gas prices since Russia’s full-scale invasion of Ukraine”.
‘RISK’ AND ‘BENEFITS’: Bloomberg reported on increases in diesel prices in Europe and the US, speculating that rising fuel costs could be “a risk for president Donald Trump”. US gas producers are “poised to benefit from the big disruption in global supply”, according to CNBC. Indian government sources told the Economic Times that Russia is prepared to “fulfil India’s energy demands”. China Daily quoted experts who said “China’s energy security remains fundamentally unshaken”, thanks to “emergency stockpiles and a wide array of import channels”.
‘ESSENTIAL’ RENEWABLES: Energy analysts said governments should cut their fossil-fuel reliance by investing in renewables, “rather than just seeking non-Gulf oil and gas suppliers”, reported Climate Home News. This message was echoed by UK business secretary Peter Kyle, who said “doubling down on renewables” was “essential” amid “regional instability”, according to the Daily Telegraph.
China’s climate plan
PEAK COAL?: China has set out its next “five-year plan” at the annual “two sessions” meeting of the National People’s Congress, including its climate strategy out to 2030, according to the Hong Kong-based South China Morning Post. The plan called for China to cut its carbon emissions per unit of gross domestic product (GDP) by 17% from 2026 to 2030, which “may allow for continued increase in emissions given the rate of GDP growth”, reported Reuters. The newswire added that the plan also had targets to reach peak coal in the next five years and replace 30m tonnes per year of coal with renewables.
ACTIVE YET PRUDENT: Bloomberg described the new plan as “cautious”, stating that it “frustrat[es] hopes for tighter policy that would drive the nation to peak carbon emissions well before president Xi Jinping’s 2030 deadline”. Carbon Brief has just published an in-depth analysis of the plan. China Daily reported that the strategy “highlights measures to promote the climate targets of peaking carbon dioxide emissions before 2030”, which China said it would work towards “actively yet prudently”.
Around the world
- EU RULES: The European Commission has proposed new “made in Europe” rules to support domestic low-carbon industries, “against fierce competition from China”, reported Agence France-Presse. Carbon Brief examined what it means for climate efforts.
- RECORD HEAT: The US National Oceanic and Atmospheric Administration has said there is a 50-60% chance that the El Niño weather pattern could return this year, amplifying the effect of global warming and potentially driving temperatures to “record highs”, according to Euronews.
- FLAGSHIP FUND: The African Development Bank’s “flagship clean energy fund” plans to more than double its financing to $2.5bn for African renewables over the next two years, reported the Associated Press.
- NO WITHDRAWAL: Vanuatu has defied US efforts to force the Pacific-island nation to drop a UN draft resolution calling on the world to implement a landmark International Court of Justice (ICJ) ruling on climate, according to the Guardian.