

China accounted for 95% of the world’s new coal power construction activity in 2023, according to the latest annual report from Global Energy Monitor (GEM).
Construction began on 70 gigawatts (GW) of new capacity in China, up four-fold since 2019, says GEM’s annual report on the global coal power industry.
This compares with less than 4GW of new coal power construction starting in the rest of the world – the lowest since 2014.
Outside China, only 32 countries have new coal projects at pre-construction phases of development and just seven have plants under construction.
While global coal power capacity – both overall and outside China – grew in 2023, GEM says this is likely to be a “blip” that will be offset by accelerating coal retirements in the next few years in the US and Europe.
Other key findings of the report include that construction of coal-fired power plants globally – excluding China – declined for the second year in a row. However, coal power plant retirements were also at the lowest level since 2011.
‘Pivotal juncture’ for China
In China, 47.4GW of coal power capacity came online in 2023, GEM says. This increase accounted for two-thirds of the global rise in operating coal power capacity, which climbed 2% to 2,130GW.
China’s 70.2GW of new construction getting underway in 2023 represents 19-times more than the rest of the world’s 3.7GW. As the figure below highlights, the country’s trajectory (red line) is diverging significantly from the rest of the world (orange line).
The level of new construction starting in China is nearly quadruple what it was in 2019, when the country hit a nine-year annual low of entirely new coal power stations starting.

This is the fourth year in a row that the amount of new coal construction starting has increased in China. This is out of line with President Xi Jinping’s 2021 pledge to “strictly control” new coal power capacity, GEM states.
In early 2022, China’s National Energy Administration’s 14th five‐year plan for a “modern energy system” stated that 30GW of coal power would be retired by 2025.
However, when counting larger coal units with capacity of at least 30 megawatts, less than 9GW of power plants have been shut down in the last three years, and few others have plans to retire, GEM notes.
If China is to meet this 30GW retirement target, it “needs to take immediate action”, GEM adds.
In a statement, Qi Qin, China analyst at the Centre for Research on Energy and Clean Air, said:
“The recent surge in coal power development in China starkly contrasts with the global trend, putting China’s 2025 climate targets at risk. At this pivotal juncture, it is crucial for China to impose stricter controls on coal power projects and expedite the transition towards renewable energy to realign with its climate commitments.”
Collectively, China, India, Bangladesh, Zimbabwe, Indonesia, Kazakhstan, Laos, Turkey, Russia, Pakistan and Vietnam account for 95% of global pre-construction capacity, according to the GEM report.
The 5% remaining is distributed among 21 countries, the tracker finds. Of these, 11 have one project and are on the brink of achieving the “no new coal” milestone, it adds.
The tracker identifies 20.9GW of entirely new coal power proposals outside of China in 2023. This was led by India, which saw 11.4GW of new coal capacity proposed, more than any year since 2016. This was in part due to the revival of several stalled projects in the country, GEM explains.
Kazakhstan also saw 4.6GW of new proposals and Indonesia saw 2.5GW. Some 4.1GW of previously shelved or cancelled capacity is now considered “proposed” again.
Another handful of countries – Russia, the Philippines, Botswana and Nigeria – also saw revived proposals and construction restarting in 2023.
Retirements slow
Globally, a total of 69.5GW of coal power came online in 2023, while 21.1GW was retired, GEM finds. This led to the highest net increase in global operating coal capacity since 2016, with a 48.4GW jump.
New capacity also came online in Indonesia (5.9GW), India (5.5GW), Vietnam (2.6GW), Japan (2.5GW), Bangladesh (1.9GW), Pakistan (1.7GW), South Korea (1GW), Greece (0.7GW) and Zimbabwe (0.3GW).
In total during 2023, the tracker found 22.1GW came online and 17.4GW was retired outside of China. This resulted in a 4.7GW net increase in the world’s coal fleet operating outside China. Globally, coal power capacity reached 2,130GW in 2023, up from 2% a year earlier.
The US contributed nearly half of coal power retirements, GEM says, with 9.7GW shuttering in 2023. However, this is a drop in retirements from 14.7GW in 2022, and a peak of 21.7GW in 2015.
Elsewhere, the EU and UK represented nearly a quarter of retirements, with 3.1GW closing in the UK, 0.6GW in Italy and 0.5GW in Poland. There is now just one operating coal-fired power plant in the UK, with the Ratcliffe-on-Soar set to close in September 2024.
Overall, global coal power plant retirements were at their lowest level since 2011, as the figure below shows.

Outside of China, the number of coal-fired power plants starting construction declined for the second consecutive year, hitting its lowest level since data collection began in 2015, GEM notes.
Less than 4GW of new projects began construction outside of China in 2023, far below the average of 16GW between 2015 and 2022. Just seven countries started construction, with one plant each in India, Laos, Nigeria, Pakistan and Russia, as well as three plants in Indonesia.
Construction has not started on any coal plants in Latin America since 2016, and none has started in Organisation for Economic Co-operation and Development (OECD), European or Middle Eastern countries since 2019, GEM says.
Nigeria’s Ugboba power station, located at the mine-mouth of the Idowu Falola Coal Mines in the Aniocha North local government area of Delta state, is the first known construction of a coal power plant in Africa since 2019, the report says.
The G7 – which accounts for 15% (310GW) of the world’s operating coal capacity, down from 32% (443GW) in 2015 – has no new coal capacity under construction. However, there is still one proposed coal power plant in Japan and two in the US.
Both of the proposed sites in the US, the 0.4GW CONSOL Project in Pennsylvania and the newly announced 0.4GW Susitna power station in Alaska, are expected to use carbon capture and storage technologies (CCS).
GEM says that these technologies are “effectively uncertain and expensive distractions from the urgent need to phase out coal”.
The G20 is home to 92% of the world’s operating coal capacity (1,968GW) and 88% of pre-construction coal capacity (336GW). Brazil, the current G20 chair, saw its pipeline of pre-construction capacity fall in 2023, but still has two prospective projects remaining – the last pre-construction coal power plants in Latin America.
No new coal nations
Overall, coal capacity reached an all time high in 2023, GEM’s tracker says.
Operating coal capacity outside China grew for the first time since 2019, as less coal capacity retired than in any other single year in more than a decade, as the figure below shows.

The world’s operating coal power capacity is up 11% since 2015, when governments agreed to keep the global average temperature to well below 2C above pre-industrial levels and aim to limit warming to 1.5C under the Paris Agreement.
Outside of China, there are still 113GW of coal power projects under construction. While this is only slightly up from the previous year’s level of 110GW, it still highlights that the coal sector is not in line with the International Energy Agency’s (IEA) 1.5C scenario, GEM says.
Across all IEA scenarios that meet international climate goals there is a rapid decline in global coal emissions.
Globally, pre-construction capacity rose 6% in 2023, “crystallising the importance of calls to stop proposing and breaking ground on new coal plants”, GEM’s report says.
Only 15% (317GW) of currently operating coal power capacity has a commitment to retire in line with Paris Agreement goals, it adds.
Phasing out unabated coal generation by 2040 – in line with the IEA’s 1.5C pathway – would require an average of 126GW of retirements every year for the next 17 years, GEM notes. This is the equivalent of two coal power plants per week.
Even steeper cuts would be needed to account for the 578GW of coal power plants also under construction and in pre-construction phases of development, GEM says.
There were 12 new countries that committed to developing no new coal generation in 2023, by joining the Powering Past Coal Alliance. This brings the total number of countries up to 101 that have either formally declared they will have no new coal or have abandoned any coal plans they have had over the last decade, GEM notes.
Since 2015, there has been a 68% reduction in global pre-construction capacity, GEM found. New construction starts are now at their lowest level outside of China, since data collection began.
GEM’s report suggests that coal power projects that utilise CCS and those used to power industrial activities may be “a last frontier” for new coal proposals.
For example, Zimbabwe’s 1.9GW of new coal capacity proposed in 2023 is made up of two projects, the Prestige power station and the Gweru power station, designed to power smelters for extracting chromium from ore.
Zimbabwe is one of one six countries, beyond China and India, to have increased its total planned capacity over the past year, along with Kazakhstan, Kyrgyzstan, Russia, Zimbabwe, the US and the Philippines.
At COP28, 130 countries signalled their intent to phase out unabated coal power and stop investing in new unabated coal-fired power plants within this decade, by signing the Global Renewables and Energy Efficiency Pledge.
In addition, the final global stocktake agreement at COP28 reiterated the pledge from COP26 to phase down unabated coal power, but still does not define what “unabated” means. Additionally, wording from earlier drafts on ending permitting of new coal power was omitted in the final text.
“Coal power is at the edge of a precipice, facing political and civil opposition and increasingly uncompetitive economics,” GEM’s report states.
In a statement, Flora Champenois, coal programme director for GEM said:
“Coal’s fortunes this year are an anomaly, as all signs point to reversing course from this accelerated expansion. But countries that have coal plants to retire need to do so more quickly, and countries that have plans for new coal plants must make sure these are never built. Otherwise we can forget about meeting our goals in the Paris Agreement and reaping the benefits that a swift transition to clean energy will bring.”



The post China responsible for 95% of new coal power construction in 2023, report says appeared first on Carbon Brief.
China responsible for 95% of new coal power construction in 2023, report says

When oil and gas shipments stopped flowing through the Strait of Hormuz at the start of the Iran war, Southeast Asian nations were left reeling as the supply crunch laid bare their acute reliance on fossil fuel imports.
As prices soared, governments in the region scrambled to introduce emergency energy-saving measures – from a four-day working week to curbs on air conditioning. Thailand revived decommissioned coal plants while the Philippines, which imports nearly all of its oil, declared a “national energy emergency”.
But the crisis has also prompted renewed resolve to find a long-term solution to their vulnerability at a time when electricity demand is booming to power the region’s growing industry, cooling needs and the mushrooming of energy-hungry data centres.
At the heart of Southeast Asian nations’ response is a longstanding infrastructure project to connect the region’s power grids by 2045 and enable cross-border trading of clean electricity through a network of underground and subsea interconnectors.
-
Southeast Asia’s fragile grids threaten billions in clean energy investment
Renewables developers need reliable electricity infrastructure and stable policies to help the region meet climate goals and surging demand for power -
UN backs push to upgrade grids slowing clean power uptake in Africa and SE Asia
The Global Grids Accelerator will help turn national and regional plans to expand electricity infrastructure into viable projects on the ground -
China keeps Indonesia’s battery dream afloat but future less certain
Chinese capital and technology turned Indonesia into the world’s top nickel supplier, but its dependence on China and the rise of nickel-free batteries could upset its battery ecosystem plans
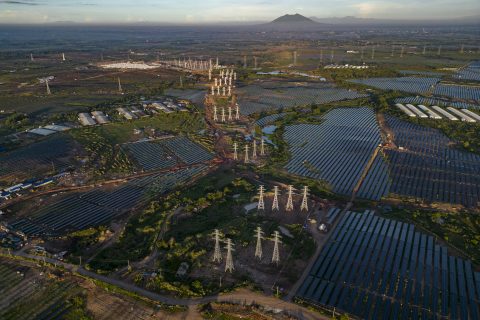
The plans will allow nations with high renewable energy generation potential to trade surplus power to their neighbours and major demand centres like Singapore, helping to integrate more renewables into the power mix and reduce reliance on fossil fuel imports.
“[It] will give us more energy security,” the Philippines’ energy secretary, Sharon Garin, told a press conference after a meeting of the Association of Southeast Asian Nations’ (ASEAN) energy ministers last week, when they discussed accelerating the delivery of the regional grid as part of measures to respond to the energy crisis.
“The Philippines is rich in solar power, Malaysia is rich in hydropower and Indonesia has geothermal: different countries have different resources. [The ASEAN Power Grid] will optimise the utilisation of renewables to the benefits of each member state,” said Garin.
But turning this decade-old political vision into a reality has been slow, held up by painstaking work to harmonise a patchwork of regulatory and legal frameworks and mobilise the private capital needed to build cross-border infrastructure.
More than $300 billion is needed to expand and modernise the region’s fragile grids to support the projected energy demand increase by 2050. This includes $27 billion required to deliver the cross-border interconnections by 2040, according to the International Energy Agency (IEA).
Every year of delay could cost the region billions of dollars in additional fuel costs and lock in new gas infrastructure for decades to come, according to analysis by global energy think-tank Ember.
The building block for energy security
With electrification high on the agenda of the COP31 climate talks in Türkiye next month, there is growing attention on the need to modernise and expand grid infrastructure to cope with growing electricity use and more renewables in the power mix.
Clean electrification and energy efficiency could deliver about a third of cumulative carbon emission reductions between 2026 and 2050, according to the International Renewable Energy Agency’s World Energy Outlook. But delivering that would require doubling annual global grid investment to $1 trillion between now and 2035.
Last month, the UN launched an initiative to accelerate investment into expanding and modernising grids in Southeast Asia and Africa.
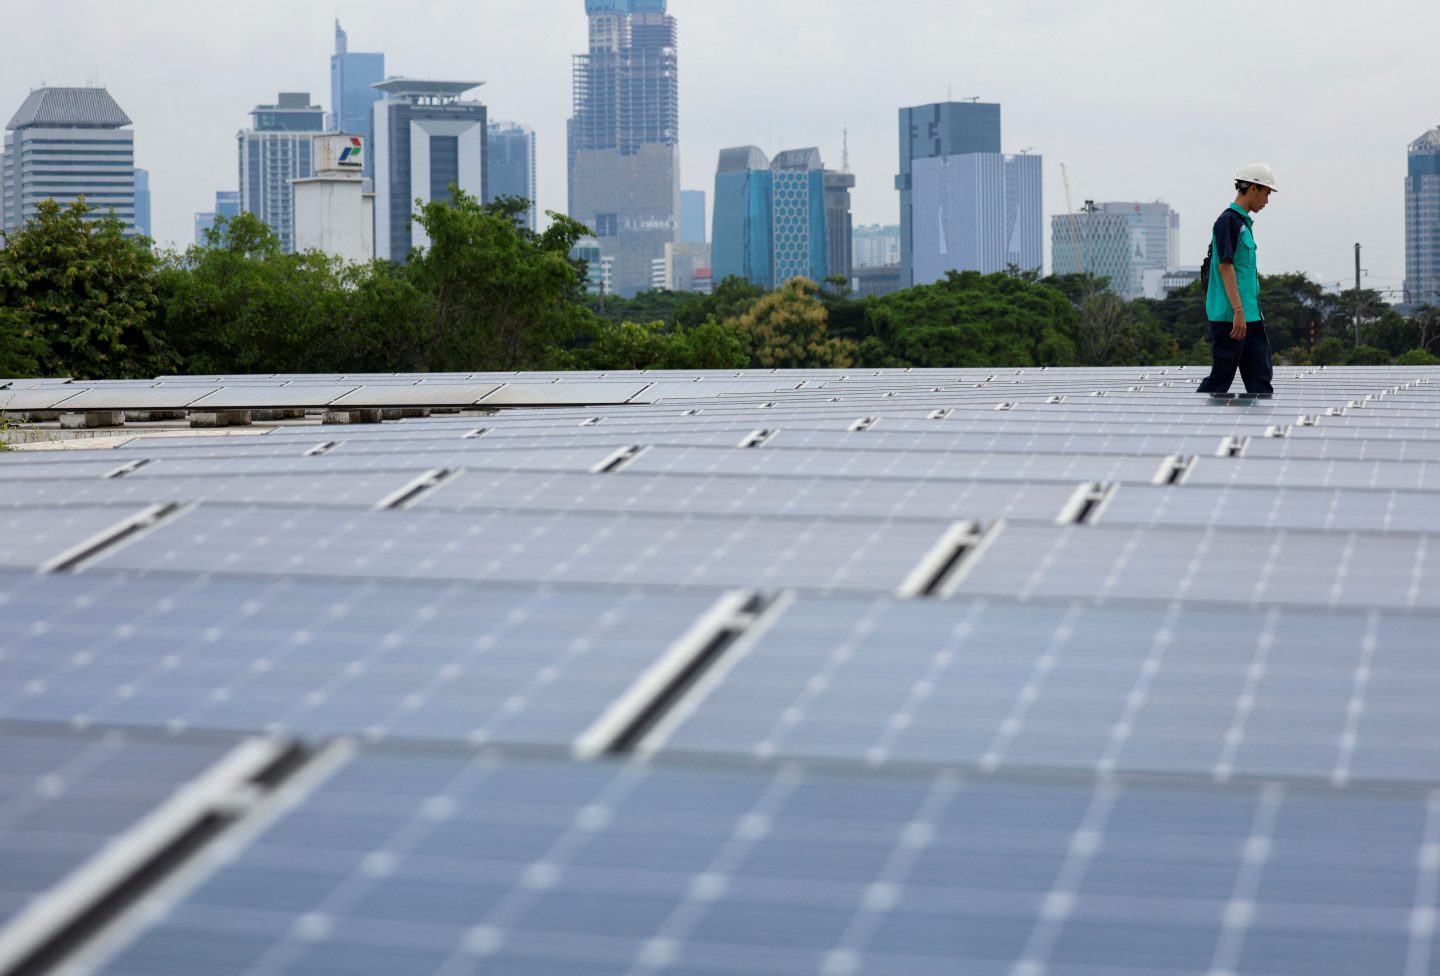
First conceptualised in 1997, the ASEAN Power Grid has gained fresh impetus in recent years as countries turn to renewables to cut their emissions and move away from volatile fossil fuel markets.
Energy supply disruption caused by wars in Ukraine and the Middle East has strengthened the case for regional grid connections. Before this year’s conflict began, the Middle East accounted for 60% of Southeast Asia’s crude oil imports. Competition for fewer, more expensive oil and gas shipments has left Southeast Asia facing a $160 billion energy import bill this year. Based on current policies, this could rise to $400 billion by mid-century.
In the Philippines last week, energy ministers agreed on an enhanced planning framework to deliver the ASEAN Power Grid and made progress on regulatory guidelines.
Garin said ministers were considering accelerating the project’s delivery. “The first study was to connect [by] 2045 – that’s too far,” she said.
A strong business case
The economic benefits of the plan have “captured the political imagination” of leaders in the region, Robert Cooke, grids advocacy lead at the Global Renewables Alliance, told Climate Home News. “The business case is stronger than ever,” he said.
“If countries were to go about building their own separate grids, of course that would be an expensive endeavour. But the discussion around the ASEAN Power Grid includes what costs could we share in building out this grid,” added Tiza Mafira, director of the Indonesia office for the Climate Policy Initiative.
Stronger grids would help the region meet collective targets to increase the share of renewable energy in total primary energy supply from 14% to 30% and in installed power capacity from 34% to 45% by 2030.
Connecting and pooling dispersed renewable resources would also help smooth local power shortages caused by daily and seasonal variations, reducing the need for backup gas plants and battery storage.
The IEA found the ASEAN Power Grid could help unlock some of the 20 terawatts of untapped solar and wind potential across Southeast Asia – an amount around 55 times the region’s current total power capacity.
From lines on a map to shovels in the ground
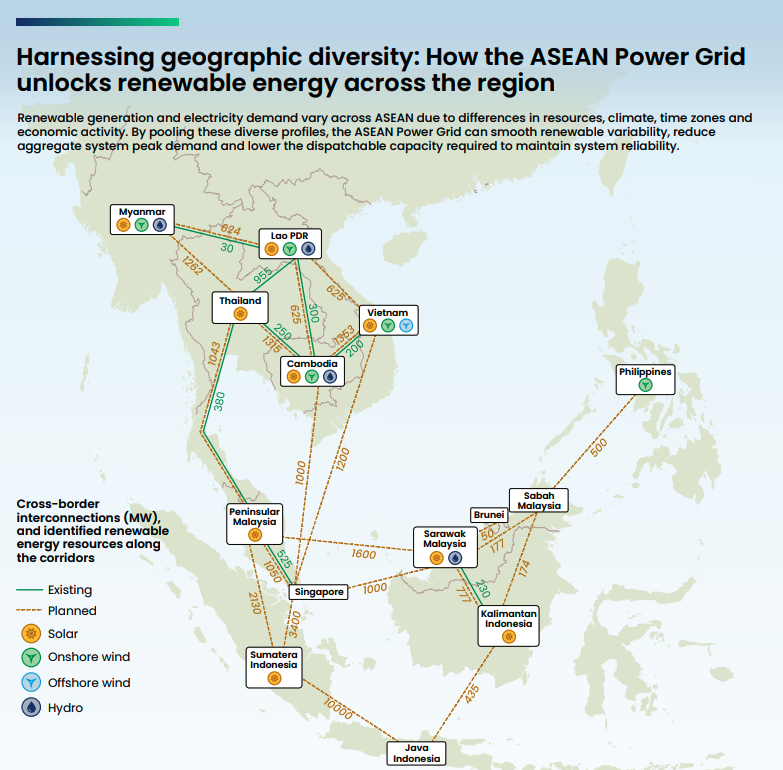
Rather than building a single unified network, the ASEAN Power Grid is developing cross-border links between neighbouring countries and smaller groups of nations.
As of 2025, nine of 18 priority interconnection projects are operational – accounting for around 10 GW of capacity with an additional 13.7 GW planned by 2040.
Source: Ember
A power line channelling up to 200 MW of clean electricity generated from hydropower in Laos to Singapore via Thailand and Malaysia has emerged as a key building block for grid-to-grid trading.
Progress on technical discussions will also help provide the clarity the private sector needs to invest in bankable projects, said Cooke.
In 2025, the Asian Development Bank and the World Bank announced a dedicated funding initiative to support the project.
“The enabling pieces are emerging,” said Monalisa Dimalanta, former chair of the Philippine Energy Regulatory Commission and the National Renewable Energy Board. “But the timelines remain unclear and a 2045 vision cannot answer today’s emergency,” she said.
“A power grid… that exists only on paper will not keep the lights on.”
Singapore: the delivery test
The implications of failing to deliver the ASEAN Power Grid are most acute in Singapore.
Constrained by space, with few renewable energy resources and dependent on gas for more than 90% of its electricity mix, Singapore has emerged as a leading proponent of a regional power grid as it seeks to achieve net-zero emissions by 2050.
To meet its power needs, the city-state aims to import 6 GW of low-carbon electricity by 2035, around one-third of its energy demand – a target which it is set to miss, however.
The plans heavily rely on building interconnectors to import solar power from Indonesia across the South China Sea. Around 40% of the ASEAN Power Grid’s planned interconnections are directed towards Singapore.
Ember’s analysis found that delivering the planned interconnectors by 2035 could enable renewables to meet nearly half of Singapore’s electricity demand. Delays could drop this to only a fraction of the country’s needs, and risk locking in new gas capacity until the 2050s. Without the ASEAN Power Grid, Singapore would need to install an additional 300 MW of gas-fired power capacity to bridge the gap by 2035.
Already home to the largest data centre capacity in Southeast Asia, Singapore’s electricity demand keeps rising, driven by the boom in AI infrastructure. “At one point, [it] either has to build a new gas plant, or it has to get the interconnection to supply that demand,” Lam Pham, an Ember energy analyst and the report’s author, told Climate Home News.
A region at a crossroads
With capital increasingly available, political will is now the biggest risk standing in the way of timely execution, said Pham.
But there are other challenges too, including the lack of frameworks on transmission tariffs and how to share the benefits of clean power trading. “It’s really hard to justify projects without that,” he said.
In addition, climate-fuelled weather events, including extreme heat and tropical storms, pose major threats to the region’s grid infrastructure. Experts say stronger grid interconnection can isolate damage and build the system’s resilience.
Efforts to deliver on the ASEAN Power Grid also come as ministers stressed the “continued importance of oil and gas” for economic development and seek to secure fossil fuel supplies and stockpile oil to prepare for the next crisis.
Despite an acceleration of renewable deployment, particularly solar, coal still generates nearly half the electricity supply in ASEAN member states and dominates the power mix in Indonesia, the Philippines and Vietnam, while Singapore and Thailand rely on gas.
While these measures might help the region with the immediate crisis, “the long-term answer is more domestic renewable energy, electrification, storage, efficiency and regional power trade”, Dimalanta said.
Main image: An aerial view of the MTerra solar project in the Philippines, set to become one of the world’s largest solar-and-battery developments (Photo by Ezra Acayan/Getty Images)
The post SE Asia speeds up plan for connected clean power grid after oil shock appeared first on Climate Home News.
SE Asia speeds up plan for connected clean power grid after oil shock