

Andy Burnham, the UK’s latest prime minister, has suggested reducing the amount the British government gives as climate finance grants and providing some of its climate finance through loans instead, in a move it anticipates will save £400 million.
The government plans to use the savings to fund a cap on bus fares in the UK, triggering accusations from the development sector that Burnham’s proposal “throws Global South countries under the bus”. One likely destination for these new loans is the Tropical Forest Forever Facility (TFFF).
Will new UK PM’s green measures at home cause climate finance pain overseas?
The TFFF is a new initiative designed to provide payments to countries that protect their rainforests by raising money from governments and private investors, channeling that money into riskier and therefore higher return assets, and using the returns it earns to fund forest protection. But there is a catch.
The UK has committed to provide around £6 billion in climate finance funded through aid (or official development assistance, ODA) over the next three years. If switching from grants to a loan to the TFFF reduces government spending, it will likely reduce the amount that counts as ODA as well.
In other words, the government can make the £400 million saving, or meet its £6 billion aid budget-funded climate finance commitment, but it probably cannot do both. The UK cannot have its cake and eat it.
How will it score as ODA?
Whether any loan to the TFFF scores as ODA depends on the OECD’s Development Assistance Committee (DAC) which is currently deliberating on this topic.
A plain reading of the DAC’s current reporting rules suggests that the TFFF would count as a multilateral organisation: the independent investment arm, the Tropical Forest Investment Fund, would ultimately be a global, official entity (with sovereign governments appointing the board and being sole equity holders), which pools capital from sponsor governments. This would mean that to count as ODA, any loan to it would have to charge less than 5% interest.
Tropical forest protection fund at risk after UK stalls on pledge
The current concept note suggests a return for sponsor capital equivalent to US borrowing costs of a similar duration: currently around 5.2%, which would make any such loans ineligible. The UK could choose to charge less, but if the UK charges less than it borrows (also above 5%), the difference will add to the deficit in future years. And ODA accounting is not binary: if the UK charges just under 5%, only a small fraction of the loan would count.
At the same time, the risk profile of TFFF is not the same as your average multilateral, and there is speculation that the DAC could allow higher interest loans to TFFF to partially count (by changing the ‘discount rate’ used to measure how concessional the loan is). The TFFF’s own modelling suggests that the risk of the UK losing money on the loan would be fairly limited: roughly a 1% chance of some capital impairment in the riskiest scenario. But some analysts doubt the accuracy of this model and view the risk as much greater.

Would it really save money?
If the risk really is higher, then it might justify counting more ODA on a loan to the TFFF, but it also undermines the arguments that this would create savings for the government. Loans generally don’t count towards the deficit because they create an asset. But that only works if the loan is expected to be fully repaid. If there is a material risk of losing money, then at least some of the transaction will also count towards the deficit.
One possibility is that the loan will be ‘partitioned’ into a financial asset (the part which is expected to be repaid and wouldn’t count towards the deficit) and a ‘capital transfer’ (the part not expected to be repaid). The greater the risk, the larger that second component, and the bigger the impact on the deficit.
This would be the ODA and public accounting rules working as intended. ODA is a measure of ‘donor effort’, usually taken to mean fiscal impact. If it counts as ODA, it should have an impact on the deficit. And the fiscal treatment itself is governed by numerous international accounting standards, a key purpose of which is preventing politically motivated obfuscation of how governments spend their money. If it costs money, there should be an impact on the deficit even if it is a loan. If it doesn’t, it shouldn’t count as ODA (even if there have been exceptions in the past).
UK halves Green Climate Fund contribution, as it spends more on security
Base funding on need, not accounting
We still know too little about the details to be sure how a loan to the TFFF (or a more exotic transaction) would count towards either ODA or the UK’s headline measures of debt and deficit. The key parameter for each is risk: the lower risk, the more likely it is that the transaction will save money, but the greater the chance that the government would have to spend more ODA elsewhere to meet its climate finance target.
If the UK believes in the TFFF business model and wants to preserve tropical forests, then it should invest. But this decision should not be driven by optimistic accounting tricks. The government cannot expect to reduce the real value of climate finance to partner countries by giving less in grant money, without this having an impact on commitments to spend that money.
The post UK’s budget juggling trick with rainforest loan for bus-fare cap needs transparency appeared first on Climate Home News.
UK’s budget juggling trick with rainforest loan for bus-fare cap needs transparency

For the first time, new-energy vehicles (NEVs) made up 67% of new car sales in China in September, according to the latest data from the China Passenger Car Association (CPCA).
The figures show that NEVs, which include battery electric cars and plug-in hybrids, captured a record share of sales, even though fewer were sold than last year.
This is because sales of combustion-engine cars are falling steeply, a trend that the CPCA has attributed to rising petrol prices following the start of the Hormuz crisis.
Indeed, sales of fuel-only cars were down 31% year-on-year in the first nine months of 2026, with plug-in hybrid sales down 26% – whereas battery EV sales were only down 4%.
One analyst tells Carbon Brief that China’s rapidly growing EV fleet has offset demand for 143m barrels of oil since the start of the Hormuz crisis.
Another says that the crisis is “reinforcing China’s electrification of road transport”.
Meanwhile, amid slowing domestic sales, Chinese carmakers’ exports of NEVs more than doubled [in 2026 to date / in September] from a year earlier.
NEV record
A record two out of every three cars sold in September in China were NEVs, according to CPCA data, as shown in the figure below.
(NEVs predominantly include battery electric vehicles – BEVs – and plug-in hybrids – PHEVs. BEVs only run on electricity, whereas PHEVs also have a combustion engine.)
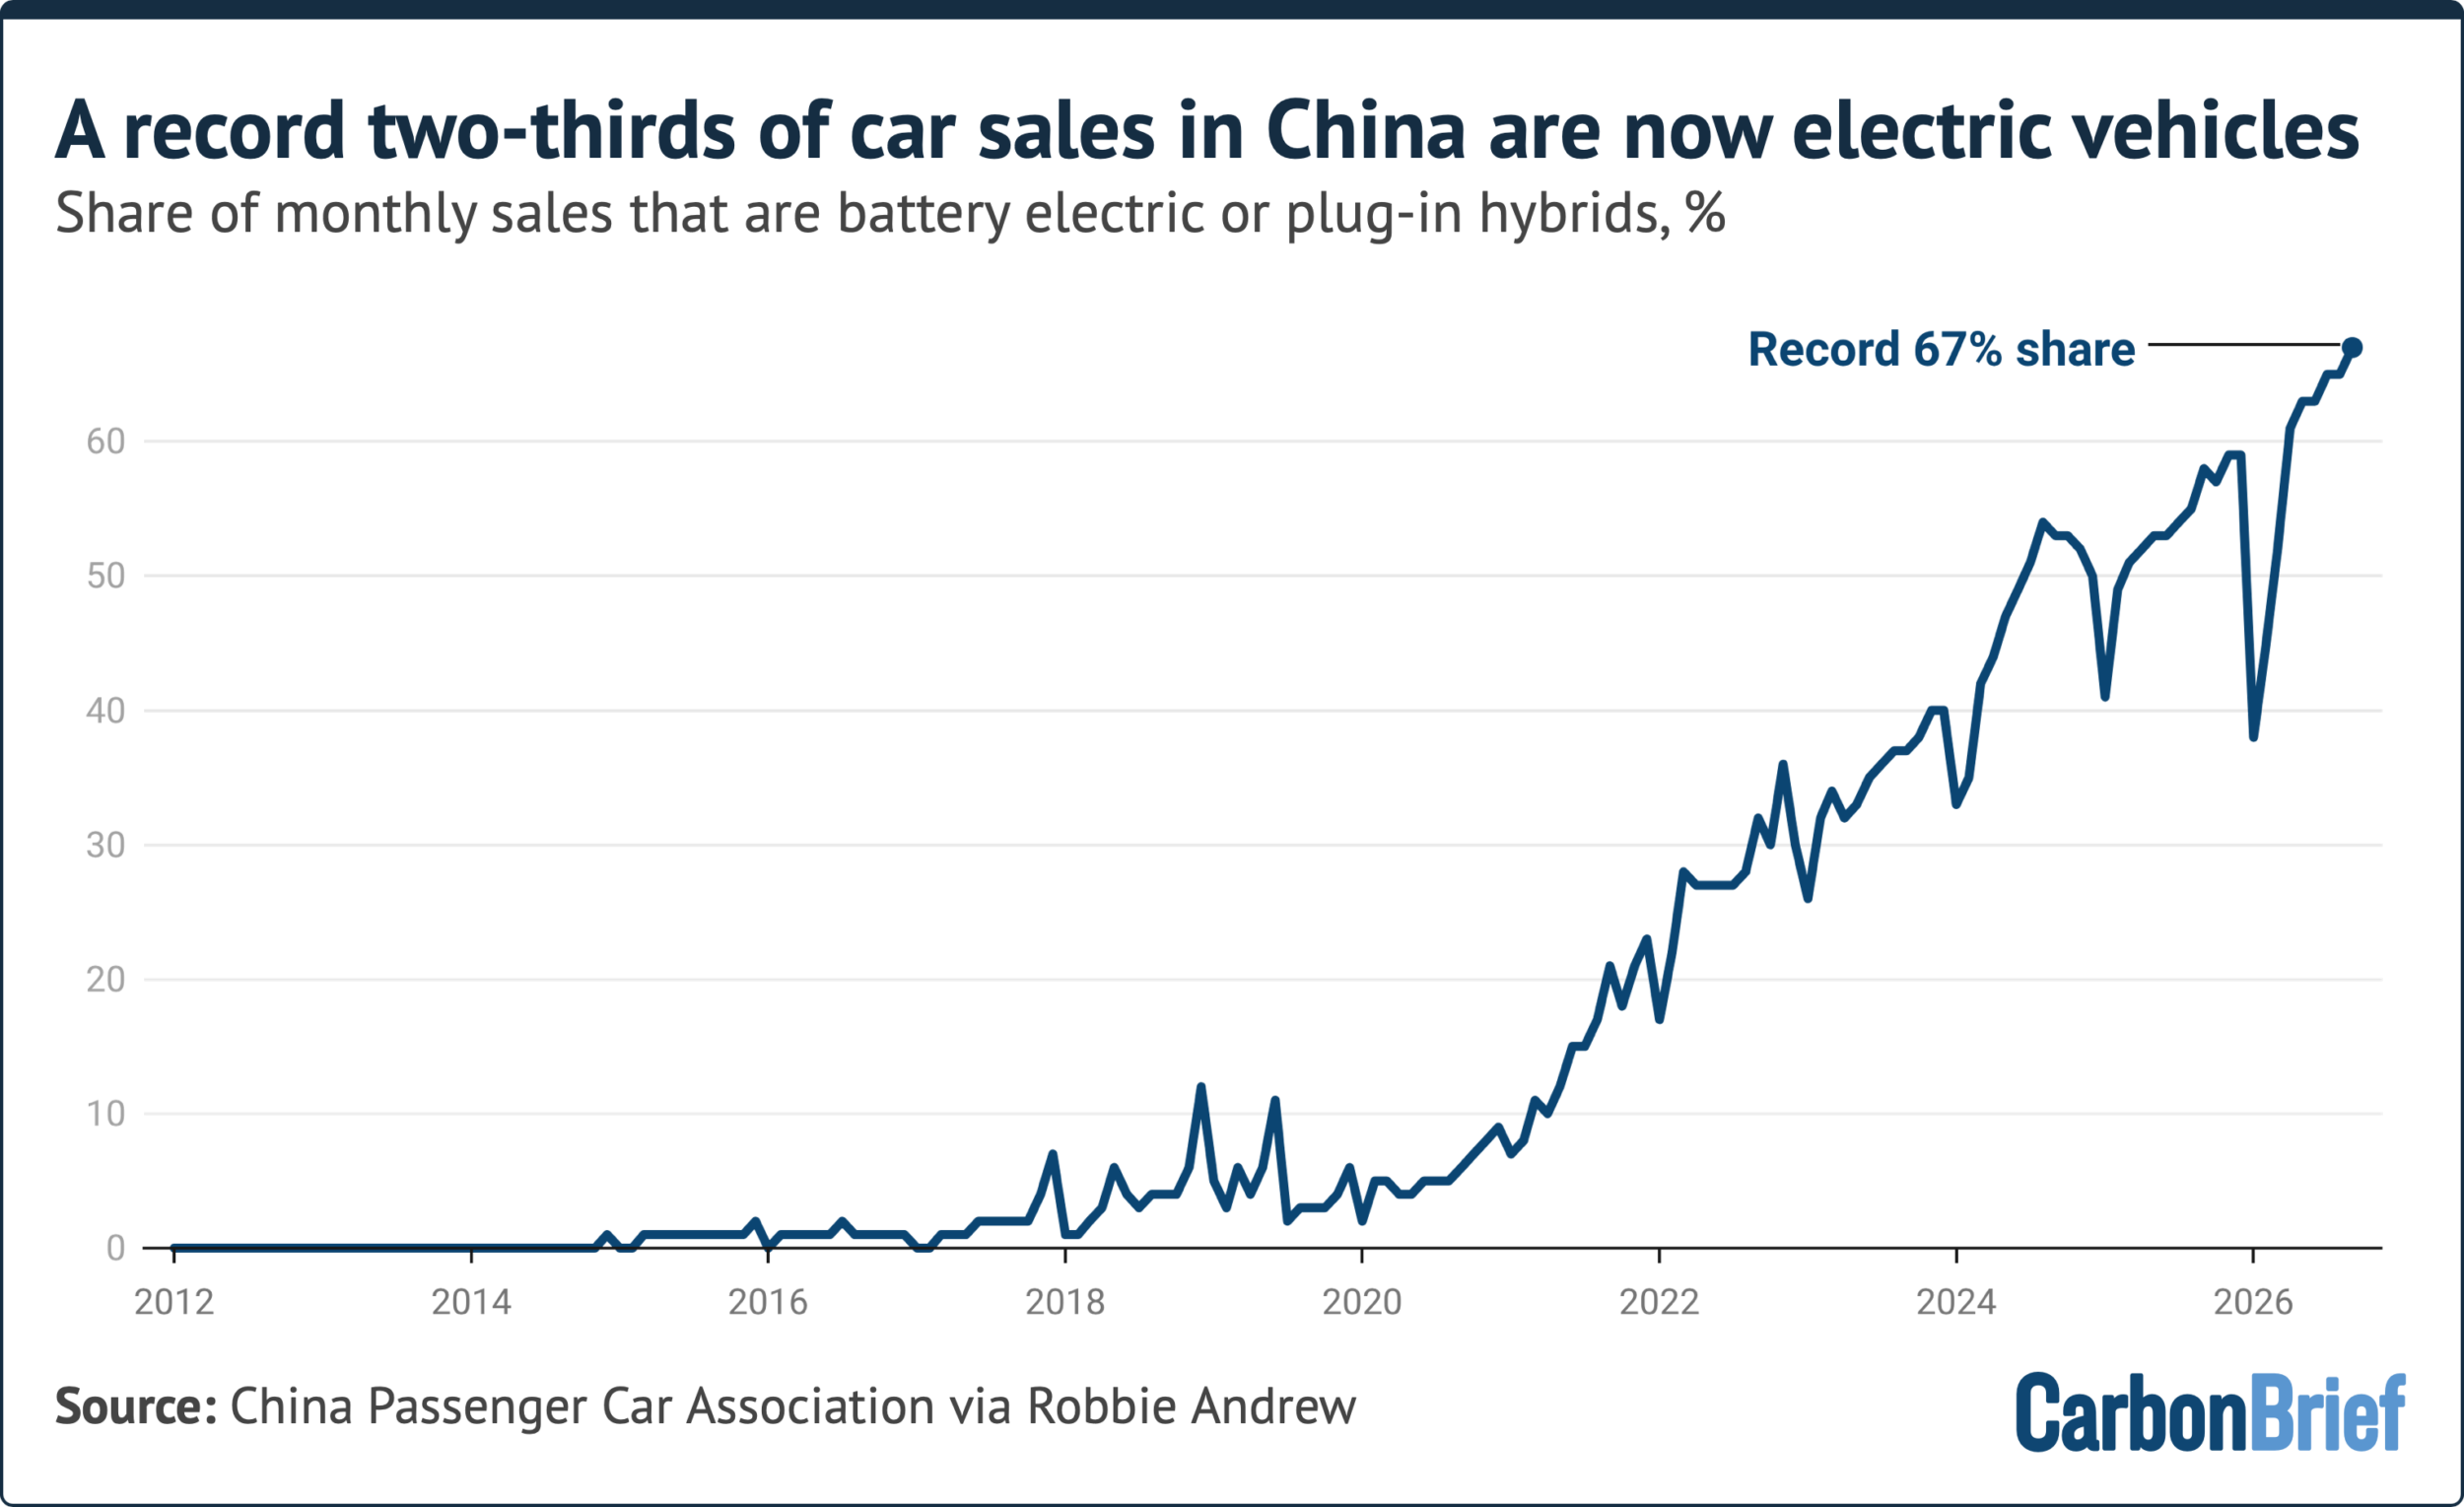
This marks a rapid rise for NEVs from just 6% of new car sales in 2020 up to 58% in 2026 to date – and a record 67% in the month of September.
This year, NEVs’ share of sales has also bounced back from a low of 39% in January, after the full purchase tax exemption that had been in place for more than a decade came to an end in December 2025.
The gain in NEV share in 2026 has come amid a slowdown across the wider domestic passenger-car market, which has hit sales of combustion-engine vehicles particularly hard.
This September, passenger-car retail sales across all categories declined, with overall sales volumes falling 28% year-on-year.
The contraction was led by combustion-engine vehicles, which saw sales fall 43% year-on-year in September and 31% in 2026 to date.
However, sales of PHEVs also fell by 36% year-on-year in September and by 26% in 2026 to date. By comparison, BEVs performed better, although sales still declined 8.5% from a year earlier in September and 4% in 2026 to date.
As a result, NEV sales overall fell by 17% in September and 13% in 2026 to date.
While the market changes in 2026 to date were particularly dramatic, they reflect a broad continuation of trends seen over the past decade.
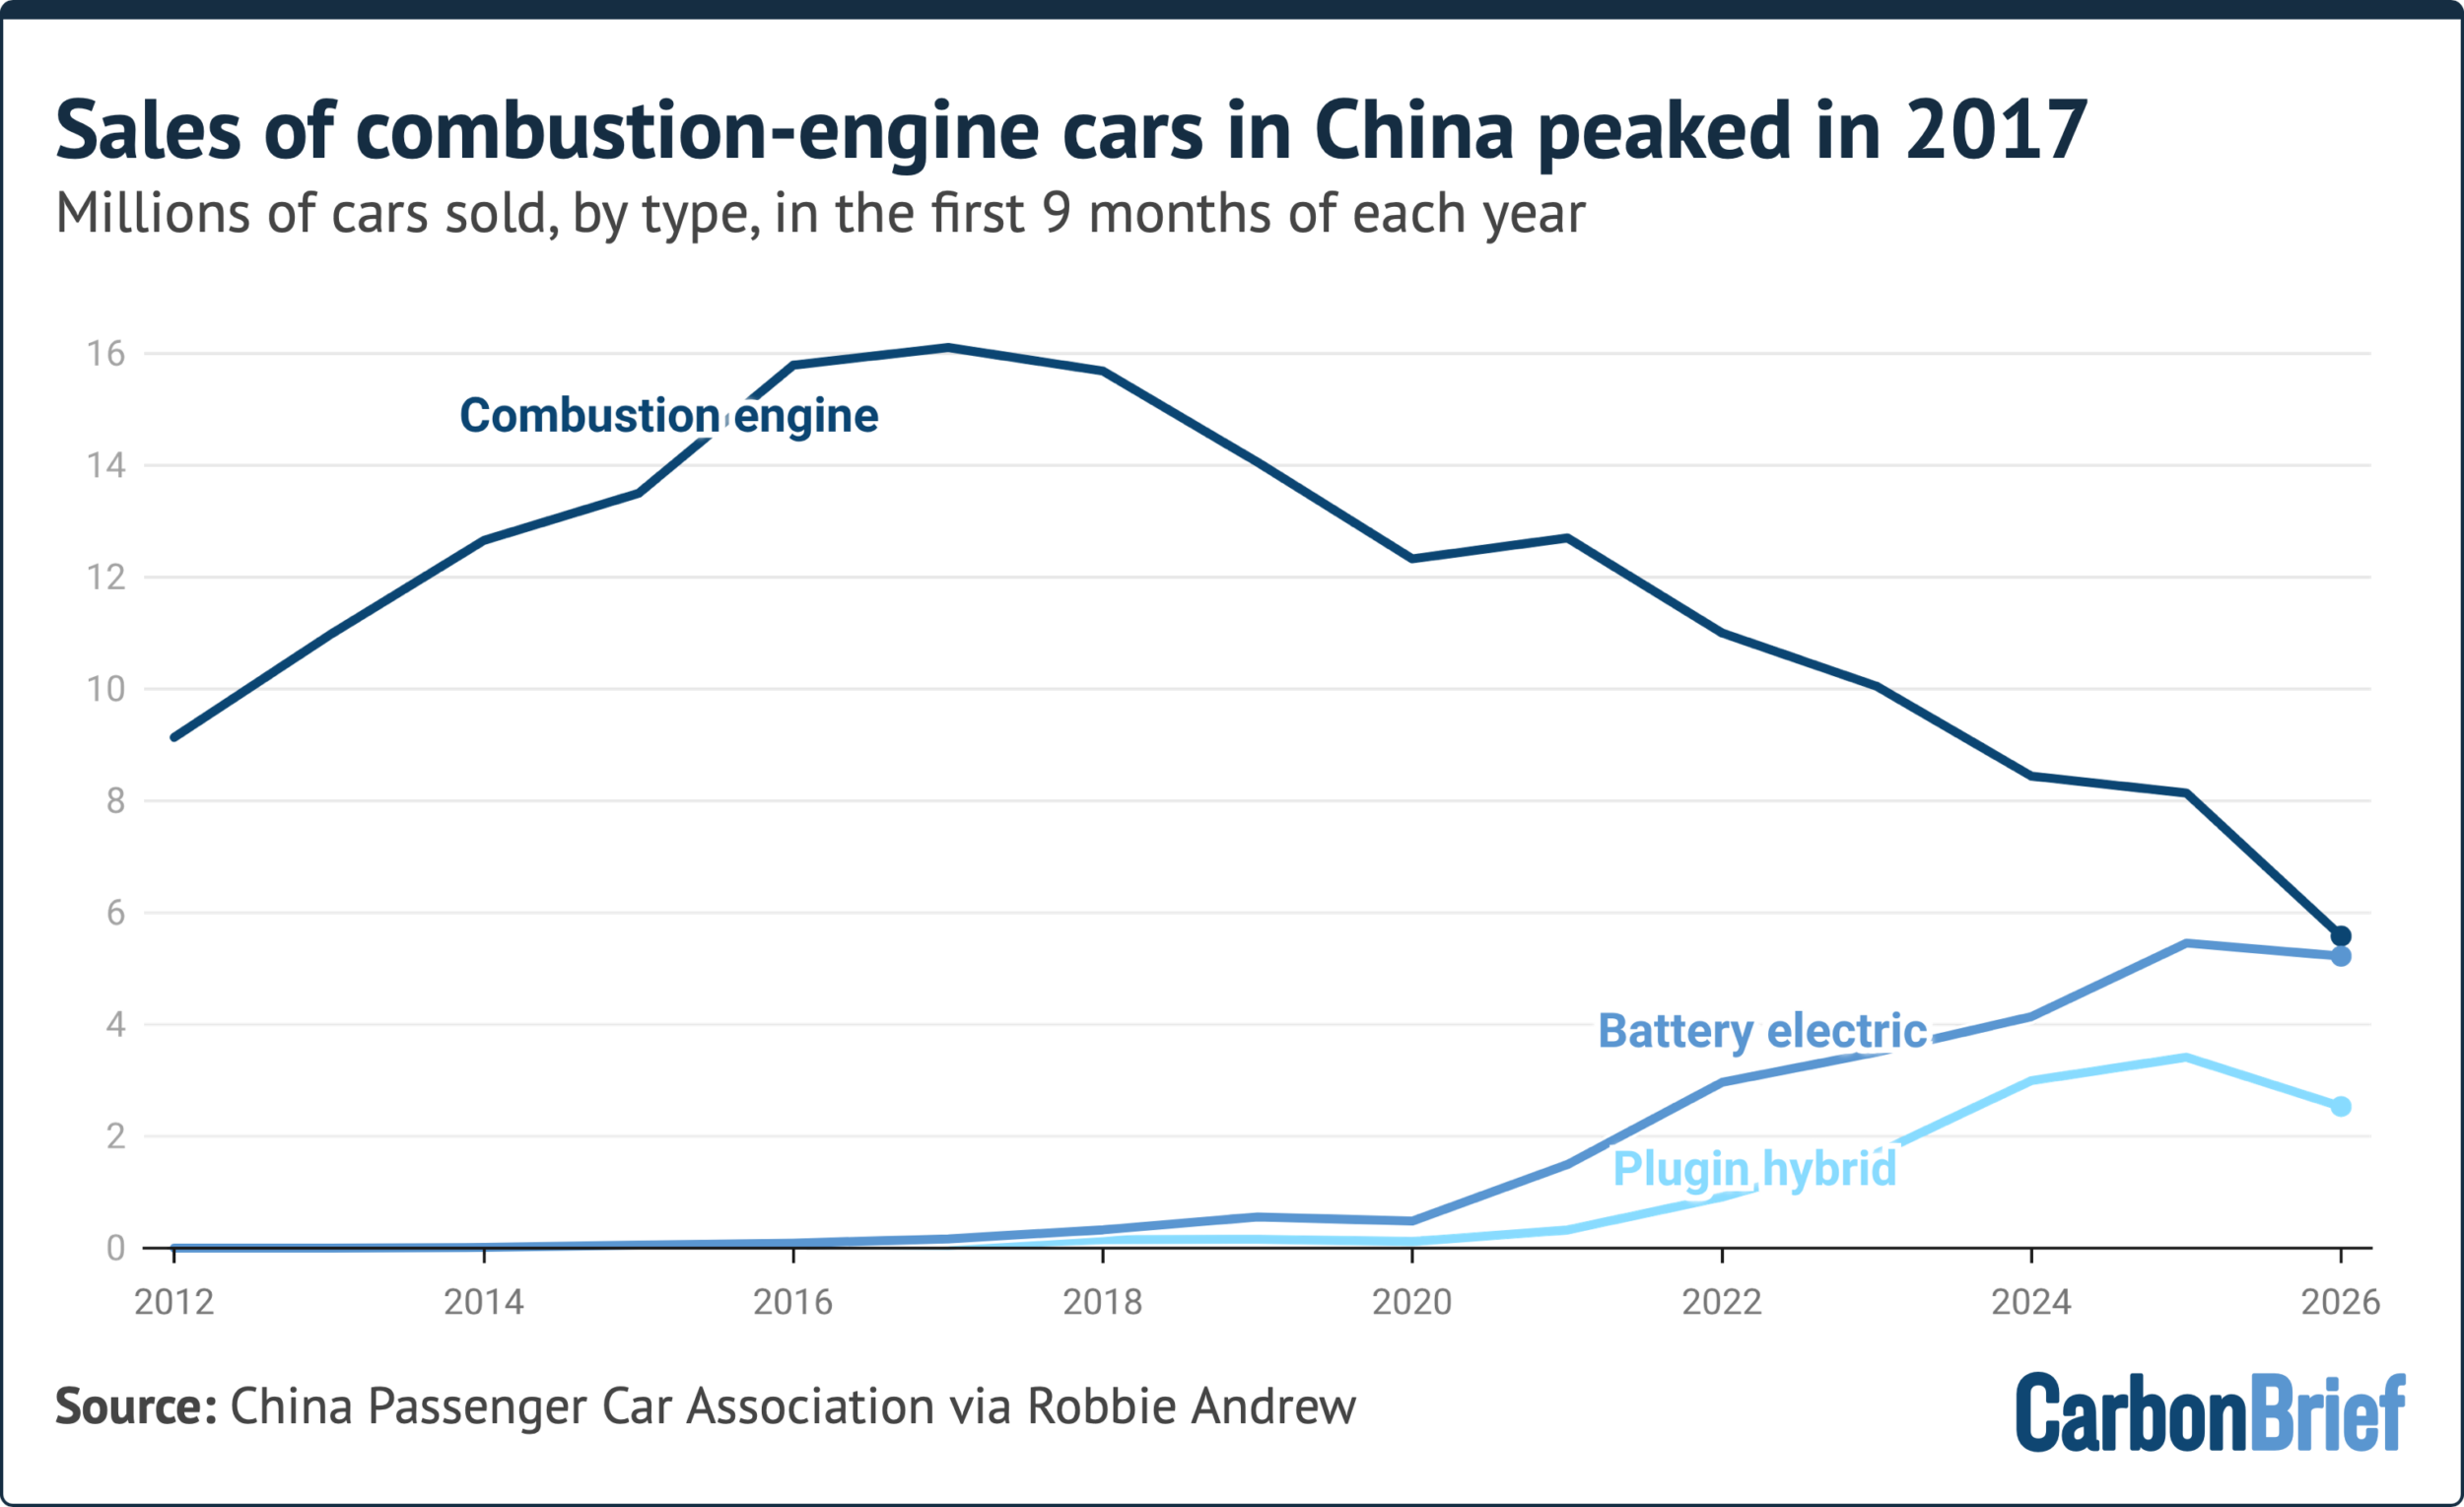
Indeed, sales of combustion-engine cars in China peaked in 2017 and they have been declining ever since, shown in the figure below.
Impact of Hormuz
Part of the reason for the advance of NEVs in 2026, said Chinese technology news outlet OFweek, was petrol cars “giving up market share” as they were outperformed by electric alternatives.
Cui Dongshu, secretary-general of the CPCA, cited higher petrol prices as an explanation for September’s weak combustion-car sales, in comments to financial news outlet National Business Daily.
Imports of oil into China in January-September have fallen 15% compared to 2025, equivalent to 470m barrels, as ongoing conflict tightened supply and drove up prices.
China’s passenger-car NEV fleet has displaced 143m barrels of oil so far during the strait of Hormuz crisis, Euan Graham, senior energy analyst at thinktank Ember, tells Carbon Brief.
EVs “accounted for 12% of the decrease in China’s oil use post-Hormuz”, according to an estimate provided to thinktank the Brookings Institute by an unnamed analyst.
Erica Downs, a senior research scholar at Columbia University’s Center on Global Energy Policy, tells Carbon Brief that the strait of Hormuz crisis and higher oil prices are “reinforcing China’s electrification of road transport”.
She says the “world’s largest oil supply disruption” vindicates China’s early bet on EVs, which was partly driven by concerns about oil-supply security.
NEV demand down
Nevertheless, NEV sales have fallen year-on-year, albeit at a slower rate than overall car sales. The growth in NEV market share has also been decelerating.
Zhang Yichao, a partner at consulting firm AlixPartners, tells Carbon Brief that NEVs benefit from government trade-in policies and a “strong pipeline” of new models, particularly those involving innovation.
He says these factors help explain why NEVs sales have fallen at a slower rate to their combustion-car counterparts.
Cui told the state-run China National Radio that the fall for NEVs and for cars overall in September 2026, is also due to a high baseline of sales from the same month in 2025, as well as changes to trade-in policies and disruptions from the holiday period.
Other factors, says consulting firm Wood Mackenzie, are the weakened demand due to “demand pull-forward” in 2025 caused by the end of subsidies, as well as “tighter financing conditions”.
Zhang tells Carbon Brief he does not “see much more room ahead” for further growth in NEVs’ market share.
He adds that, in his view, their share in China is unlikely to exceed 80%, as some premium-market segments and specific use cases will continue to require combustion-engine vehicles.
Exports surge
Meanwhile, while domestic NEV retail sales fell 17% in September 2026, exports more than doubled, increasing 164% year-on-year, according to the CPCA.
This extends the decline in domestic sales and very strong growth in exports seen across 2026 to date, as shown in the figure below.
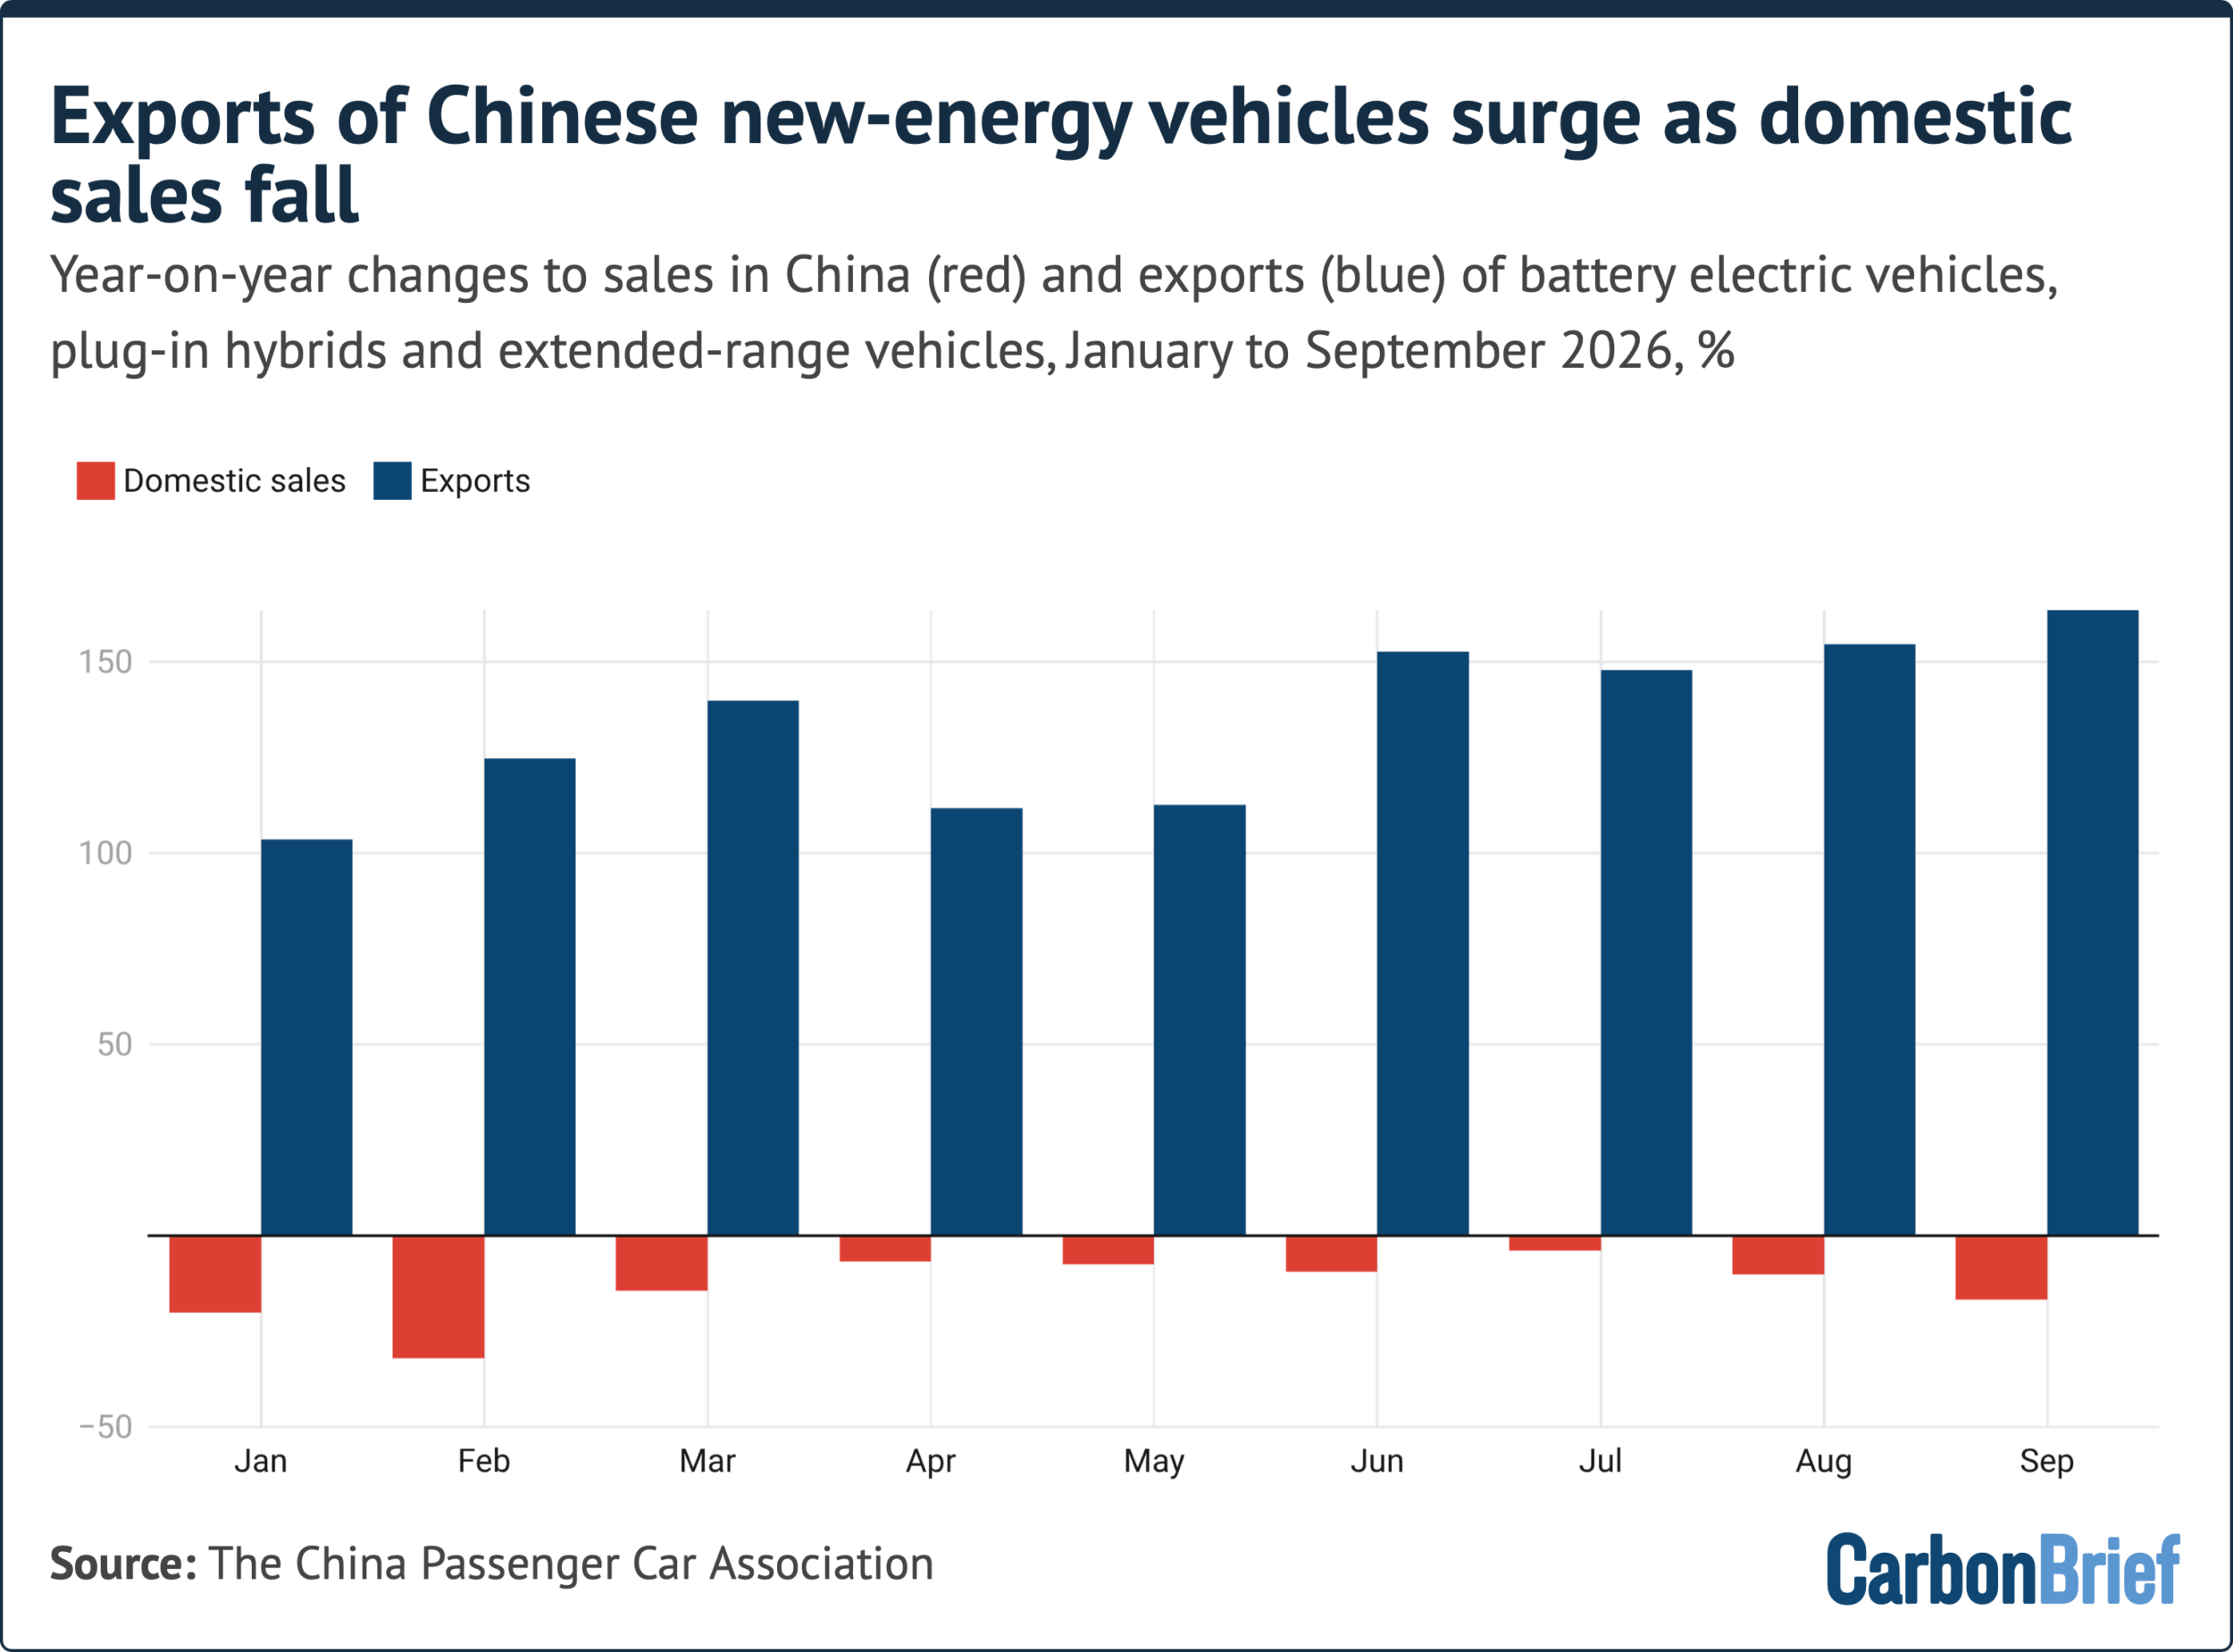
In September, 1,084,000 NEVs were sold domestically in China, while 558,000 NEVs were exported.
Exports are becoming increasingly important to Chinese carmakers, in the face of weaker domestic demand and cut-throat industrial competition.
The CPCA says exports have become “a core priority” for some carmakers.
However, the surge in exports from China has create