

War-torn Ukraine can aid the European Union in securing the battery materials it needs to accelerate the transition from fossil fuels to clean energy systems, researchers say.
The eastern European country holds deposits of 25 of the EU’s 34 minerals listed as “critical” to its economy. This includes Europe’s largest reserves of graphite and manganese, which are needed to manufacture batteries for electric vehicles (EVs) and energy storage, as well as titanium, which is used in offshore wind turbines and hydrogen electrolysers.
Ukraine has the potential to become a regional supplier of battery-grade graphite to the EU as the bloc seeks to bolster its mineral supplies and reduce its dependence on China for materials, according to analysis by Forum Energii and Green Deal Ukraïna published this week.
A ‘targeted’ solution to Europe’s needs
Graphite is the most prominent critical mineral by weight in a typical EV or energy storage battery and the booming battery market is causing demand to soar.
But the EU mines less than 0.1% of its total graphite needs and depends heavily on imports from China, which produces over 95% of the world’s battery-grade graphite. In 2024, only around 2% of total EU natural graphite imports came from Ukraine but this share could be much higher, researchers said.
Plans to develop a graphite mine and processing plant outside the village of Balakhivka in central Ukraine, could potentially meet 10% of Europe’s graphite consumption by 2030 and supply the battery industry, according to the report.
-
Dutch startup’s rust-powered batteries could help crack Europe’s energy storage gap
Ore Energy says its long-duration batteries made of iron and air can help Europe cut its dependence on critical minerals supply chains and boost renewables -
The energy transition has a rare earth problem: These startups are solving it
China’s grip on global supply chains is turbocharging efforts to find alternatives to the small group of metals that dominate EV motor technology -
How green are batteries for electric vehicles?
What you need to know about electric vehicles (EVs) and their batteries


The project has been designated as “strategic” by the European Commission, making it eligible for preferential access to EU financing. The European Bank for Reconstruction and Development (EBRD) has signalled its interest in supporting the project.
Danylo Moiseienko, an analyst at Forum Energii and lead author of the report, said Ukraine’s contribution to the EU’s mineral supply will be “targeted…exactly what Europe needs to diversify away from single-source dependencies”.
Over the next two years, the challenge for Ukraine will be to translate its geological potential into a pipeline of mineral projects that qualify for EU support and “make sure that over time, more of the value stays in Ukraine,” he said.
The price of war
Russia’s ongoing war in Ukraine remains a major barrier to developing the country’s mineral potential, however.
Four years of conflict have devastated Ukraine’s energy and transport infrastructure, pushed up the cost of capital and disrupted access to mineral deposits, some of which are now in Russian-occupied territories, including two of Ukraine’s six major graphite deposits.
In addition, Ukraine’s energy system has come under persistent attack from Russian drones and missile strikes, weakening the country’s ability to power energy-hungry mining and processing operations. The World Bank estimates the country’s energy sector has suffered nearly $25 billion worth of damage, with the total cost of rebuilding estimated at more than $90 billion.
Ukraine’s graphite production fell by 88% between 2021 and 2024 due to a temporary shutdown of its only operating mine and electricity supply disruptions from Russian attacks. The report says that during that time, the EU – which signed a minerals partnership with Kyiv to develop its mineral resources – remained the main buyer of Ukrainian graphite, as the country drew down on its stocks.
Ksenia Orynchak, CEO of the National Association of Extractive Industry of Ukraine, said investment in the mineral sector will be an important part of Ukraine’s post-war reconstruction and economic recovery.
“The mining sector is very important for Ukraine’s reconstruction,” she told Climate Home News during an online presentation of the report’s findings. “If our government manages to stay strong and prioritises our extractive industries, our minerals will help rebuild our country,” she said.
EU, US offer window for new funding
But Ukraine faces other challenges to develop its energy transition mineral deposits.
The country’s geological data is outdated and incomplete, the financing and regulatory environment is unattractive to investors, environmental and social standards are not aligned with international norms and the sector is suffering from a shortage of qualified personnel.
Despite these challenges, the country’s significant mineral resources remain widely coveted. Last year, Donald Trump’s administration signed a minerals deal with Kyiv establishing a joint Reconstruction Investment Fund, which will focus on investment in the energy, critical minerals and infrastructure sectors, and gives the US preferential access to Ukrainian minerals.
The International Development Finance Corporation (DFC), the US’s development finance institute, announced an initial $75 million to launch the fund, an amount matched by the Ukrainian government.
But so far, only two oil and gas projects are in line to receive DFC funding, Orynchak said.
The US deal and the EU partnership have opened a window for mineral projects in Ukraine to access financing but they remain limited, experts said.
“The amount announced by the US fund is not even sufficient to fully develop one mine,” said Tetiana Dzhumurat, a principal banker in the natural resources team at the EBRD, which is supporting Ukraine to digitise its paper-based geological data archive.
At the same time, the pipeline of mineral projects ready to be financed remains “thin”, she said. “I think there is potential, but more remains to be done.”
The post Ukraine can help Europe meet its battery material needs, experts say appeared first on Climate Home News.
Ukraine can help Europe meet its battery material needs, experts say

China’s carbon dioxide (CO2) emissions fell by 3.1% in the third quarter of 2026, as the Hormuz crisis continued to hit oil demand and coal use also dropped.
This guest post is by:
Lauri Myllyvirta, lead analyst at the Centre for Research on Energy and Clean Air
This was the largest quarterly reduction since the 2022 Covid lockdowns and means that China’s CO2 emissions have now fallen by an estimated 0.5% in the year to date.
The new analysis for Carbon Brief, based on official figures and commercial data, shows that coal use fell by 3% year-on-year in the third quarter of 2026, while oil was down 4%.
The main drivers were a fall in power-sector coal consumption, a continued sharp reduction in transport oil consumption and slowing growth in the coal-to-chemical industry.
The sharp decline in China’s CO2 emissions extends a “flat or falling” trend that began in March 2024 and has now lasted more than two years, as shown in the figure below.
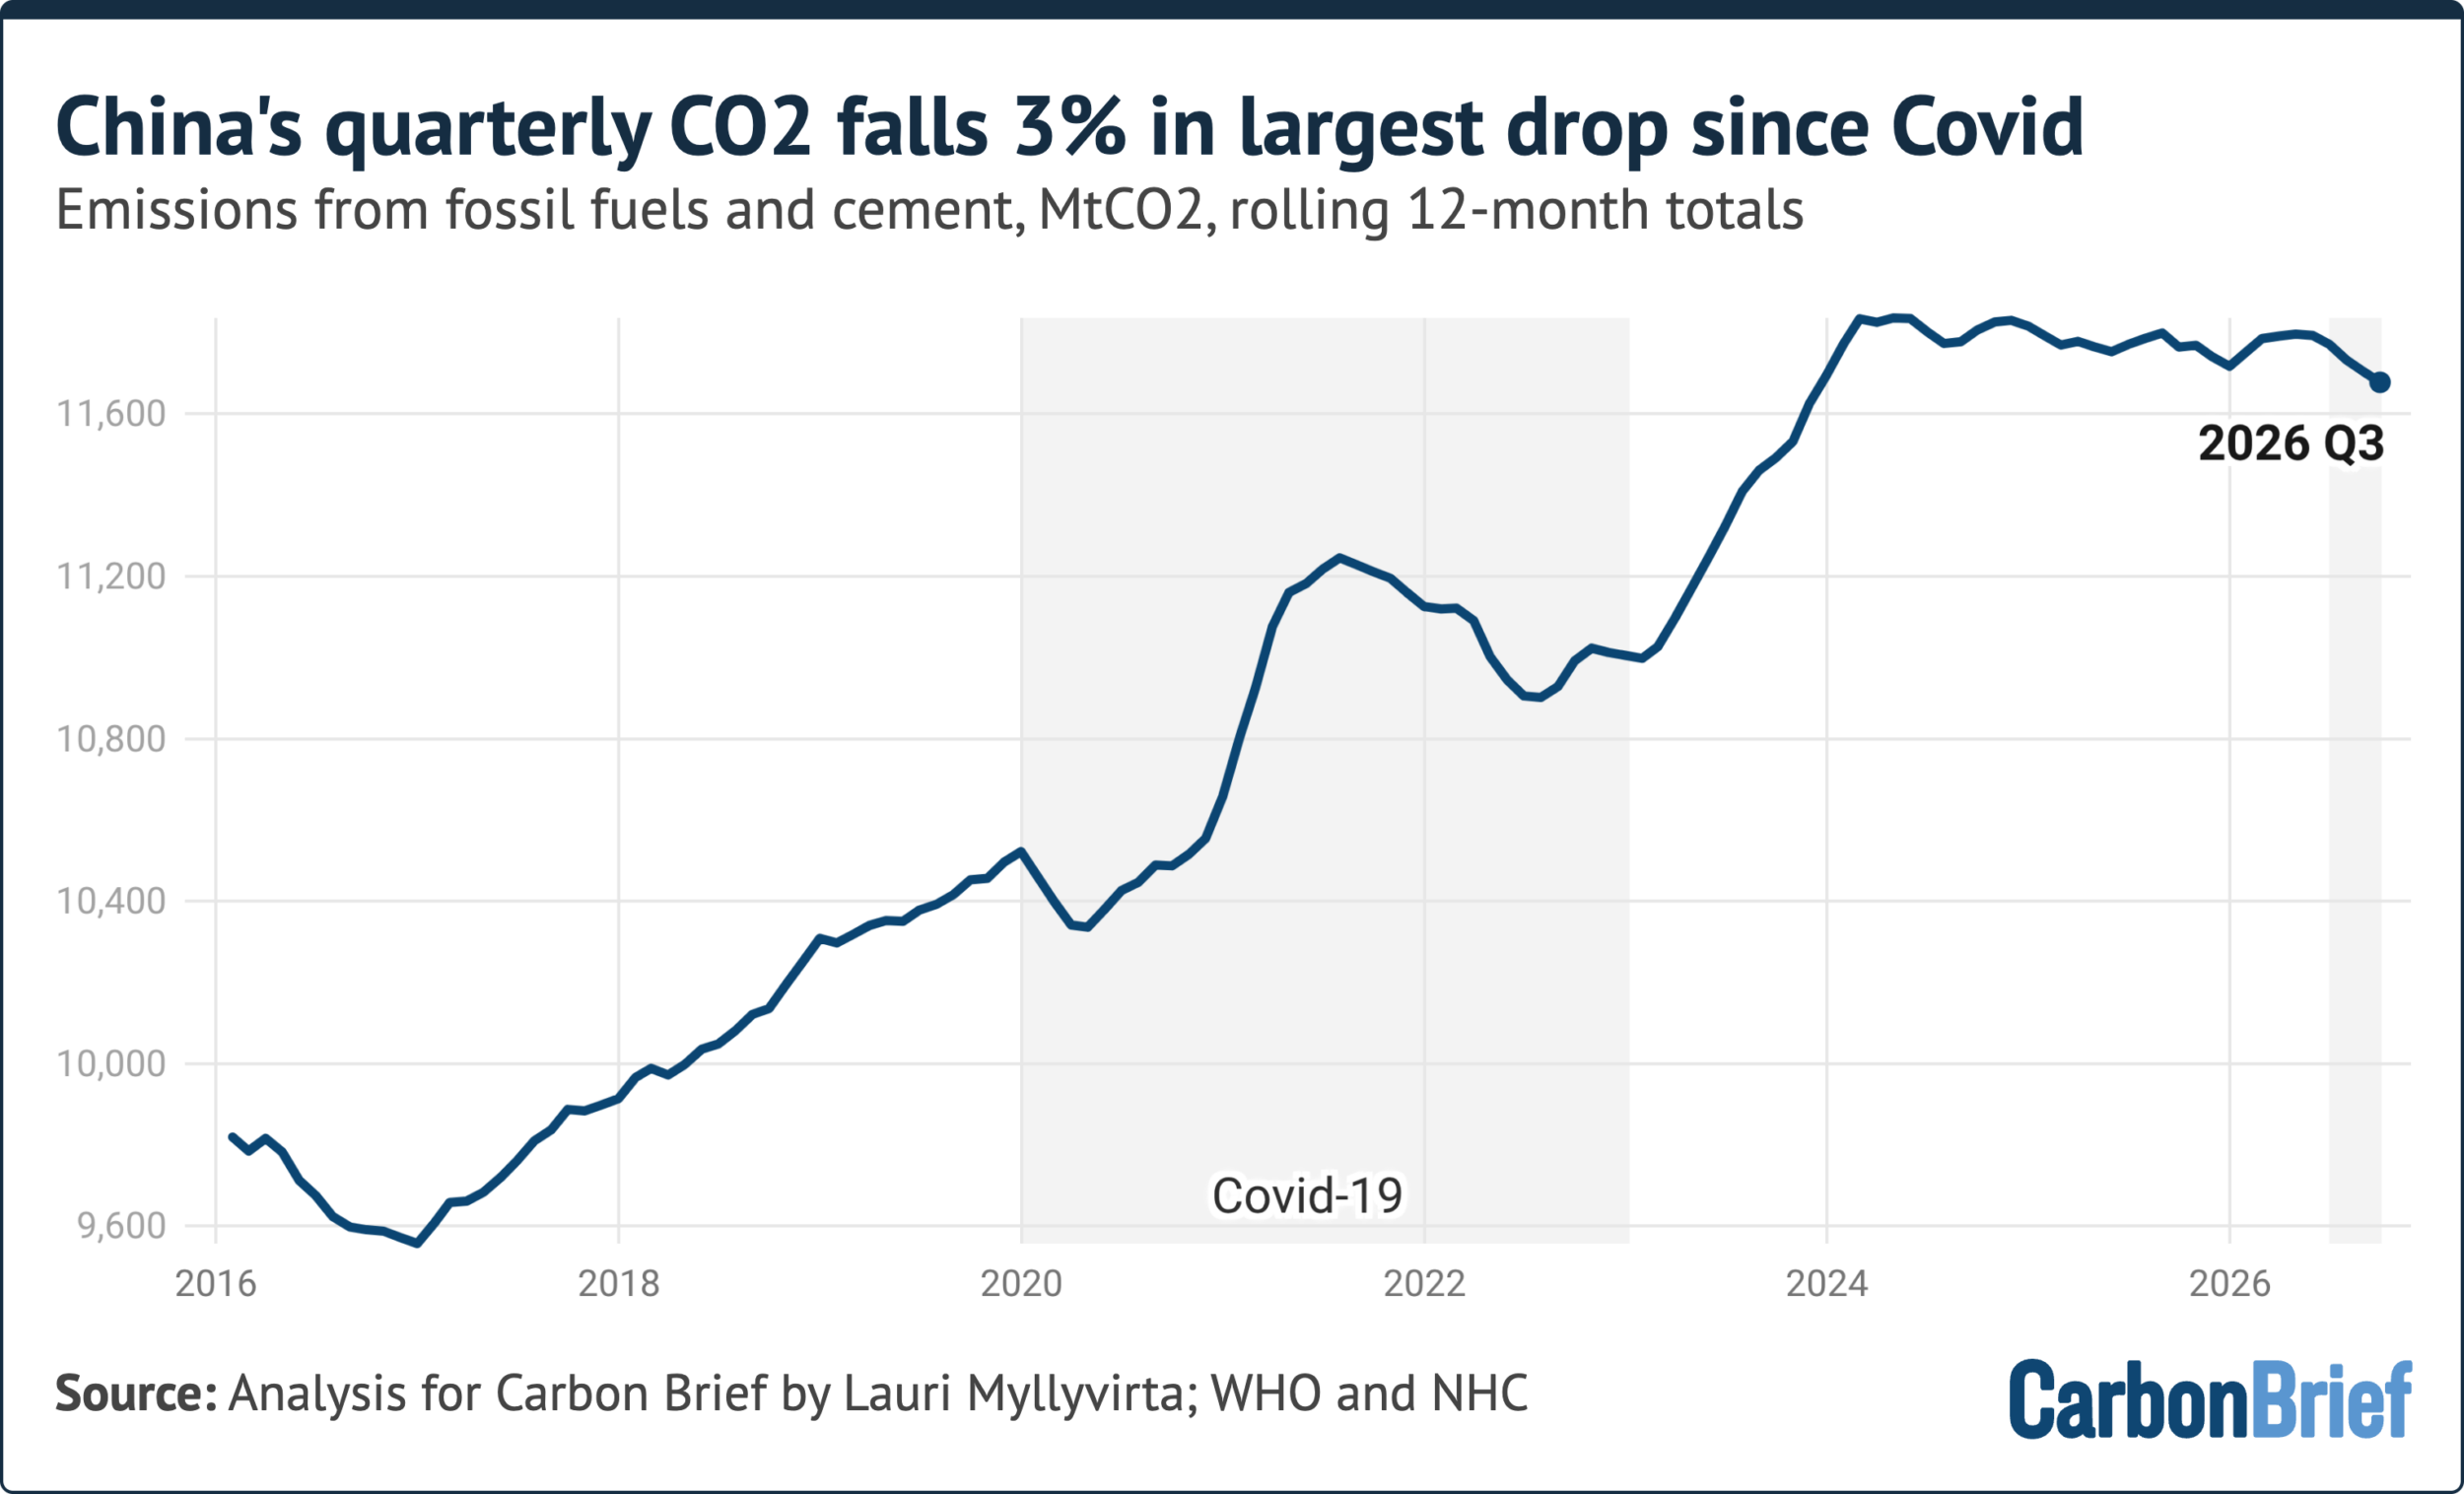
The outlook for China’s CO2 emissions depends on the balance between rising energy demand, clean-energy growth and the government response to a GDP slowdown.
Decline drivers
Key drivers of the fall in CO2 in the third quarter of 2026 included a 3.3% drop in coal-power generation, after demand growth slowed and the amount of “wasted” wind and solar fell.
Power generation from solar, wind and nuclear increased by 110 terawatt hours (TWh) year-on-year, more than twice as much as the growth in total electricity demand. This added clean-power generation equal to Germany’s total power output in the same time period.
The fall in coal-power output and CO2 emissions came despite the fact that China continues to build new coal-power capacity at near-record rates. This means that average running hours for coal plants are falling even faster than total generation, eroding their profits.
Meanwhile, transport oil consumption continued to fall sharply, down 9% year-on-year in the third quarter of 2026. Electric vehicles (EVs) continued to gain market share, hitting a record 67% of passenger car sales and 50% of heavy trucks in September.
The amount of electricity used by EVs grew by 53%, much faster than the number of EVs on the road, showing increased usage of the existing fleet in preference to fuelled vehicles.
Elsewhere, growth in the coal-to-chemical industry continued to slow down in the third quarter of 2026. The sector has been a key source of emissions growth, but high coal prices have weakened profitability and higher output prices hurt downstream demand.
Finally, CO2 emissions from cement and steel production continued to fall in the third quarter, as the contraction in construction volumes accelerated.
Outlook for emissions
Energy consumption growth has been falling after a period of exceptionally high growth during Covid, while clean-power growth has been robust.
This makes it likely that the growth in clean-power generation will exceed total energy demand growth this year, maintaining the structural fall in fossil-fuel use.
Looking ahead, this balance also relies on progress in removing barriers to new solar and wind power being added to the grid, which result in some clean electricity being “wasted”.
The recent slowdown in energy demand growth is partly – but not fully – explained by exceptionally mild weather in the third quarter.
Another key factor is weaker GDP growth. Since reported GDP growth remains within target, however, there is reduced pressure for further stimulus policies.
The focus of the economic stimulus announced to date is “six networks”, which includes the power grid and the transportation network.
These networks are highly relevant for energy and emissions – and they are already covered by policies that emphasise “green” and zero-carbon solutions.
The post Analysis: China’s quarterly CO2 falls 3% in largest drop since Covid appeared first on Carbon Brief.
Analysis: China’s quarterly CO2 falls 3% in largest drop since Covid
Climate Change
Coles, Woolworths grilled as beef buyers receive fail grade on new deforestation scorecard
MELBOURNE, Friday 6 November 2026 — As Coles holds its Annual General Meeting today, Greenpeace Australia Pacific has branded the major supermarkets with a fail grade on their commitment to source deforestation-free beef, with an updated scorecard revealing none of the major beef buyers are following through on forest sustainability commitments.
It comes after Woolworths’s AGM last week where the board copped a grilling by environmentalists and shareholders over its failed sustainability commitments. Both Coles and Woolworths committed to eliminating deforestation in their supply chains by the end of 2025, but a year past the deadline, neither company could guarantee that their beef was not sourced from deforested pastures.
From outside the Coles AGM, Adele Chasson, Nature Policy Lead at Greenpeace Australia Pacific, said:
“This is a report card Coles and Woolworths should be ashamed to take home. While all major beef buyers had promised to take deforestation off the shelves, none of them followed through. Shareholders and the public demanded answers from Woolworths last week and from Coles today, and we will continue to hold their feet to the fire on their promises.
“Beef is the leading cause of deforestation in Australia, and Coles and Woolworths keep putting off action while koalas continue losing their homes. Aussies must be able to get their groceries without having to worry if their dinner is contributing to the bulldozing of forests or driving extinction of iconic Australian animals.
“Without strong, rapid implementation plans, these companies continue with business as usual, flying in the face of Australia’s deforestation crisis. Big beef buyers like Coles and Woolworths must stop the bulldozers now, make good on their sustainability promises and play their part in stopping Australian forest destruction.”
The scorecard assesses how eight of Australia’s largest beef buyers stack up against a conversion and deforestation-free target. It charts whether the major supermarkets, Aldi, McDonalds, Hungry Jacks, Teys, Metcash/IGA and JBS are taking proper action to end Australia’s deforestation crisis. They all failed.
-ENDS-
Media contact: Kimberley Bernard on 0407 581 404 or kbernard@greenpeace.org
Coles, Woolworths grilled as beef buyers receive fail grade on new deforestation scorecard
Özgür Özel is the leader of Turkey’s main opposition “New Party” and a member of parliament from Manisa.
The world is running out of time to deliver on the Paris Agreement. The UN Environment Programme’s latest Emissions Gap Report concludes that the chance of keeping warming below 1.5C without overshooting it is gone. Even if every country delivers its current national pledges, the planet is heading for about 2.6C of warming this century.
This is the backdrop as governments and their leaders gather in Antalya for COP31, ten years after the Paris Agreement took effect. Turkey lies in the Mediterranean, one of the regions most exposed to climate change, and hosting the summit is a real opportunity.
It is also a responsibility, and that responsibility begins at home. The world does not lack targets. What it has lacked – almost everywhere – is delivery. If Antalya is remembered for anything, it should be for shifting the focus from what countries promise to what they actually do.
For many people in Turkey, the climate crisis is already part of daily life. In 2021, forests in Manavgat, a district of Antalya, burned for more than a week. Last year, wildfires forced more than 50,000 people from their homes around the western coast city of Izmir. This October, Istanbul had its heaviest rainfall in more than 80 years, with the floods killing at least eight people.
COP31 Briefing: What to expect from the Antalya climate summit?
Electrification, the fossil fuel transition, adaptation to rising impacts, climate science and trade are key themes as governments gather for COP31 in TürkiyeBrazil’s fossil fuel roadmap sketches out first global timetable
The COP30 presidency’s voluntary timetable asks countries to plan first, then build up clean energy – only turning to oil and gas supplies from 2031


Measurable outcomes
Two weeks of climate negotiations cannot deliver everything that is needed to resolve the crisis, but COP31 can push for a few things that can be measured. The first is a voluntary fossil-fuel transition roadmap, with national milestones for 2030 and 2035 reported in the same format every year.
The second is a stronger commitment to protecting forests, with progress tracked over time. The third is yearly reporting on progress towa