China’s carbon dioxide (CO2) emissions fell by 1% in the final quarter of 2025, likely securing a decline of 0.3% for the full year as a whole.
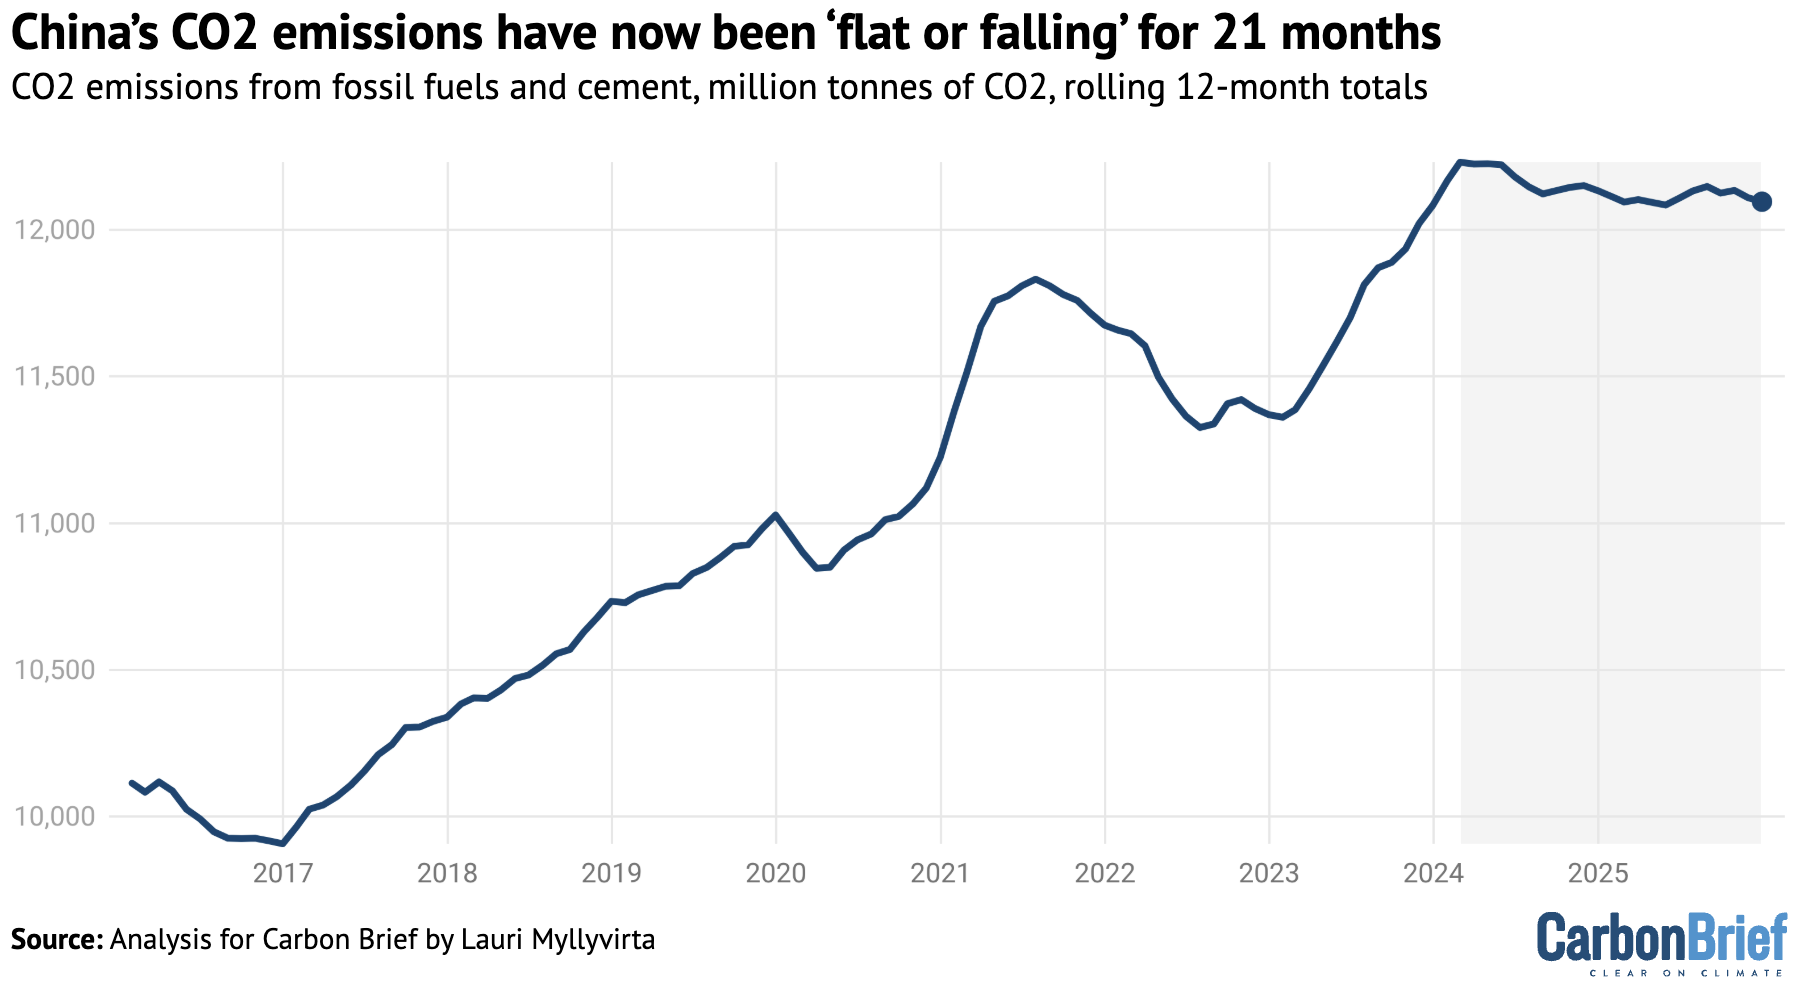
This extends a “flat or falling” trend in China’s CO2 emissions that began in March 2024 and has now lasted for nearly two years.
The new analysis for Carbon Brief shows that, in 2025, emissions from fossil fuels increased by an estimated 0.1%, but this was more than offset by a 7% decline in CO2 from cement.
Other key findings include:
- CO2 emissions fell year-on-year in almost all major sectors in 2025, including transport (3%), power (1.5%) and building materials (7%).
- The key exception was the chemicals industry, where emissions grew 12%.
- Solar power output increased by 43% year-on-year, wind by 14% and nuclear 8%, helping push down coal generation by 1.9%.
- Energy storage capacity grew by a record 75 gigawatts (GW), well ahead of the rise in peak demand of 55GW.
- This means that growth in energy storage capacity and clean-power output topped the increases in peak and total electricity demand, respectively.
The CO2 numbers imply that China’s carbon intensity – its fossil-fuel emissions per unit of GDP – fell by 4.7% in 2025 and by 12% during 2020-25.
This is well short of the 18% target set for that period by the 14th five-year plan.
Moreover, China would now need to cut its carbon intensity by around 23% over the next five years in order to meet one of its key climate commitments under the Paris Agreement.
Whether Chinese policymakers remain committed to this target is a key open question ahead of the publication of the 15th five-year plan in March.
This will help determine if China’s emissions have already passed their peak, or if they will rise once again and only peak much closer to the officially targeted date of “before 2030”.
‘Flat or falling’
The latest analysis shows China’s CO2 emissions have now been flat or falling for 21 months, starting in March 2024. This trend continued in the final quarter of 2025, when emissions fell by 1% year-on-year.
The picture continues to be finely balanced, with emissions falling in all major sectors – including transport, power, cement and metals – but rising in the chemicals industry.
This combination of factors means that emissions continue to plateau at levels slightly below the peak reached in early 2024, as shown in the figure below.
Power sector emissions fell by 1.5% year-on-year in 2025, with coal use falling 1.7% and gas use increasing 6%. Emissions from transportation fell 3% and from the production of cement and other building materials by 7%, while emissions from the metal industry fell 3%.
These declines are shown in the figure below. They were partially offset by rising coal and oil use in the chemical industry, up 15% and 10% respectively, which pushed up the sector’s CO2 emissions by 12% overall.
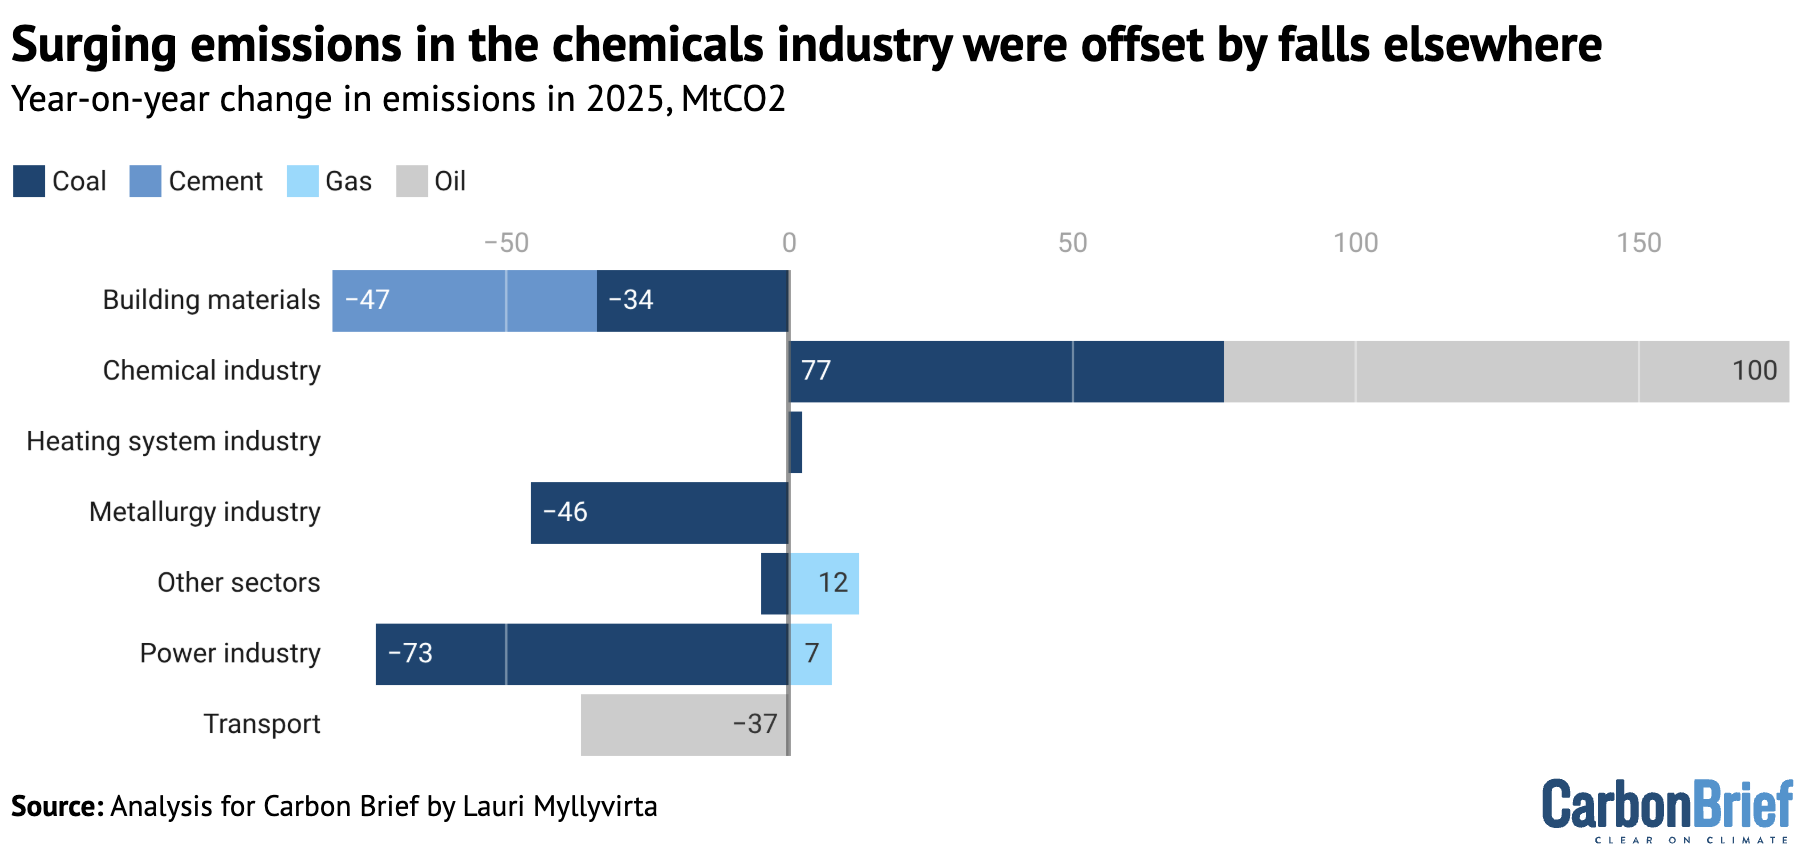
In other sectors – largely other industrial areas and building heat – gas use increased by 2%, more than offsetting the reduction in emissions from a 3% drop in their coal consumption.
Clean power covers electricity demand growth
In the power sector, which is China’s largest emitter by far, electricity demand grew by 520 terawatt hours (TWh) in 2025.
At the same time, power generation from solar increased by 43% and wind power generation by 14%, delivering 360TWh and 130TWh of additional clean electricity. Nuclear power generation grew 8%, supplying another 40TWh. The increased generation from these three sources – some 530TWh – therefore met all of the growth in demand.
Hydropower generation also increased by 3% and bioenergy by 3%, helping push power generation from fossil fuels down by 1%. Gas-fired power generation increased by 6% and, as a result, power generation from coal fell by 1.9%.
Furthermore, the surge in additions of new wind and solar capacity at the end of 2025 will only show up as increased clean-power generation in 2026.
On the other hand, the growth in solar and wind power generation has fallen short of the growth in capacity, implying a fall in capacity utilisation – a measure of actual output relative to the maximum possible. This is highly likely due to increased, unreported curtailment, where wind and solar sites are switched off because the electricity grid is congested.
If these grid issues are resolved over the next few years, then generation from existing wind and solar capacity will increase over time.
Developments in 2025 extended the trend of clean-power generation growing faster than power demand overall, as shown in the top figure below. This trend started in 2023 and is the key reason why China’s emissions have been stable or falling since early 2024.
In addition, 2025 saw another potential inflection point, shown in the bottom figure below. It was the first year ever that energy storage capacity – mainly batteries – grew faster than peak electricity demand in 2025 and faster than the average growth in the past decade.
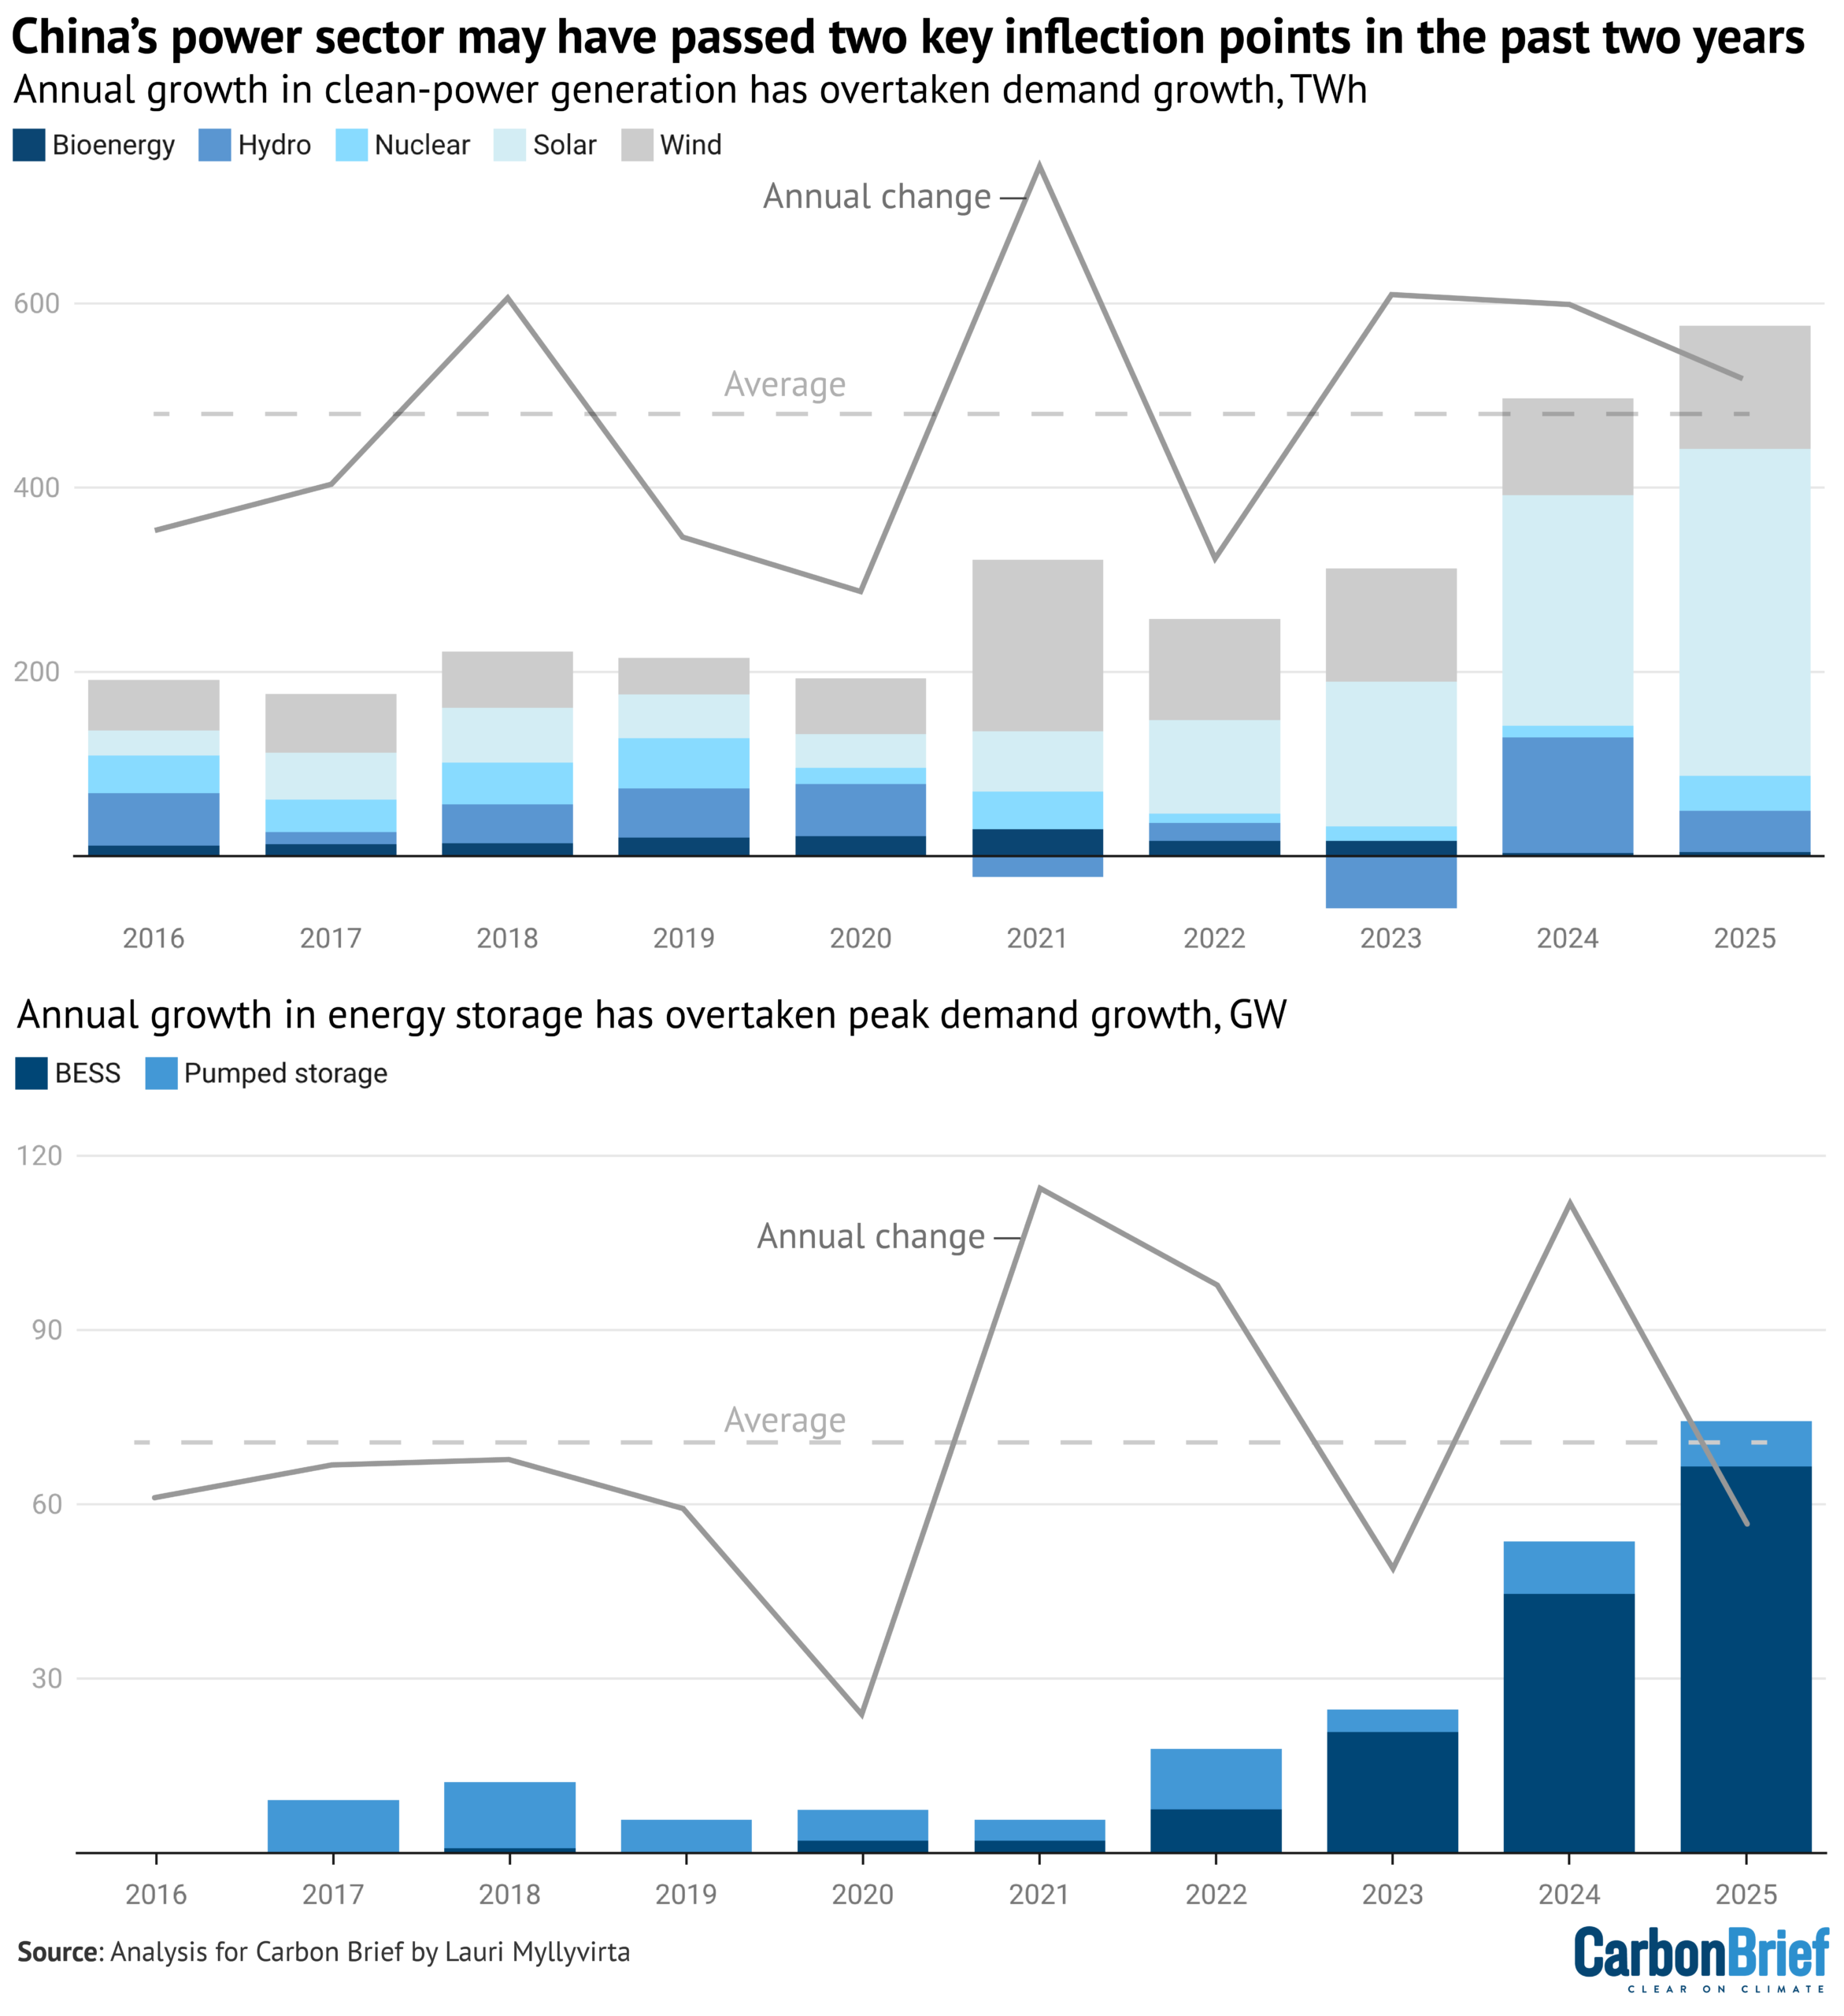
China’s energy storage capacity increased by 75GW year-on-year in 2025, while peak demand only increased by 55GW. The rise in storage capacity in 2025 is also larger than the three-year average increase in peak loads, some 72GW per year.
Peak demand growth matters, because power systems have to be designed to reliably provide enough electricity supply at the moment of highest demand.
Moreover, the increase in peak loads is a key driver of continued additions of coal and gas-fired power plants, which reached the highest level in a decade in 2025.
The growth in energy storage could provide China with an alternative way to meet peak loads without relying on increased fossil fuel-based capacity.
The growth in storage capacity is set to continue after a new policy issued by China’s top economic planner the National Development and Reform Commission (NDRC) in January.
This policy means energy storage sites will be supported by so-called “capacity payments”, which to date have only been available to coal- and gas-fired power plants and pumped hydro storage.
Concerns about having sufficient “firm” power capacity in the grid – that which can be turned on at will – led the government to promote new coal and gas-fired power projects in recent years, leading to the largest fossil-fuel based capacity additions in a decade in 2025, with another 290GW of coal-fired capacity still under construction.
Reforming the power system and increasing storage capacity would enable the grid to accommodate much higher shares of solar and wind, while reducing the need for new coal or gas capacity to meet rising peaks in demand.
This would both unlock more clean-power generation from existing capacity and improve the economics and risk profiles of new projects, stimulating more growth in capacity.
Peaking power CO2 requires more clean-energy growth
China’s key climate commitments for the next five-year period until 2030 are to peak CO2 emissions and to reduce carbon intensity by more than 65% from 2005 levels. The latter target requires limiting CO2 emissions at or below their 2025 level in 2030.
The record clean-energy additions in 2023-25 have barely sufficed to stabilise power-sector emissions, showing that if rapid growth in power demand continues, meeting the 2030 targets requires keeping clean-energy additions close to 2025 levels over the next five years.
China’s central government continues to telegraph a much lower level of ambition, with the NDRC setting a target of “around” 30% of power generation in 2030 coming from solar and wind, up from around 22% in 2025.
If electricity demand grows in line with the State Grid forecast of 5.6% per year, then limiting the share of wind and solar to 30% would leave space for fossil-fuel generation to grow at 3% per year from 2025 to 2030, even after increases from nuclear and hydropower.
Such an increase would mean missing China’s Paris commitments for 2030.
Alternatively, in order to meet the forecast increase in electricity demand without increasing generation from fossil fuels would require wind and solar’s share to reach 37% in 2030.
Similarly, China’s target of a non-fossil energy share of 25% in 2030 will not be sufficient to meet its carbon-intensity reduction commitment for 2030, unless energy demand growth slows down sharply.
This target is unlikely to be upgraded, since it is already enshrined in China’s Paris Agreement pledge, so in practice the target would need to be substantially overachieved if the country is to meet its other commitments.
If energy demand growth continues at the 2025 rate and the share of non-fossil energy only rises from 22% in 2025 to 25% in 2030, then the consumption of fossil fuels would increase by 3% per year, with a similar rise in CO2 emissions.
Still, another recent sign that clean-energy growth could keep exceeding government targets came in early February when the China Electricity Council projected solar and wind capacity additions of more than 300GW in 2026 – well beyond the government goal of “over 200GW”.
Chemical industry
The only significant source of growth in CO2 emissions in 2025 was the chemical industry, with sharp increases in the consumption of both coal and oil.
This is shown in the figure below, which illustrates how CO2 emissions appear to have peaked from cement production, transport, the power sector and others, whereas the chemicals industry is posting strong increases.

Even though chemical-industry emissions are small relative to other sectors – at roughly 13% of China’s total – the pace of expansion is creating an outsize impact.
Without the increase from the chemicals sector, China’s total CO2 emissions would have fallen by an estimated 2%, instead of the 0.3% reported here.
Without changes to policy, emission growth is set to continue, as the coal-to-chemicals industry is planning major increases in capacity.
Whether these expansion plans receive backing in the upcoming five-year plan for 2026-30 will have a major impact on China’s emission trends.
Another key factor is the development of oil and gas prices. Production in the coal-based chemical industry is only profitable when coal is significantly cheaper than crude oil.
The current coal-to-chemicals capacity in China is dominated by plants producing higher-value – and therefore less price-sensitive – chemicals such as olefins and aromatics, as feedstocks for the production of plastics.
In contrast, the planned expansion of the sector is expected to be largely driven by plants producing oil products and synthetic gas to be used for energy. For these products, electrification and clean-electricity generation provide a direct alternative, meaning they are even more sensitive to low oil and gas prices than chemicals production.
Outlook for China’s emissions
This is the latest analysis for Carbon Brief to show that China’s CO2 emissions have now been stable or falling for seven quarters or 21 months, marking the first such streak on record that has not been associated with a slowdown in energy demand growth.
Notably, while emissions have stabilised or begun a slow decline, there has not yet been a substantial reduction from the level reached in early 2024. This means that a small jump in emissions could see them exceed the previous peak level.
China’s official plans only call for peaking emissions shortly before 2030, which would allow for a rebound from the current plateau before the ultimate emissions peak.
If China is to meet its 2030 carbon intensity commitment – a 65% reduction on 2005 levels – then emissions would have to fall from the peak back to current levels by 2030.
Whether China’s policymakers are still committed to meeting this carbon intensity pledge, after the setbacks during the previous five-year period, is a key open question. The 2030 energy targets set to date have fallen short of what would be required.
The most important signal will be whether the top-level five-year plan for 2026-30, due in March, sets a carbon intensity target aligned with the 2030 Paris commitment.
Officially, China is sticking to the timeline of peaking CO2 emissions “before 2030”, which was announced by president Xi Jinping in 2020.
According to an authoritative explainer on the recommendations of the Central Committee of the Communist Party for the upcoming five-year plan, published by state-backed news agency Xinhua, coal consumption should “reach its peak and enter a plateau” from 2027.
It says that continued increases in demand for coal from electricity generators and the chemicals industry would be offset by reductions elsewhere. This is despite the fact that China’s coal consumption overall has already been falling for close to two years.
The reference to a “plateau” in coal consumption indicates that in official plans, meaningful absolute reductions in emissions would have to wait until after 2030. Any increase in coal consumption from 2025 to 2027, before the targeted plateau, would need to be offset by reductions in oil consumption, to meet the carbon intensity target.
Moreover, allowing coal consumption in the power sector to grow beyond the peak of overall coal use and emissions implies slowing down China’s clean-energy boom. So far, the boom has continued to exceed official targets by a wide margin.
In addition, the explainer’s expectation of further growth in coal use by the chemicals industry indicates a green light for at least a part of its sizable expansion plans.
The Xinhua article recognises that oil product consumption has already peaked, but says that oil use in the chemicals industry has kept growing. It adds that overall oil consumption should peak in 2026.
Elsewhere, the article speaks of “vigorously” developing non-fossil energy and “actively” developing “distributed” solar, which has slowed down due to recent pricing policies.
Yet it also calls for “high-quality development” of fossil fuels and increased efforts in domestic oil and gas production, suggesting that China continues to take an “all of the above” approach to energy policy.
The outcome of all this depends on how things turn out in reality. The past few years show it is possible that clean energy will continue to overperform its targets, preventing growth in energy consumption from fossil fuels despite this policy support.
The key role of the clean-energy boom in driving GDP growth and investments is one key motivator for policymakers to keep the boom going, even when central targets would allow for a slowdown. It is also possible that the five-year plans of provinces and state-owned enterprises could play a key role in raising ambition, as they did in 2022.
About the data
Data for the analysis was compiled from the National Bureau of Statistics of China, National Energy Administration of China, China Electricity Council and China Customs official data releases, as well as from industry data provider WIND Information and from Sinopec, China’s largest oil refiner.
Electricity generation from wind and solar, along with thermal power breakdown by fuel, was calculated by multiplying power generating capacity at the end of each month by monthly utilisation, using data reported by China Electricity Council through Wind Financial Terminal.
Total generation from thermal power and generation from hydropower and nuclear power were taken from National Bureau of Statistics monthly releases.
Monthly utilisation data was not available for biomass, so the annual average of 52% for 2023 was applied. Power-sector coal consumption was estimated based on power generation from coal and the average heat rate of coal-fired power plants during each month, to avoid the issue with official coal consumption numbers affecting recent data.
CO2 emissions estimates are based on National Bureau of Statistics default calorific values of fuels and emissions factors from China’s latest national greenhouse gas emissions inventory, for the year 2021. The CO2 emissions factor for cement is based on annual estimates up to 2024.
For oil, apparent consumption of transport fuels – diesel, petrol and jet fuel – is taken from Sinopec quarterly results, with monthly disaggregation based on production minus net exports. The consumption of these three fuels is labeled as oil product consumption in transportation, as it is the dominant sector for their use.
Apparent consumption of other oil products is calculated from refinery throughput, with the production of the transport fuels and the net exports of other oil products subtracted. Fossil-fuel consumption includes non-energy use such as plastics, as most products are short-lived and incineration is the dominant disposal method.

The post Analysis: China’s CO2 emissions have now been ‘flat or falling’ for 21 months appeared first on Carbon Brief.
Analysis: China’s CO2 emissions have now been ‘flat or falling’ for 21 months

Drought and heatwaves occurring together – known as “compound” events – have “surged” across the world since the early 2000s, a new study shows.
Compound drought and heat events (CDHEs) can have devastating effects, creating the ideal conditions for intense wildfires, such as Australia’s “Black Summer” of 2019-20 where bushfires burned 24m hectares and killed 33 people.
The research, published in Science Advances, finds that the increase in CDHEs is predominantly being driven by events that start with a heatwave.
The global area affected by such “heatwave-led” compound events has more than doubled between 1980-2001 and 2002-23, the study says.
The rapid increase in these events over the last 23 years cannot be explained solely by global warming, the authors note.
Since the late 1990s, feedbacks between the land and the atmosphere have become stronger, making heatwaves more likely to trigger drought conditions, they explain.
One of the study authors tells Carbon Brief that societies must pay greater attention to compound events, which can “cause severe impacts on ecosystems, agriculture and society”.
Compound events
CDHEs are extreme weather events where drought and heatwave conditions occur simultaneously – or shortly after each other – in the same region.
These events are often triggered by large-scale weather patterns, such as “blocking” highs, which can produce “prolonged” hot and dry conditions, according to the study.
Prof Sang-Wook Yeh is one of the study authors and a professor at the Ewha Womans University in South Korea. He tells Carbon Brief:
“When heatwaves and droughts occur together, the two hazards reinforce each other through land-atmosphere interactions. This amplifies surface heating and soil moisture deficits, making compound events more intense and damaging than single hazards.”
CDHEs can begin with either a heatwave or a drought.
The sequence of these extremes is important, the study says, as they have different drivers and impacts.
For example, in a CDHE where the heatwave was the precursor, increased direct sunshine causes more moisture loss from soils and plants, leading to a drought.
Conversely, in an event where the drought was the precursor, the lack of soil moisture means that less of the sun’s energy goes into evaporation and more goes into warming the Earth’s surface. This produces favourable conditions for heatwaves.
The study shows that the majority of CDHEs globally start out as a drought.
In recent years, there has been increasing focus on these events due to the devastating impact they have on agriculture, ecosystems and public health.
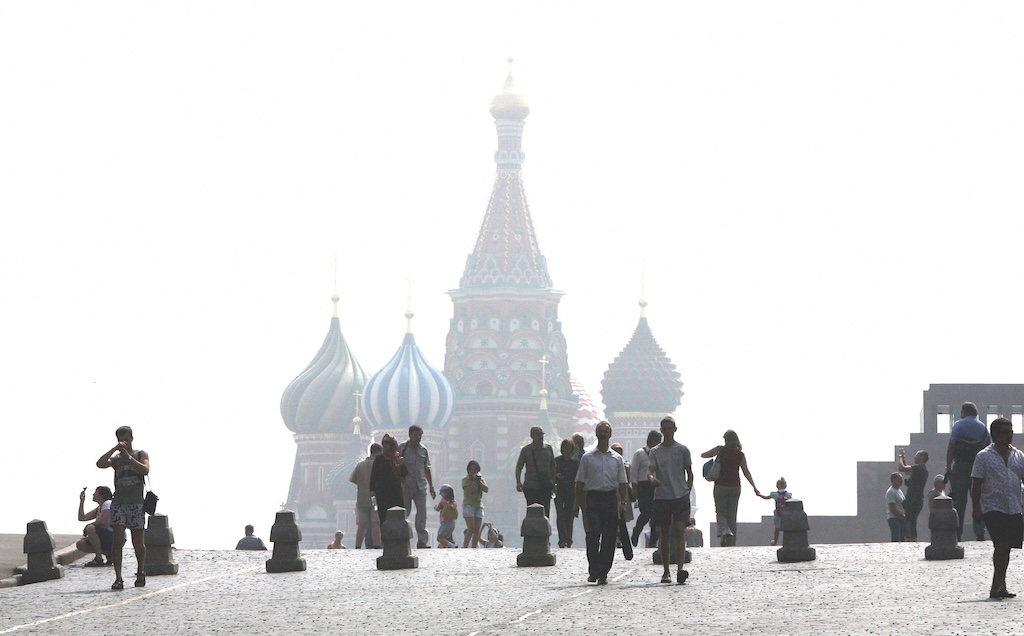
In Russia in the summer of 2010, a compound drought-heatwave event – and the associated wildfires – caused the death of nearly 55,000 people, the study notes.
The record-breaking Pacific north-west “heat dome” in 2021 triggered extreme drought conditions that caused “significant declines” in wheat yields, as well as in barley, canola and fruit production in British Columbia and Alberta, Canada, says the study.
Increasing events
To assess how CDHEs are changing, the researchers use daily reanalysis data to identify droughts and heatwaves events. (Reanalysis data combines past observations with climate models to create a historical climate record.) Then, using an algorithm, they analyse how these events overlap in both time and space.
The study covers the period from 1980 to 2023 and the world’s land surface, excluding polar regions where CDHEs are rare.
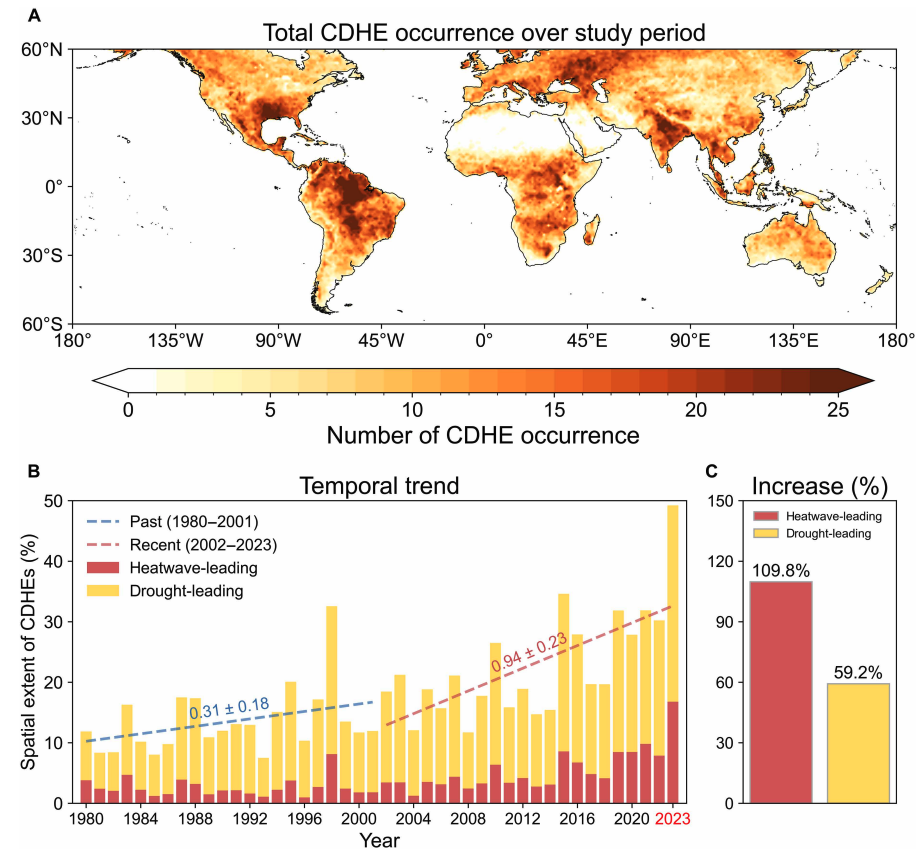
The research finds that the area of land affected by CDHEs has “increased substantially” since the early 2000s.
Heatwave-led events have been the main contributor to this increase, the study says, with their spatial extent rising 110% between 1980-2001 and 2002-23, compared to a 59% increase for drought-led events.
The map below shows the global distribution of CDHEs over 1980-2023. The charts show the percentage of the land surface affected by a heatwave-led CDHE (red) or a drought-led CDHE (yellow) in a given year (left) and relative increase in each CDHE type (right).
The study finds that CDHEs have occurred most frequently in northern South America, the southern US, eastern Europe, central Africa and south Asia.
Threshold passed
The authors explain that the increase in heatwave-led CDHEs is related to rising global temperatures, but that this does not tell the whole story.
In the earlier 22-year period of 1980-2001, the study finds that the spatial extent of heatwave-led CDHEs rises by 1.6% per 1C of global temperature rise. For the more-recent period of 2022-23, this increases “nearly eightfold” to 13.1%.
The change suggests that the rapid increase in the heatwave-led CDHEs occurred after the global average temperature “surpasse[d] a certain temperature threshold”, the paper says.
This threshold is an absolute global average temperature of 14.3C, the authors estimate (based on an 11-year average), which the world passed around the year 2000.
Investigating the recent surge in heatwave-leading CDHEs further, the researchers find a “regime shift” in land-atmosphere dynamics “toward a persistently intensified state after the late 1990s”.
In other words, the way that drier soils drive higher surface temperatures, and vice versa, is becoming stronger, resulting in more heatwave-led compound events.
Daily data
The research has some advantages over other previous studies, Yeh says. For instance, the new work uses daily estimations of CDHEs, compared to monthly data used in past research. This is “important for capturing the detailed occurrence” of these events, says Yeh.
He adds that another advantage of their study is that it distinguishes the sequence of droughts and heatwaves, which allows them to “better understand the differences” in the characteristics of CDHEs.
Dr Meryem Tanarhte is a climate scientist at the University Hassan II in Morocco, and Dr Ruth Cerezo Mota is a climatologist and a researcher at the National Autonomous University of Mexico. Both scientists, who were not involved in the study, agree that the daily estimations give a clearer picture of how CDHEs are changing.
Cerezo-Mota adds that another major contribution of the study is its global focus. She tells Carbon Brief that in some regions, such as Mexico and Africa, there is a lack of studies on CDHEs:
“Not because the events do not occur, but perhaps because [these regions] do not have all the data or the expertise to do so.”
However, she notes that the reanalysis data used by the study does have limitations with how it represents rainfall in some parts of the world.
Compound impacts
The study notes that if CDHEs continue to intensify – particularly events where heatwaves are the precursors – they could drive declining crop productivity, increased wildfire frequency and severe public health crises.
These impacts could be “much more rapid and severe as global warming continues”, Yeh tells Carbon Brief.
Tanarhte notes that these events can be forecasted up to 10 days ahead in many regions. Furthermore, she says, the strongest impacts can be prevented “through preparedness and adaptation”, including through “water management for agriculture, heatwave mitigation measures and wildfire mitigation”.
The study recommends reassessing current risk management strategies for these compound events. It also suggests incorporating the sequences of drought and heatwaves into compound event analysis frameworks “to enhance climate risk management”.
Cerezo-Mota says that it is clear that the world needs to be prepared for the increased occurrence of these events. She tells Carbon Brief:
“These [risk assessments and strategies] need to be carried out at the local level to understand the complexities of each region.”