

The number of new coal-fired power plants built around the world hit a “10-year high” in 2025, even as the global coal fleet generated less electricity, amid a “widening disconnect” in the sector.
That is according to the latest annual report from Global Energy Monitor (GEM), which finds that the world added nearly 100 gigawatts (GW) of new coal-power capacity in 2025, the equivalent of roughly 100 large coal plants.
It adds that 95% of the new coal plants were built in India and China.
Yet GEM says that the amount of electricity generated with coal fell by 0.6% in 2025 – with sharp drops in both China and India – as the fuel was displaced by record wind and solar output, among other factors.
The report notes that there have been previous dips in output from coal power and there could still be ups – as well as downs – in the near term.
For example, nearly 70% of the coal-fired units scheduled to retire globally in 2025 did not do so, due to postponements triggered by the 2022 energy crisis and policy shifts in the US.
However, GEM says that the underlying dynamics for coal power have now fundamentally shifted, as the cost of renewables has fallen and low usage hits coal profitability.
China and India dominate growth
In 2025, coal-capacity growth hit a 10-year high, with 97 gigawatts (GW) of new power plants being added, according to GEM.
(Capacity refers to the potential maximum power output, as measured in GW, whereas generation refers to power actually generated by the assets over a period of time, measured in gigawatt hours, GWh.)
This is the highest level since 2015 when 107GW began operating, as shown in the chart below. This makes 2025 the second-highest level of additions on record.
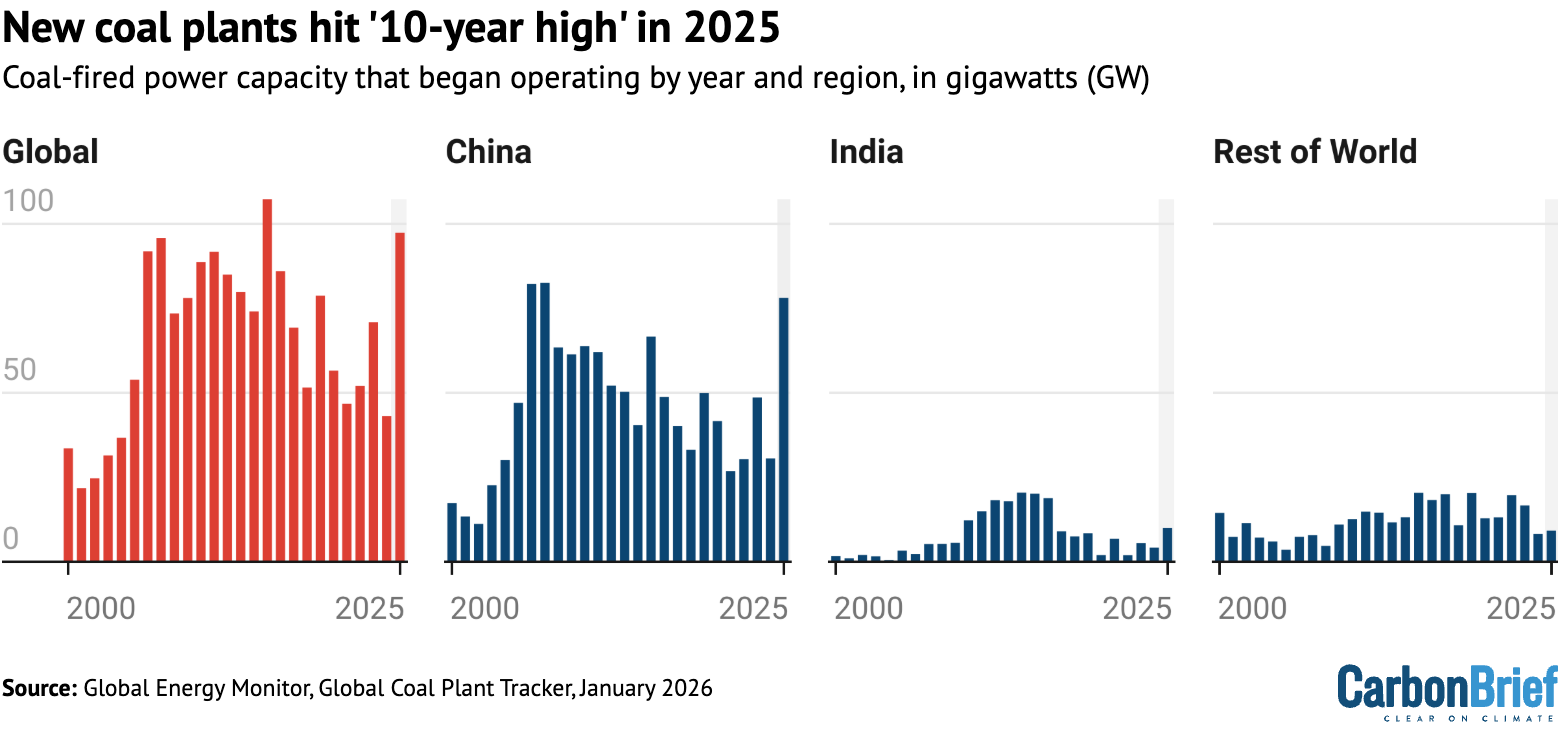
The majority of this growth came from China and India, which added 78GW and 10GW, respectively, against 9GW from all other countries.
Yet GEM points out that, even as coal capacity in China grew by 6%, the output from coal-fired power plants actually fell 1.2%. This means that each power plant would have been running less often, eroding its profitability. Similarly, capacity in India grew by 3.8%, while generation fell by 2.9%.
China and India had accounted for 87% of new coal-power capacity that came into operation in the first half of 2025. The shift up to 95% in the year as a whole highlights how increasingly just those two countries dominate the sector, GEM says.
Christine Shearer, project manager of GEM’s global coal plant tracker, said in a statement:
“In 2025, the world built more coal and used it less. Development has grown more concentrated, too – 95% of coal plant construction is now in China and India, and even they are building solar and wind fast enough to displace it.”
Both China and India saw solar and wind meet most or all of the growth in electricity demand last year.
Analysis for Carbon Brief last year showed that, in the first six months of 2025 alone, a record 212GW of solar was added in China, helping to make it the nation’s single-largest source of clean-power generation, for example.
However, the country continues to propose new coal plants. In 2025, a record 162GW of capacity was newly proposed for development or reactivated, according to GEM. This brought the overall capacity under development in the country to more than 500GW.
China’s 15th “five-year plan”, covering 2026-2030, had pledged to “promote the peaking” of coal use, while a more recent pair of policies introduced stricter controls on local governments’ coal use.
For its part, in India some 28GW of new coal capacity was newly proposed or reactivated last year, bringing the total under development to 107.3GW and under-construction capacity to 23.5GW.
The Indian government is planning to complete 85GW of new coal capacity in the next seven years, even as clean-energy expansion reaches levels that could cover all of the growth in electricity demand.
Outside of China and India, GEM says that just 32 countries have new coal plants under construction or under development, down from 38 in 2024.
Countries that have dropped plans for new coal in 2025 include South Korea, Brazil and Honduras, it says. GEM notes that the latter two mean that Latin America is now free from any new coal-power proposals.
This means that both electricity generation from coal and the construction of new coal-fired power plants are increasingly concentrated in just a few countries, as the chart below shows.
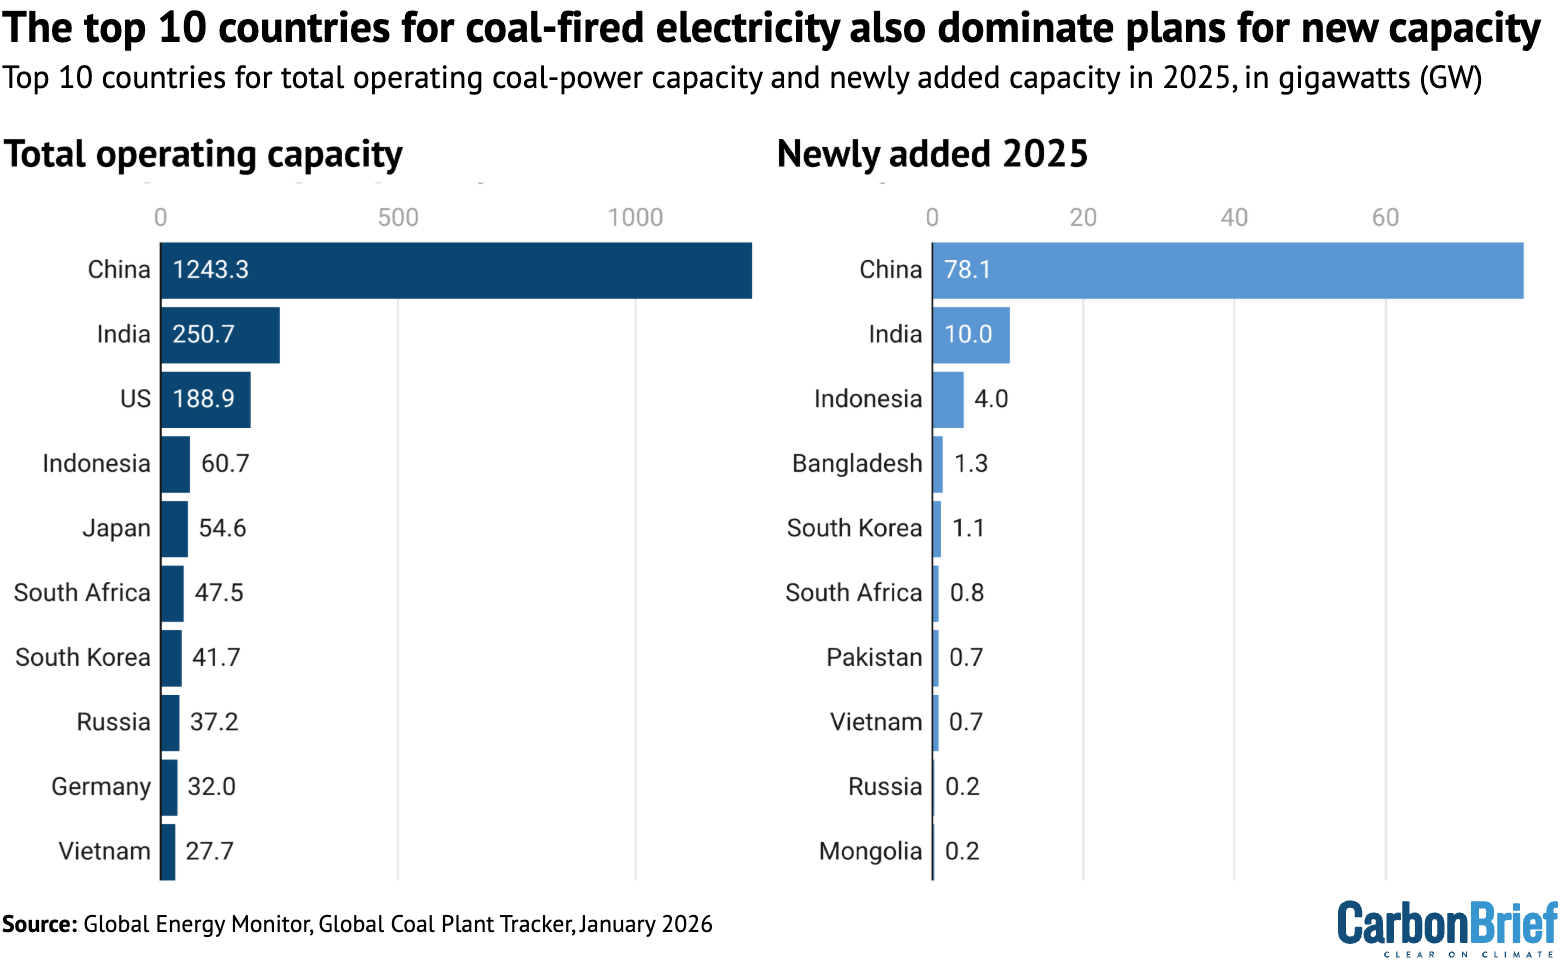
Indonesia’s coal fleet grew by 7% in 2025 to 61GW, with a quarter of the new capacity tied to nickel and aluminium processing, according to GEM.
Turkey – which is gearing up to host the COP31 international climate summit in November – has just one coal-plant proposal remaining, down from 70 in 2015.
The amount of new coal capacity that started to operate in south-east Asia fell for the third year in a row in 2025, according to GEM.
Countries in south Asia that rely on imported energy are increasingly looking to other technologies to protect themselves from fossil-fuel shocks, such as Pakistan, which is rapidly deploying solar, states the GEM report.
In Africa, plans for new coal capacity are concentrated in Zimbabwe and Zambia, the report shows, with the two countries accounting for two-thirds of planned development in the region.
‘Persistence of policies’
While new coal plants are still being built and even more are under development, GEM notes that the global electricity system is undergoing rapid changes.
Crucially, the growth of cheap renewable energy means that new coal plants do not automatically translate into higher electricity generation from coal.
Without rising output from coal power, building new plants simply results in the coal fleet running less often, further eroding its economics relative to wind and solar power.
Indeed, GEM notes that electricity generation from coal fell globally in 2025. Moreover, a recent report by thinktank Ember found that renewable energy overtook coal in 2025 to become the world’s largest source of electricity.
GEM notes that coal generation may fluctuate in the near term, in particular due to potential increases in demand driven by higher gas prices.
It adds that gas price shocks, such as the one triggered by the Iran war, can cause temporary reversals in the longer-term shift away from coal.
According to Carbon Brief analysis, at least eight countries announced plans to either increase their coal use or review plans to transition away from coal in the first month of the Iran war. However, a much-discussed “return to coal” is expected to be limited.
GEM’s report highlights that global fossil-fuel shocks can have an impact on the phase out of coal capacity over several years.
In the EU, for example, 69% of planned retirements did not take place in 2025, due to postponements that began in the 2022-23 energy crisis triggered by the Russian invasion of Ukraine, according to the report. Countries across the bloc chose to retain their coal capacity amid gas supply disruptions and concerns about energy security.
Yet coal-fired power generation in the bloc is now more than 40% below 2022 levels. Again, this highlights that coal capacity does not necessarily translate into electricity generation from coal, with its associated CO2 emissions.
Overall, GEM notes that “repeated exposure to fossil-fuel price volatility is as likely to accelerate the shift toward clean energy as it is to delay it”.
GEM’s Shearer says in a statement:
“The central challenge heading into 2026 is not the availability of alternatives, but the persistence of policies that treat coal as necessary even as power systems move increasingly beyond it.”
In the US, 59% of planned retirements in 2025 did not happen, according to GEM. This was due to government intervention to keep ageing coal plants online.
Five coal-power plants have been told to remain online through federal “emergency” orders, for example, even as the coal fleet continues to face declining competitiveness.
Keeping these plants online has cost hundreds of millions of dollars and helped drive an annual increase in the average US household electricity prices of 7%, according to GEM.
Despite such measures, Trump has overseen a larger fall in coal-fired power capacity than any other US president, according to Carbon Brief analysis.
Meanwhile, according to new figures from the US Energy Information Administration, solar and wind both set new records for energy production in 2025.
Despite challenges with policy and wider fossil-fuel impacts, the underlying dynamic has shifted, says GEM, as “clean energy becomes more competitive and widely deployed” around the world.
It adds that this raises the prospect of “a more sustained decoupling between coal-capacity growth and generation, particularly if clean-energy deployment continues at current rates”.
The post New coal plants hit ‘10-year’ global high in 2025 – but power output still fell appeared first on Carbon Brief.
New coal plants hit ‘10-year’ global high in 2025 – but power output still fell

Elisa Morgera is the UN Special Rapporteur on Climate Change and Human Rights.
For years, governments and international financial institutions have justified the mining boom by arguing that the energy transition cannot happen without critical minerals.
Increasingly, however, they are securing those minerals for something else: weapons and artificial intelligence (AI).
At COP31, governments must make clear what a sustainable and fair energy transition requires and reject demand for minerals that fuels war and other climate-harming uses.
Independent research shows that mineral demand is increasingly driven by AI and militarisation. Yet, both undermine climate action.
Major armed conflicts are linked to fossil fuel expansion, generate emissions that are unaccounted for under the Paris Agreement, and deliver record profits to fossil fuel and petrochemical companies through price spikes and disrupted access to fuel and food.
Meanwhile, AI infrastructure risks undoing the progress of the renewable energy transition by driving fossil fuel expansion to meet data centres’ vast new energy demand.
-
We need no-go mining zones for the energy transition to be just: Here’s how it could work
As rising demand for critical minerals is compounding threats to fragile ecosystems, NGOs have mapped out areas that should be off-limits to mining -
Rush for critical minerals tests Europe’s resolve to protect nature
A Climate Home News investigation found that more than half of the EU’s “strategic” mineral projects lie on, or within a kilometre, of protected Natura 2000 sites -
Major financiers neglect energy transition risks from mining as demand booms
Financial institutions are lacking safeguards to prevent harms caused by mining the resources needed for the energy transition, analysis of the sector’s financing finds


UN Secretary-General António Guterres and the head of UN Climate Change Simon Stiell have both warned of the climate harm of unchecked, fossil fuel-powered AI and data centre growth.
In addition, AI equipment and infrastructure require huge amounts of copper – one of the minerals most in demand for the energy transition. A recent academic study found that copper makes up roughly 82-83% of the mineral mass in data centres.
None of this demand serves the energy transition. Instead, the climate case for mining is being used to legitimise uses that undermine a sustainable future.
Mining still relies heavily on fossil fuels and often harms the environment, so it must be limited to extracting the resources strictly necessary for the energy transition. Otherwise, states breach their binding obligations to protect the environment and human rights, as the International Court of Justice (ICJ) has made clear.
National security is the new mining fast track
Campaigners have long warned that when minerals become a matter of national security, governments are more tempted to deregulate and fast-track mining projects. Communities pay the price.
Extraction without adequate consultation is a global pattern linked to killings of land and environmental defenders. More than half of transition mineral projects are located on or near Indigenous lands, and allegations of abuses linked to mining transition minerals surged 73% in 2025 alone.
Security and climate are not separate problems. Both are rooted in the fossil fuel-based global economy, now joined by the unchecked growth of AI and data centres.
Who should benefit from minerals?
Not every demand for minerals can or should be met. Minerals are finite and must be used to address the worsening climate crisis as a priority.
The COP31 presidency’s push for electrification will have significant implications for mineral demand. At the same time, electrification doesn’t necessarily help to phase out fossil fuels. Governments must be clear about how minerals are being used and prioritise uses that genuinely advance the energy transition.
- Climate action comes first: Mineral demand for the wind and solar projects that power communities and essential public services such as local food systems should be met first. Priority uses should include community-led wind and solar projects and renewable power for public transport.
- No support for climate-harming activities: Mineral demand projections for the energy transition should exclude the military-industrial complex and data centres, and governments should reconsider public spending on militarisation. Mineral demand for electrification should also be scrutinised to avoid deepening fossil fuel dependence.
- Cut demand before expanding supply: High-consuming countries should use less primary material through efficiency, longer-lasting products and by reducing car dependence, rather than exporting waste and harm to the Global South.
- Prioritise energy needs: Those without access to energy must be served first. Overproduction and overconsumption must be curbed, otherwise the transition will neither mitigate climate change nor reduce poverty.
- No mining without consent: No project should receive financing or permits without the Free, Prior and Informed Consent of Indigenous Peoples and genuine consultations with affected communities.
- No-go zones: States should establish no-go mining zones in ecologically sensitive areas, on land and at sea, and ensure that mining does not cause significant harm to biodiversity.
What can COP31 do?
Last year, governments agreed to develop a Just Transition Mechanism, but explicit provisions on transition mineral governance were dropped. At COP31, negotiators are reconsidering the issue. I urge negotiators in Antalya to:
- Reflect states’ obligations underpinning the ICJ Advisory Opinion and the UN Secretary-General’s Critical Energy Transition Minerals Panel principles in the Just Transition Work Programme.
- Keep mineral demand for the military and digital infrastructure separate from demand that serves climate protection.
- Require traceability and end-use disclosure, so it is publicly known whether a mineral ends up in a battery, a missile or a data centre.
- Respect the human rights of Indigenous Peoples, peasants and environmental human rights defenders, including the right to say no, protection from reprisals and access to remedy.
At COP31, transition minerals should be unequivocally linked to everyone’s human right to a safe climate and a healthy environment.
The post Minerals for the planet or for war and AI? COP31 must make clear what we prioritise appeared first on Climate Home News.
Minerals for the planet or for war and AI? COP31 must make clear what we prioritise
Dozens of countries – from big emerging economies to the world’s poorest nations – are calling for the UN’s new carbon market to reassess climate integrity rules, in a push that campaigners and researchers have blamed on industry lobbying.
At COP31 talks on the Paris Agreement Crediting Mechanism (PACM) this weekend, the Like-Minded Developing Countries – a group that includes Saudi Arabia, India and China – the Least Developed Countries (LDCs) and landlocked developing countries raised concerns about the requirements project developers must meet, according to sources familiar with the closed-door discussions.
They warned about the cumulative weight of those requirements developed under Article 6 of the Paris Agreement as barriers to implementation. Several countries, including Singapore and some Latin American states, said rules must keep projects financially viable, while South Korea asked for proportionate requirements, the sources said.
Their demands closely track arguments from carbon market industry groups, which claim PACM’s conservative approach to counting emission reductions is so strict that few projects will ever come to fruition.
Industry and NGOs lobby to weaken UN carbon credit rules in “coordinated” push
In a letter published ahead of COP31, the lobby groups asked governments to “raise implementation concerns” and to request that the Supervisory Body – the UN body that oversees the market – assess the “combined impact” of its rules on the feasibility of projects.
The letter was signed by the International Emissions Trading Association (IETA), a business group whose members include fossil fuel giants Shell, BP, Saudi Aramco and Chevron, along with the Project Developer Forum and the Wildlife Conservation Society, which develops forest conservation programmes.
Draft text reflects industry demands
Those demands are reflected in the first draft of the COP31 decision on the mechanism, published late on Saturday. To guard against over-crediting, PACM’s rules deliberately err on the side of issuing fewer credits when emissions cuts from projects are uncertain.
The document asks the Supervisory Body to look at how these cautious assumptions add up across its rules and what that means for the number of credits, project costs and prices. The aim, it says, is to avoid “excessive compounding of conservative adjustments”.
Other parts of the draft tell the body not to make its rules too cautious or too rigid. That includes efforts to guard against the risk that carbon captured by a project is later released. Most of these passages add that environmental integrity must be maintained.
Risk of another ‘failure’
“Weakening the rules is not climate ambition – it is a license to pollute,” said Erika Lennon, a senior attorney at the Center for International Environmental Law (CIEL). “As we are on the brink of permanently breaching 1.5C, we cannot afford to turn the carbon market into another loophole for polluters,” she added.
Axel Michaelowa, research director at Perspectives Climate Research, said that if attempts to weaken the rules succeed, it could lead to another failure of an international carbon market. Demand for credits rests on trust, he said, and the slightest doubt over integrity erodes buyers’ willingness to pay.
Calls to revise requirements “must be supported by scientific evidence, not unsupported claims of under-crediting – especially when these assumptions come from private actors whose revenues depend on the volume of transacted credits rather than real mitigation outcomes,” Michaelowa said.
The EU, Switzerland and Senegal are among a handful of countries pushing back against demands to re-assess the market rules, according to the sources, and are opposing requests to weigh up the profitability of projects or to lower standards.
