
Article Contents

China’s exports in 2026 of clean-energy technologies, such as solar panels, batteries and electric vehicles, are on track to cut emissions beyond its borders by 2%, reveals new analysis.
This guest post is by:
Lauri Myllyvirta, lead analyst at the Centre for Research on Energy and Clean Air and senior fellow at Asia Society Policy Institute
The impact of these Chinese exports on carbon dioxide (CO2) emissions around the world grew by 26% year-on-year in the first three quarters of 2026, having already risen by 36% in 2025.
The new analysis for Carbon Brief is based on detailed data for clean-tech product exports, the electricity system in destination countries and emissions during manufacturing in China.
If the latest trends continue for the rest of the year, then Chinese clean-tech exports in 2026 alone will avoid around 450m tonnes of CO2 (MtCO2) – roughly equivalent to Brazil’s annual emissions.
Other key findings from the analysis include:
- Electric car and heavy vehicle shipments grew by 61% year-on-year in the first three quarters of 2026, wind-turbines by 45%, batteries 39%, solar 22% and electric two-wheelers by 21%.
- Over the lifetime of the equipment, exports in 2026 are on track to avoid 8,400MtCO2, equivalent to the annual emissions of the US and India combined.
- This lifetime avoided emissions total for exports in 2026 is up by a quarter from 6,800MtCO2 in 2025 and up by two-thirds from 5,000MtCO2 in 2024.
- Wind- and solar-equipment exports from China in 2026 will generate as much electricity each year as roughly 100 coal-fired power plants.
- While the majority of clean-tech exports by value went to the global north in the first three quarters of 2026, some 76% of lifetime avoided emissions were in the global south.
- This includes 52% of lifetime avoided emissions being in south and south-east Asia, reflecting solar shipments from China being installed onto high-carbon power grids.
- Chinese-owned clean-energy projects built in other countries doubled from 2022-25, but the amount of CO2 avoided remains small compared to equipment exports.
The analysis shows that most of China’s clean-energy exports have been built on new or expanded markets, enabling other producers to maintain their own sales volumes.
In addition, clean-energy sales within China are larger than exports for most technologies, but a domestic solar slowdown could exacerbate trade tensions, if it continues.
Clean-tech exports
China has become the pre-eminent producer of clean-energy technologies, from solar panels and wind turbines through to batteries and electric vehicles.
The majority of China’s clean-tech production is destined for the domestic market. But it has also become a major exporter – and these exports are avoiding significant amounts of CO2.
Previous analysis for Carbon Brief showed that these clean-energy exports in 2024 would cut emissions in countries outside China by around 1%.
The latest analysis shows that China’s clean-tech exports in 2026 are on track to avoid around 450MtCO2, as shown in the figure below, which is nearly 2% of global emissions outside China. It is also roughly equivalent to Brazil’s annual CO2 emissions from fossil fuels.
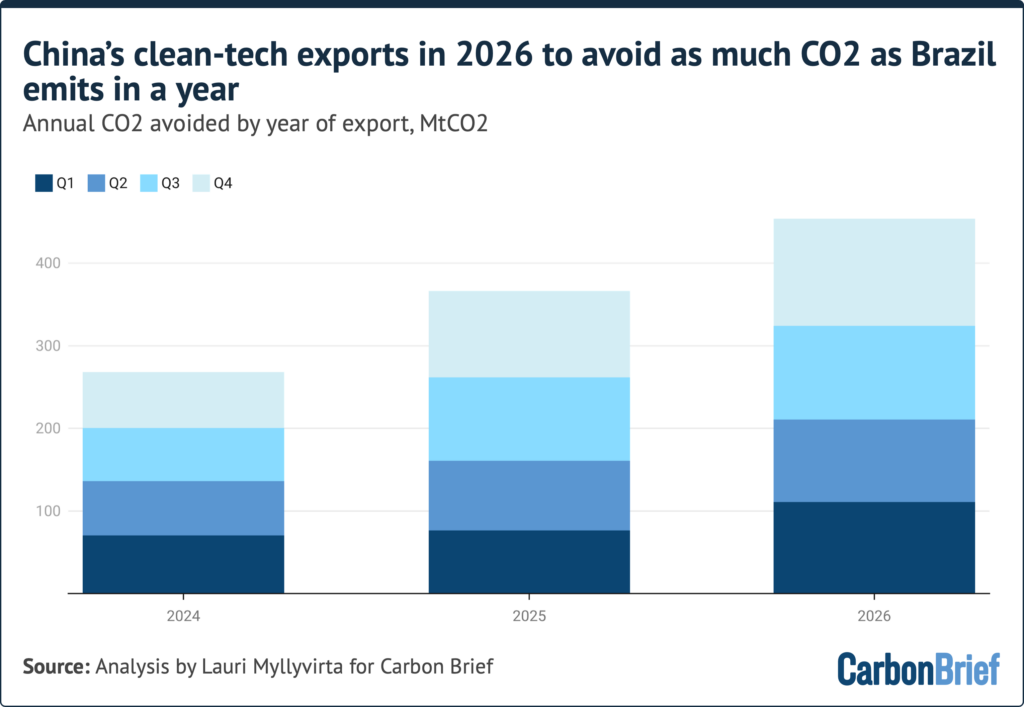
The analysis accounts for the impact of the clean-tech exports in the destination country, as well as the emissions due to manufacturing the products in China.
Looking at the full-year data for 2025, manufacturing clean-energy equipment resulted in emissions of around 170MtCO2 within China, while avoiding 370MtCO2 in other countries. This implies that, in aggregate, it takes six months for the exported goods to pay back the CO2 from manufacturing.
Solar exports are the biggest enabler
China’s solar-equipment exports continue to be the biggest enabler of decarbonisation in other countries, according to the analysis.
In the full-year data for 2025, China exported finished solar panels and intermediate products that correspond to a total generating capacity of 436 gigawatts (GW) once assembled and installed.
(Note that this is measured in gigawatts DC, which reflects the capacity of the panels, whereas capacity measured in AC refers to the size of the wire that connects them to the grid.)
In addition, China exported 8GW of wind turbines. Together with the solar equipment, this will generate approximately 720 terawatt-hours (TWh) of electricity per year, based on the average output per unit of capacity for solar and wind in each destination country.
For 2026, China’s exports of wind and solar equipment are on track to generate approximately 800TWh of electricity, equivalent to the generation from around 100 coal-fired power plants.
Over their lifetimes, based on the power sources expected to be displaced in each destination country, the solar exports in 2025 will avoid an estimated 6,400MtCO2.
(For more details on the basis for these calculations, see: About the data.)
Solar is therefore the largest source of lifetime avoided CO2 emissions by far, with wind-turbine exports in second place displacing just 180MtCO2, as shown in the figure below.
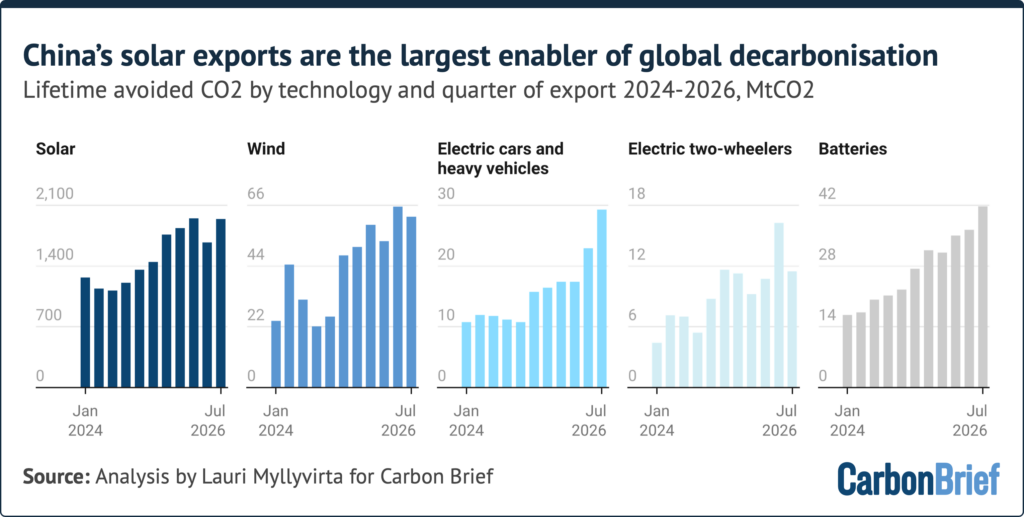
The 39m electric vehicles exported from China in 2025 included 36m two-wheelers, 2.2m battery electric cars, 160,000 plug-in hybrid cars, 15,000 buses and 30,000 trucks.
In addition, China exported batteries with a capacity of 305 gigawatt-hours (GWh) in 2025, enough to power another 5m battery electric cars once installed, based on typical battery sizes.
Based on typical driving distances and fuel consumption for corresponding fuel-burning vehicles, as well as the CO2 intensity of the electricity grid in destination countries, the EVs and batteries exported in 2025 will avoid an estimated 170MtCO2 over their lifetimes.
Given the sheer number of electric two-wheelers, the amount of oil and resulting CO2 they displace is a key uncertainty. Real–world e-bike studies support an assumption that roughly half of e-bike travel displaces the use of motor vehicles, either cars or motorbikes depending on location.
This suggests that, when taking into account the electricity grid in importing nations, China’s electric two-wheeler exports in 2025 will avoid an estimated 40MtCO2 over their lifetimes.
Global South dominates avoided emissions
In 2025, some 73% of the lifetime emissions avoided by China’s clean-tech exports were in global-south countries, which also accounted for 87% of the growth year-on-year.
In the first three quarters of 2026, global-south countries were responsible for almost all of the increase in avoided emissions compared with a year earlier, as shown in the figure below.
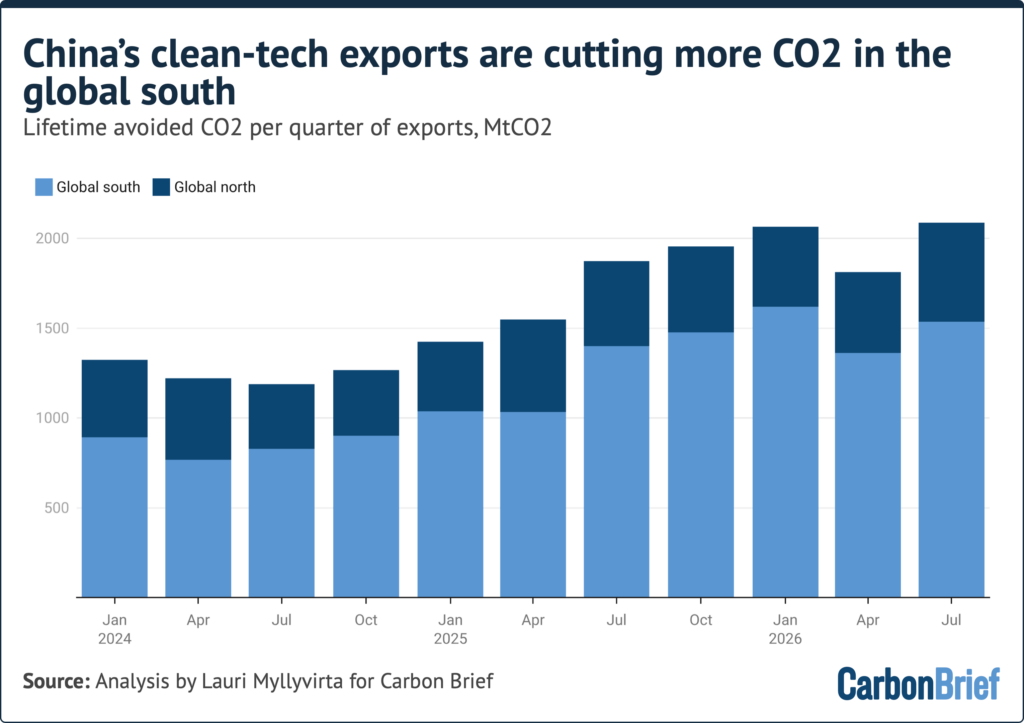
The high share of the global south in avoided emissions reflects large export volumes and power grids that are more carbon-intensive on average, as well as better average solar conditions that result in larger avoided emissions for each gigawatt of solar exported.
Clean-tech exports span the globe
On the regional level, South Asia has the largest avoided emissions due to imports of Chinese clean-tech, with strong year-on-year growth both in 2025 and the first three quarters of 2026.
Other top regional destinations in 2026 to date, in terms of lifetime avoided emissions, include south-east Asia, North America, Europe and the Middle East.
However, the exports span the globe, as shown in the map below, avoiding billions of tonnes of CO2 across every continent and in nearly every country of the world.
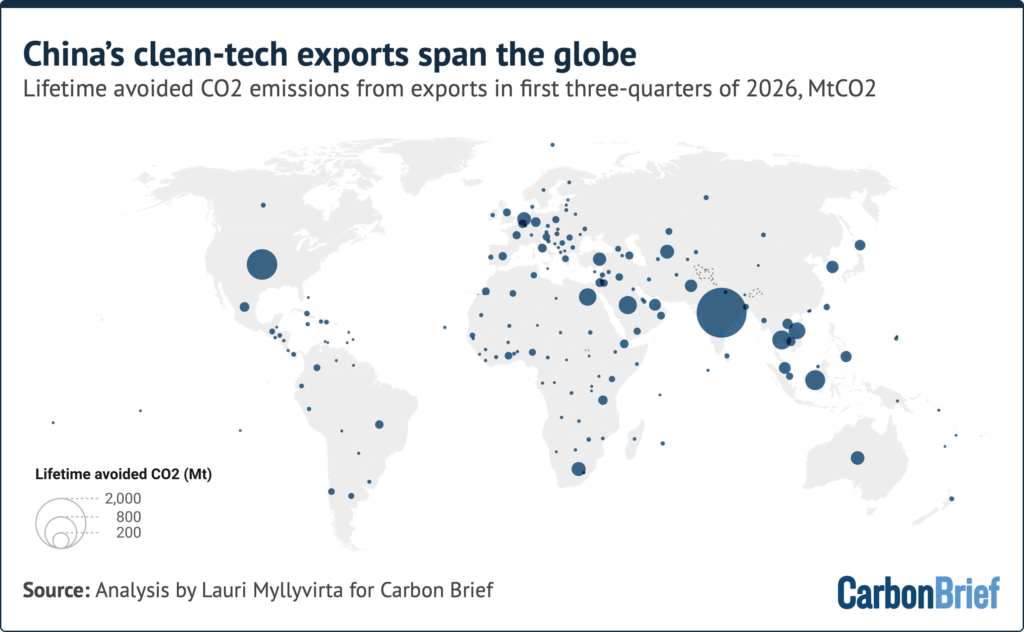
Among countries, the US has the second-largest avoided emissions after India. It registered a further increase of 12% in 2026, despite increased tariffs, and exceeds the EU as a bloc. The US is followed by Thailand, Saudi Arabia, South Africa and Australia.
The EU imports more of every clean energy technology than the US, but the US has higher avoided emissions. This is because average US solar output per unit of capacity is higher – as is the average CO2 intensity of power generation. As a result, every gigawatt of solar installed in the US results in three-times more avoided CO2 emissions than in the EU.
The resilience of Chinese clean-tech exports to the US indicates strong demand for the technology, despite the Trump administration’s steps to slow down deployment and discourage imports.
The data suggests that reducing reliance on technology supply from China – a policy aim of recent administrations from both parties – is likely to require scaling up of domestic and third-country manufacturing of the key technologies, in order to meet that resilient demand.
The largest change in the national rankings for avoided emissions from clean-tech exports in 2026, compared with the previous year, has been a fall in exports to the Gulf countries affected by the war in the region.
For electric cars and heavy vehicles, western Europe was the largest destination in the first three quarters of 2026, followed by Latin America and south-east Asia, both of which more than doubled, reflecting the impact of the oil crisis. Exports to the EU gained 39%.
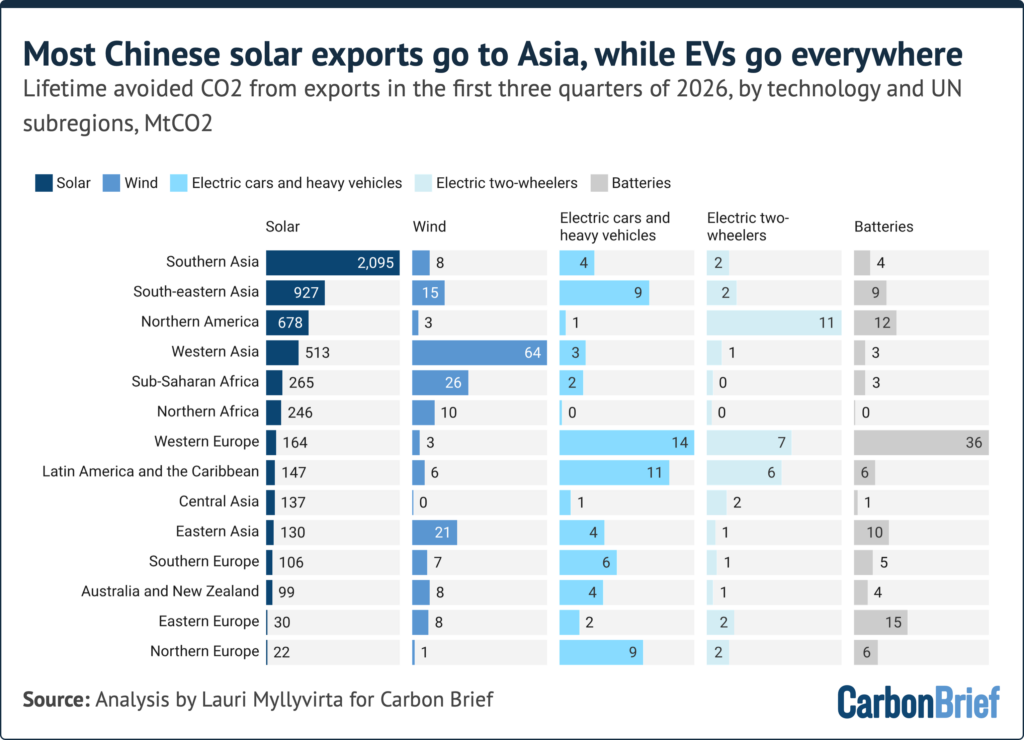
When including batteries and electric two-wheelers, North America and Europe are the largest destinations for avoided emissions due to EV-related exports, followed by Latin America and south-east Asia.
Exports of Chinese solar equipment to the US rose 13% year-on-year in the first three quarters of 2026, once re-routing through different channels is considered. This is a reversal of the dip early in the year, due to a sharp increase in tariffs in June 2025. Exports of EVs and batteries to the US also increased slightly, by 3% in the first three quarters of 2026.
Overseas clean energy projects double over three years
In addition to its clean-tech exports, China is also increasingly becoming directly involved in the development of overseas clean-energy projects.
This can be traced back to the 2021 pledge by Chinese president Xi Jinping, in which he said:
“China will step up support for other developing countries in developing green and low-carbon energy, and will not build new coal-fired power projects abroad.”
As of July 2026, some 69GW of China-linked renewable energy projects were in operation overseas. An additional 100GW are being built, with 280GW in planning but not yet under construction. This renewable energy capacity is supported by 3.5GW of China-linked energy storage projects in operation, with a further 21.4GW of storage in the pipeline.
China has also financed and built six operating nuclear reactors overseas, with a total capacity of 3.3GW. These are all located in Pakistan and, in 2023, they had a total generation of 26TWh. China began construction on the 1.2GW Chashma-5 reactor in 2024, also in Pakistan, with the plant expected to be operational around 2030.
The expected electricity output of China’s newly operating overseas clean-power projects doubled from 2022 to 2025, with a further 6% year-on-year increase in the first seven months of 2026.
The countries with the largest estimated generation from China-linked clean-power capacity are Indonesia, Vietnam, Bangladesh, Mongolia, Zimbabwe, Laos, Turkey and South Africa.
The list looks slightly different when considering the impact of operating, under construction or planned China-linked capacity on avoided CO2 emissions.
As shown in the figure below, Saudi Arabia, Uzbekistan, Indonesia and Pakistan are expected to see the largest avoided CO2, once under-construction projects are completed.
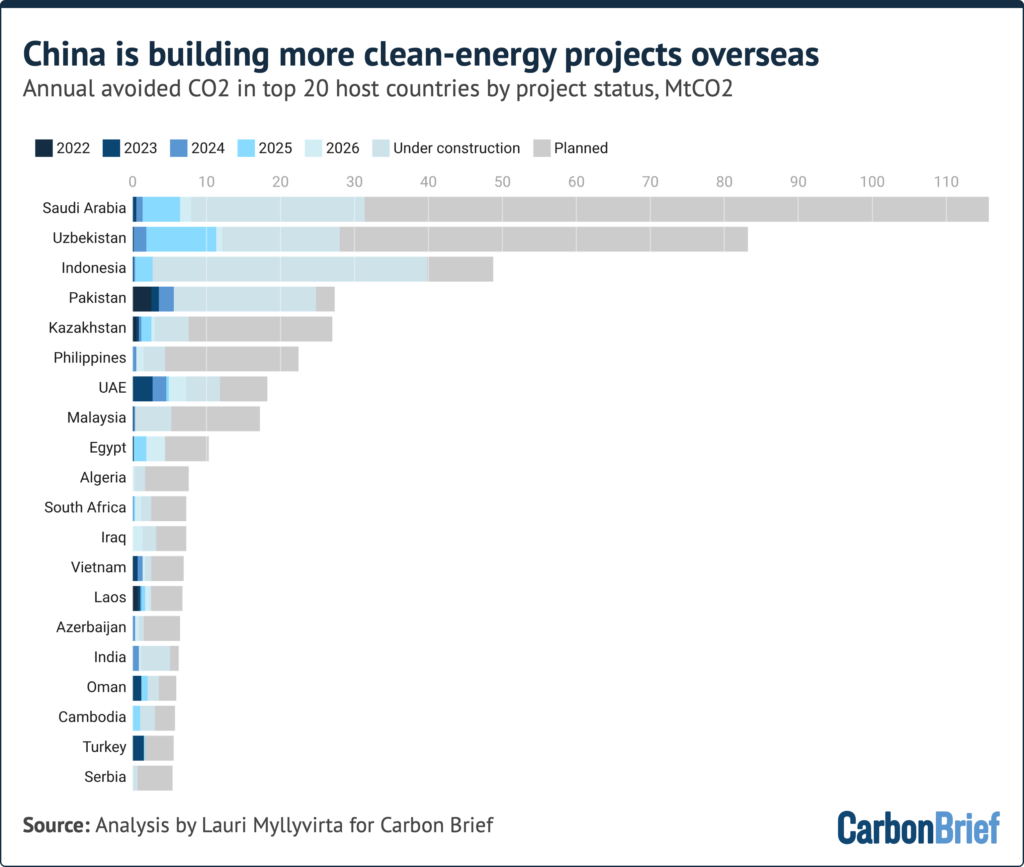
The increase in overseas clean-energy projects has changed China’s role in the power-sector development of other emerging countries. Having previously been the main financier of coal-power projects, it is now an important force in developing clean-power generation.
Nevertheless, there are gaps in the implementation of Xi’s pledge to end overseas coal-power development, which could be seen to affect its effectiveness and credibility. These gaps are particularly with respect to “captive” coal-power plants linked to industrial projects in Indonesia.
China’s overseas clean-energy project portfolio is growing, but remains small compared with the country’s equipment exports. For example in 2025, some 8.4GW of solar-power projects with Chinese financing or involvement entered operation and 18GW were newly announced. That year, China also exported 436GW of solar panels and intermediates.
This implies that financing, project development and construction using solar panels and other clean-tech from China is overwhelmingly carried out by local and other non-Chinese actors.
China’s exports enable market growth
A key concern in countries around the world is that Chinese industrial “overcapacity” is crowding out domestic industries, from automotive to steel or chemicals.
However, analysis of China’s clean-tech exports suggests that they have generally been additional, meaning they have not displaced exports by other producers. This could be a sign that China’s exports have either captured or enabled market growth for these clean-energy technologies.
For example, the value of EV exports from other countries has grown much more than those from China, as shown in the figure below. These EV exports have been led by the EU27 – particularly Germany – as well as Mexico, Japan, the UK and South Korea.
Similarly, there has been growth in the value of exports of heat pumps, solar inverters and electrolysers from both China and from other countries.
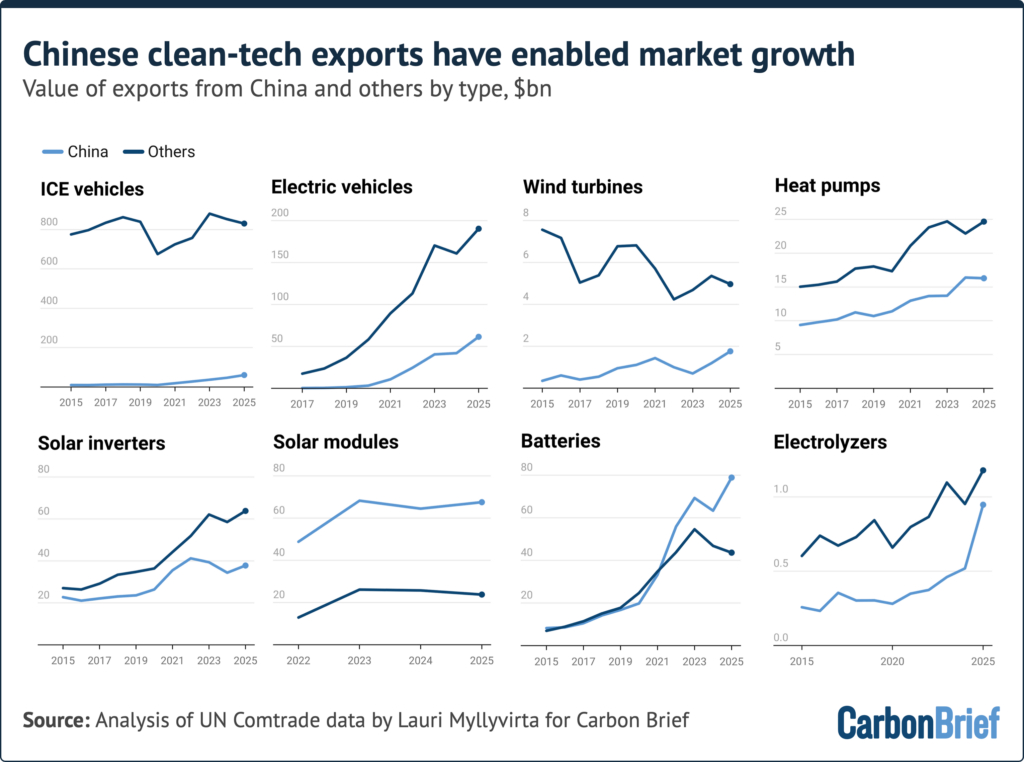
This pattern has not been universal. In the case of wind, China’s exports have grown while exports by other producers have declined, representing displacement on the global level.
However, on the level of importing countries, there has not been displacement. China’s wind-turbine exports have mostly headed to countries with growing markets, while incumbent producers have seen a decline in sales, in some of their previously important markets.
For some clean-tech, exports from other producers have displaced Chinese supply. For example, tariffs and restrictions on the use of Chinese components have seen other producers expanding into existing markets for solar panels, solar inverters and heat pumps.
At the same time, China’s exports of these technologies have been redirected into new markets, which previously imported little solar equipment.
Another indication of additionality is that Chinese clean-tech exports often target different market segments. For example, in the case of EVs, solar inverters and heat pumps, Chinese exports have much lower unit prices than equivalent exports from other producers.
Finally, it is worth noting that there has been much clearer displacement in the case of fuel-burning vehicles, where low-cost products from China have replaced exports from other suppliers.
Electrification export implications
China’s clean-tech exports have become a key enabler of the global clean-energy transition, driving down the cost, opening up new markets and responding to the rapid increase in demand.
China’s role as a major supplier of electrification technologies could give it a reason to support a push by the COP31 presidency for a global electrification target.
The country also has a large and growing role in financing and building clean-energy projects in many emerging countries, although this remains much smaller in scale than its exports.
When analysed on the country level, China’s clean-tech exports have, by and large, not displaced exports by other producers in absolute terms. Rather, it has captured market growth and opened up clean-energy development in countries that previously did not import the technologies at all.
However, the sharp drop in clean-tech prices means that exporters that have only held their sales volumes steady have seen the value of their exports dwindle. They have also lost market share to China’s exports. To retain market share, other exporters would need to expand production capacity.
Clean-energy technology has also become a cornerstone of China’s economy, responsible for 16% of all net growth in total exports in the first half of 2026, although the share fell in the third quarter due to the broad surge in exports, even as cleantech growth accelerated as well.
More broadly, clean energy sectors contributed a third of China’s GDP growth in 2025. This means that the country has a clear economic self-interest in the success of the global energy transition.
EV and wind deployment has continued to grow also in China domestically, but for solar and battery energy storage, the domestic market has dived after record volumes in 2025.
China’s domestic clean-energy market is larger than the export market for most technologies. Only 43% of solar cells and panels, 13% EVs, 17% of batteries and 7% of wind turbines produced in China were exported in 2025, highlighting the importance of the home market for producers.
For solar, however, exports continue to expand and could outweigh China’s domestic deployment after a slowdown in the sector in 2026. This could exacerbate overseas concerns about “unfair” trade practices, unless the domestic market picks up again.
About the data
This analysis estimates the fossil fuel and CO2 emissions avoided outside China as a result of China’s exports of solar, wind, electric-vehicle and battery technology.
Each exported unit of generating capacity is assumed to displace electricity from the grid of its destination country. Similarly, each exported electric vehicle is assumed to displace fuel in an equivalent internal-combustion vehicle.
Export volumes: Solar exports include finished modules as well as intermediates (wafers and cells), each expressed by Ember as finished-panel-equivalent gigawatts, with data taken from Ember’s China solar exports tracker. Wind and battery export totals are taken from Chinese industry bodies the China Wind Energy Association (CWEA) and the China Automotive Battery Innovation Alliance (CABIA). They are distributed across destination countries and months using customs-value shares from Ember’s China clean-tech exports tracker. Electric-vehicle volumes use vehicle counts from China Customs. Exports to Hong Kong are excluded and replaced with Hong Kong’s onward re-exports, treated as Chinese exports.
Avoided emissions: For each technology, the analysis combines the destination country’s average capacity factor and grid CO2 intensity, both derived from Ember’s yearly electricity data. Missing or implausible values are filled with UN sub-regional and then global medians, while all EU destinations are assigned the EU-average grid to correct for re-export hubs such as the Netherlands. For vehicles and batteries, avoided oil and CO2 is estimated based on per-vehicle assumptions compiled from the literature, net of charging emissions at the destination grid. Electric two-wheelers are credited with displacing conventional two-wheeler use for 48% of their travel. Lifetime figures multiply annual avoided emissions by assumed operating lives of 20 years for solar and wind, 10 for vehicles and batteries, or five for two-wheelers. “Embodied” manufacturing emissions are subtracted from these totals. Manufacturing emissions are calculated using average Chinese emission intensities compiled from the literature. National emissions used for comparison are from the Energy Institute statistical review of world energy.
Attributing solar exports to final markets: Because customs data records only a shipment’s first destination, the analysis traces Chinese wafers, modules and cells to their final destination using UN Comtrade bilateral import data. It identifies countries that import large amounts of solar modules and intermediates from China and export them further, classifying these onward exports as exports of Chinese goods, as long as they do not exceed the volume each country imported from China. It converts customs values to capacity using Ember’s monthly module and cell prices.